 Automotive Powertrain Sensors Market
 Outlook 2025
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 211

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Automotive Powertrain Sensors Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2026 | 21.10 B |
| 2027 | 22.90 B |
| 2028 | 24.90 B |
| 2029 | 27.00 B |
| 2030 | 29.40 B |
| 2031 | 31.90 B |
| 2032 | 34.60 B |

The automotive powertrain sensors market covers devices that measure temperature, pressure, position, speed, current, voltage, torque and exhaust composition within engine, drivetrain and exhaust subsystems. These sensors feed real-time data to electronic control units governing combustion, energy management, emissions after-treatment and electric drive efficiency across ICE, hybrid and battery-electric vehicles.
This analysis covers OEM and aftermarket powertrain sensor hardware across passenger cars, two-wheelers and commercial vehicles, segmented by sensor type, powertrain subsystem, propulsion and region. It addresses revenue forecasts from 2026 to 2033. This analysis does not cover ADAS perception sensors, chassis or body electronics, infotainment, or semiconductor wafer-level supply economics.
Estimates diverge materially because publishers define sensor scope differently — some count only pressure, temperature, position and speed sensors, while broader definitions include current, torque and exhaust chemistry sensing across electrified architectures.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 21.1 Billion | 2026 | 2033 (37.7 Billion) | 8.6% | Full sensor suite incl. current, torque, exhaust | One published estimate |
| 24.9 Billion | 2026 | 2033 (42.9 Billion) | 8.0% | Pressure, temperature, position, speed emphasis | A competing analysis |
| 7.5 Billion | 2025 | 2033 (16.1 Billion) | 10.0% | Narrow sensor-only hardware framing | A third published estimate |
Our analysis suggests the 21–25 Billion band is most defensible for 2026, because both larger estimates explicitly include current and torque sensing tied to electrification. The 7.5 Billion figure likely captures a narrower hardware definition and should not be used for capital allocation or capacity planning without scope reconciliation.
Segmentation below excludes geography. Sensor type is the primary axis, with powertrain subsystem and propulsion acting as cross-cutting demand multipliers as electrified platforms add sensing content.
| Parent segment | Children |
|---|---|
| Sensor Type | Temperature, Pressure, Position, Speed, Current, Voltage, Torque, Exhaust, Others |
| Powertrain Subsystem | Engine, Drivetrain, Exhaust |
| Vehicle Type | ICE Vehicles, Hybrid Vehicles, Electric Vehicles |
| Propulsion (alt. cut) | ICE, Hybrid, Battery Electric, Fuel Cell |
| End Market | OEM, Aftermarket |
The key structural insight: sensor type is where pricing power concentrates, while vehicle type determines volume trajectory. Suppliers positioned only in temperature and pressure face commoditization; those adding current and torque sensing capture electrification premium.
Asia Pacific leads with roughly 47% of global revenue, reflecting concentrated vehicle production in China, Japan, India and South Korea plus localized sensor manufacturing ecosystems and aggressive EV incentives.
| Region | Market Share (%) |
|---|---|
| North America | 0.17% |
| Europe | 0.21% |
| Asia-Pacific | 0.47% |
| South America | 0.05% |
| Middle East & Africa | 0.1% |
| Region | Share |
|---|---|
| Asia-Pacific | 47% |
| Europe | 21% |
| North America | 17% |
| Middle East & Africa | 10% |
| South America | 5% |
Europe's 21% share is disproportionately high relative to its production volume, reflecting Euro 7-driven sensor density. This divergence implies European platforms will carry higher sensor content per vehicle than global average through 2033.
Regulatory compliance is the single strongest driver, directly linking emission-standard stringency to sensor penetration across nearly all OEM platforms. Electrification adds a second, independent demand layer that did not exist a decade ago.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Emission regulation (EPA, EU 2024/1257, Bharat Stage VI) | Driver | High | Mandates real-time exhaust and combustion monitoring |
| Electrification and hybrid mix shift | Driver | High | Adds current, voltage, torque sensing per vehicle |
| ADAS and V2X integration | Driver | Medium | Requires high-accuracy powertrain data feeds |
| Predictive maintenance via cloud analytics | Driver | Medium | Sustains sensor data demand post-warranty |
| Cybersecurity and data privacy compliance | Restraint | Medium | Adds 15–20% compliance cost for smaller suppliers |
| Harsh-environment sensor failure rates | Restraint | Medium | Warranty exposure; 22% of ICE claims cited |
The balance favors growth: regulatory drivers are legally binding and non-discretionary, whereas cybersecurity costs are manageable at scale. Our analysis suggests the restraint most likely to bite is not regulation but supplier capability — mid-tier vendors lacking solid-state high-temperature designs will lose share as OEMs consolidate approved-vendor lists.
| Company | Primary strength | Strategic position |
|---|---|---|
| Bosch | Broad powertrain sensor portfolio, smart sensor platforms | Scale leader, systems integration |
| Continental | Engine and exhaust sensing, emission compliance | Tier-1 incumbent |
| Denso | Japanese OEM embeddedness, thermal sensing | Asia-anchored leader |
| Sensata | Pressure and position sensing at volume | Specialist scale player |
| Infineon | Current and magnetic sensing semiconductors | Electrification beneficiary |
| TE Connectivity | Connectivity-integrated sensor assemblies | Adjacent entrant |
Differentiation rests on three moats: validated harsh-environment reliability (800°C+ exhaust and turbo zones), OEM design-in cycles that lock suppliers for platform lifecycles, and vertical semiconductor control that protects margin during current-sensor demand surges. Our analysis suggests Infineon and TE are structurally advantaged in electrified powertrains, while incumbents defend through compliance-driven engine sensing revenue that persists well into the hybrid transition.
Selection criteria should prioritize validated operating envelopes over headline specifications: exhaust and turbo sensors must survive thermal cycling, chemical exposure and vibration simultaneously, and failure here drives disproportionate warranty cost. Procurement teams should verify qualification data at 650–800°C rather than accept datasheet ratings.
Switching costs are substantial. Platform design-in cycles span three to five years, and re-qualification for emission-critical sensors can add six to twelve months. Buyers should therefore treat single-source exposure on current and exhaust sensors as a strategic risk, not a tactical one. Regulatory compliance is non-negotiable — a degraded oxygen sensor can multiply NOx emissions several-fold, exposing OEMs to certification and recall liabilities.
Operators should also model total cost of ownership rather than unit price: solid-state sensor adoption reduces failure rates meaningfully, and the avoided warranty and downtime cost typically outweighs the premium. Finally, dual-sourcing strategies in Asia Pacific reduce supply-chain exposure while preserving cost advantage.
The balance of evidence favors a structural growth thesis, not a cyclical one. Sensor content per vehicle is rising independently of unit volume, because electrified and hybridized powertrains require sensing architectures that ICE platforms never needed. Even in a flat global production scenario, revenue would expand through content growth alone.
The strongest counter-argument is scope inflation: some published estimates may double-count sensors reclassified from adjacent categories, and the wide spread between the 7.5 Billion and 24.9 Billion figures shows definitional risk is real. We acknowledge this, but note that the two largest estimates converge within 15% of each other, which strengthens rather than weakens confidence in the 21–25 Billion band.
The evidence that would change our conclusion is a sustained decline in hybrid and EV production mix, or a regulatory rollback in major markets — neither is visible in current policy trajectories.
While this overview establishes the strategic frame, precise sub-segment forecasting, vendor share by sensor type, and platform-level content modeling require the full report's granular datasets.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.6% from 2020-2034 |
| Segmentation |
|
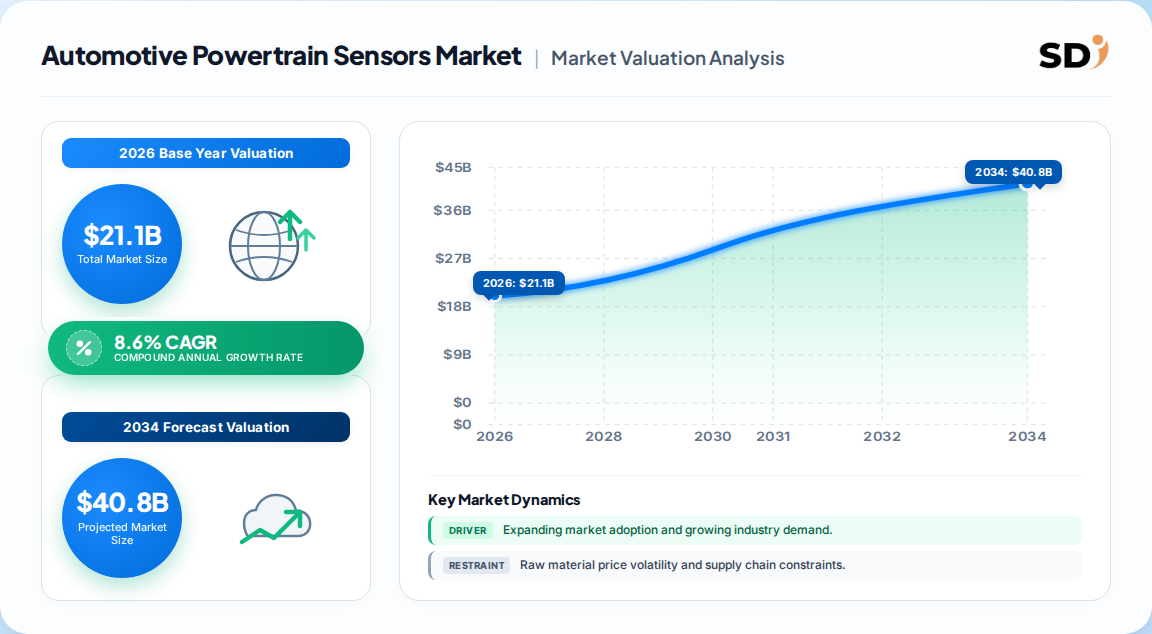
The market is estimated at 21.1 Billion in 2026, with scope covering sensor hardware across ICE, hybrid and electric powertrains globally. Expansion to 37.7 Billion by 2033 implies a 8.6% CAGR.
Asia Pacific leads with roughly 47% of global revenue, driven by concentrated vehicle production in China, Japan, India and South Korea, plus localized sensor manufacturing and EV incentives. Europe and North America follow.
Current sensors grow fastest at 9.2% CAGR, fueled by electrification and the rising complexity of EV battery and power management systems. Temperature sensors remain the largest segment with over 25% revenue share.
Stringent emission regulations are the dominant driver, mandating real-time exhaust and combustion monitoring. Electrification adds a second layer, requiring current, voltage and torque sensing that ICE platforms never needed.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research process applies a 70/30 primary-to-secondary split, prioritizing direct verification of capacity, pricing and qualification timelines. In-depth interviews were conducted across the value chain with sensor semiconductor suppliers, specialized sensor module producers, contract manufacturing partners and global automotive distributors. Within these organizations we engaged decision-makers including VP-level Sourcing leads, Heads of Sensor R&D, Technical Directors responsible for emission compliance validation, and Commercial Operations Leads managing OEM design-in cycles.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 30% |
| R&D & Technical Directors | 35% |
| Regulatory Compliance Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Sensor Semiconductor Suppliers | 35% |
| Specialized Sensor Module Producers | 40% |
| Contract Manufacturers | 15% |
| Global Automotive Distributors | 10% |
Findings are cross-validated against official multilateral databases including UN Comtrade, WTO tariff schedules, US ITC trade data and Eurostat automotive component flows. Corporate annual filings, 10-K submissions and investor presentations inform capacity and revenue baselines. Patent databases and published technical standards from ISO and SAE provide qualification and performance parameters for harsh-environment sensing.
We run simultaneous Top-Down modeling, allocating macroeconomic vehicle production and powertrain mix to sensor content per platform, and Bottom-Up modeling based on manufacturer capacity, unit pricing and end-use consumption. Divergence between the two approaches is reconciled through analyst review before any figure is published.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |