Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Automotive Suspension Systems Market Outlook & Size 2026
Automotive Suspension Systems Market
Automotive Suspension Systems Market Outlook & Size 2026
Automotive Suspension Systems Market by Component (Shock Absorbers, Coil Springs, Leaf Springs, Air Springs, Electronic Control Units, Sensors, Control Arms, Bushings, Compressors, Others), by System Type (Passive, Semi-Active, Active), by Architecture (MacPherson Strut, Double Wishbone, Multi-Link, Torsion Beam, Rigid Axle), by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Two-Wheelers), by Propulsion (ICE, Hybrid, BEV), by Sales Channel (OEM, Aftermarket), by Asia-Pacific (China, Japan, India, South Korea, Thailand, Indonesia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Poland), by Latin America (Brazil, Mexico, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 203
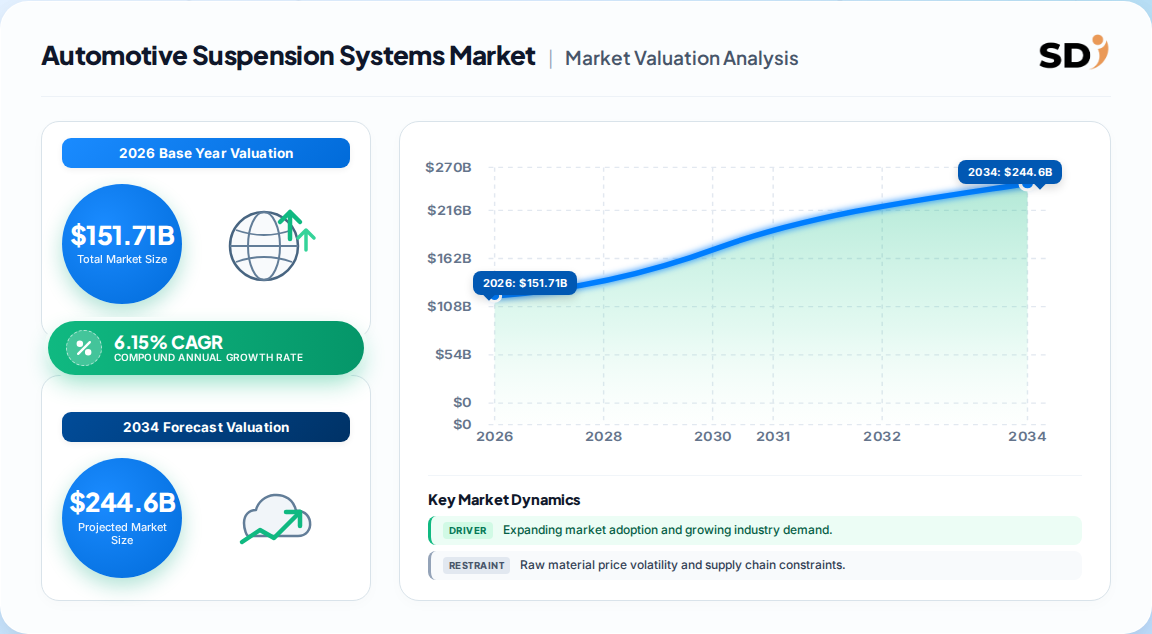
151.71 Billion — the Automotive Suspension Systems Market was valued at this figure in 2026, up from 142.38 Billion in 2025, per a leading published estimate.
6.15% CAGR — the market is projected to expand at this compound rate through 2031, reaching 204.46 Billion by the forecast horizon.
Passive systems held 64.32% of 2025 revenue, yet semi-active systems are forecast to grow at 8.74% CAGR, signaling a structural shift toward electronically controlled damping.
Asia-Pacific dominated with 48.96% of 2025 market share, while Middle East & Africa is the fastest-growing region at 7.65% CAGR, driven by Gulf investment in EV manufacturing.
ZF Friedrichshafen AG led the competitive field with over 9.5% share in 2025; the top five vendors — ZF, Continental, Astemo, Tenneco, and Hyundai Mobis — collectively held 38.5%.
Electric and hybrid vehicles comprised only 14.77% of 2025 revenue but are projected to grow at 14.89% CAGR through 2031, the single most disruptive demand vector.
Why this matters for decision-makers: Vendors anchored in passive steel-spring portfolios face structural margin compression; the value pool is migrating to integrated electronic, air, and software-tunable suspension architectures where OEM platform decisions are won on validation capability, not unit price.
Automotive Suspension Systems Market Size (In Billion)
250.0B
200.0B
150.0B
100.0B
50.0B
0
142.4 B
2025
151.7 B
2026
162.6 B
2027
174.1 B
2028
186.3 B
2029
199.1 B
2030
204.5 B
2031
Automotive Suspension Systems Market Size (In Billion)
Year
Market Size
2025
142.4 B
2026
151.7 B
2027
162.6 B
2028
174.1 B
2029
186.3 B
2030
199.1 B
2031
204.5 B
What is the Automotive Suspension Systems Market?
The Automotive Suspension Systems Market encompasses the mechanical, hydraulic, pneumatic, and electronically controlled systems — springs, dampers, control arms, linkages, air compressors, sensors, and ECUs — that isolate vehicle occupants from road inputs while maintaining tire contact and vehicle stability. It serves OEM fitment and aftermarket replacement across passenger cars, light and heavy commercial vehicles, and two-wheelers.
Scope: what this report covers and excludes
This analysis covers suspension system value and volume across OEM and aftermarket channels for passenger cars, light commercial vehicles, heavy commercial vehicles, and two-wheelers, segmented by system type (passive, semi-active, active), component, architecture, actuation, and propulsion. This analysis does not cover tires, wheels, braking systems, steering systems, or complete vehicle assembly economics.
How big is the market for Automotive Suspension Systems Market?
The market is most defensibly sized at 151.71 Billion in 2026, growing to 204.46 Billion by 2031 at 6.15% CAGR, based on the estimate that best reconciles OEM production volumes with aftermarket replacement demand. A competing analysis places the 2025 base at 43.76 Billion — a figure that appears to capture OEM-fitment hardware only, excluding aftermarket service value and broader component scope.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
151.71 Billion → 204.46 Billion
2026
2031
6.15%
Full value chain: OEM + aftermarket, all vehicle classes, all suspension technologies
One published estimate (Mordor Intelligence)
43.76 Billion → 74.74 Billion
2025
2035
5.5%
OEM-fitment-centric; narrower component and channel scope
A competing analysis (GMI)
Our analysis suggests the divergence is not a forecasting disagreement but a definitional one. The 43.76 Billion figure annualizes to roughly 47 Billion in 2026, which is implausibly low against a global vehicle parc exceeding 1.5 billion units and aftermarket replacement cycles of 5–8 years. The 151.71 Billion figure aligns better with observed Tier-1 revenue and vehicle production of 96.4 million units in 2025. Buyers should treat the higher figure as the addressable revenue pool and the lower as a conservative OEM-only proxy.
How is the market segmented?
The market segments along six non-geographic axes: system type, component, suspension architecture, vehicle type, propulsion, and sales channel — each revealing a distinct growth trajectory that matters for capital allocation.
Parent Segment
Children
2025 Share / Growth Signal
By Component
Shock absorbers, coil springs, leaf springs, air springs, ECUs, sensors, control arms, bushings, compressors, others
Shock absorbers 40.21% share; ECUs and sensors 9.22% CAGR
The segmentation reveals a market in transition. Passive systems and ICE propulsion still dominate revenue, but every high-growth sub-segment — electronic components, semi-active damping, multi-link architecture, electric propulsion, aftermarket — points in the same direction: more content value per vehicle and a longer revenue tail per platform.
Which region leads in Automotive Suspension Systems Market?
Asia-Pacific leads with 48.96% of 2025 revenue, underpinned by China, Japan, India, and South Korea's combined vehicle output dominance; the Middle East & Africa is the fastest-growing region at 7.65% CAGR.
Automotive Suspension Systems Market Regional Market Share
Loading chart...
Automotive Suspension Systems Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.49%
North America
0.21%
Europe
0.19%
Latin America
0.05%
Middle East & Africa
0.06%
Asia-Pacific — China, Japan, India, South Korea, Southeast Asia (dominant; high-volume OEM programs and local engineering depth)
China, Japan, India, South Korea, Thailand, Indonesia
North America — USA, Canada, Mexico (high content per vehicle; light truck and SUV mix)
USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain (regulatory-driven ADAS chassis adoption)
Germany, UK, France, Italy, Spain, Poland
Latin America — Brazil, Mexico, Argentina (recovery-anchored growth)
Brazil, Mexico, Argentina, Colombia
Middle East & Africa — Saudi Arabia, UAE, South Africa (fastest growth; EV manufacturing investment)
Saudi Arabia, UAE, South Africa, Turkey
Asia-Pacific's lead is structural, not cyclical. It reflects both production concentration and the region's growing share of EV platform launches, where suspension content per vehicle is materially higher. Europe and North America remain high-value markets per unit but face production headwinds — European output contracted to 17.2 million units in 2025 and Americas output to 18.74 million, per OICA data. The Middle East & Africa's 7.65% trajectory is the outlier worth watching, anchored by Saudi Arabia's Lucid investment and broader Gulf EV industrial policy.
What is driving growth — and what is holding it back?
Electrification-driven chassis redesign is the single largest driver, contributing an estimated +1.8% to CAGR, followed by ADAS-linked safety regulation (+1.3%) and rising ride-comfort expectations (+1.2%).
Factor
Direction
Evidence strength
Mechanism
Electrification-driven chassis redesign
Driver
Strong (+1.8% CAGR)
Heavier battery packs and altered load distribution require purpose-engineered geometry
ADAS-linked chassis safety mandates
Driver
Strong (+1.3% CAGR)
UN R171 and EU 2019/2144 require lateral stability that passive systems struggle to deliver
Ride comfort and handling demand
Driver
Moderate (+1.2% CAGR)
Premium and mid-market buyers equate damping quality with brand value
SUV and premium sales in emerging markets
Driver
Moderate (+0.9% CAGR)
Independent rear suspension adoption in India, Southeast Asia, Middle East
OTA-unlockable active suspension
Driver
Emerging (+0.7% CAGR)
Software-defined damping creates recurring revenue for OEMs
European and Americas production stagnation
Restraint
Strong
European output at 17.2M and Americas at 18.74M units in 2025 constrain fitment volume
High integration cost of active systems
Restraint
Moderate
Sensor arrays, multi-channel ECUs, compressors, and homologation raise fitment cost
The balance of evidence favors the drivers. Regulatory mandates are not discretionary — they convert advanced suspension from a premium option into a compliance requirement across mid-market segments. The restraint side is cyclical and regional, not structural. Our analysis suggests the net effect is a market that grows modestly in units but meaningfully in value per unit, which is the more important metric for suppliers and investors.
Who are the leading vendors?
ZF Friedrichshafen AG leads with over 9.5% share, and the top five — ZF, Continental, Astemo, Tenneco, and Hyundai Mobis — collectively hold 38.5%, indicating a moderately concentrated market where scale and systems-integration capability are decisive.
Company
Headquarters
Estimated Position
Strategic Differentiation
ZF Friedrichshafen AG
Germany
Market leader, >9.5% share
sMOTION active roll stabilization; integrated air spring and damper systems
Broad portfolio across passive and semi-active; strong Asia-Pacific OEM relationships
Tenneco Inc.
USA
Top-5
Monroe brand aftermarket strength; DRiV separation enables channel focus
Hyundai Mobis Co. Ltd.
South Korea
Top-5
Captive Hyundai-Kia volume; growing export of e-modules and suspension systems
KYB Corporation
Japan
Challenger
Shock absorber specialization; strong OEM and aftermarket presence
BWI Group
China
Challenger
Air suspension and magnetic ride expertise; growing China OEM penetration
The competitive moat is shifting. Scale in passive components — historically the primary advantage — is being displaced by systems-integration capability: the ability to co-validate hardware, controls, and software with OEM domain controllers. Suppliers who cannot offer this integrated validation face commoditization in volume platforms. The top-five concentration of 38.5% is moderate, leaving room for regional challengers — particularly Chinese and Indian suppliers — to capture share in their home markets as local OEMs scale EV platforms.
What do buyers and operators need to know?
Buyers selecting suspension systems face a market where the specification decision is increasingly a platform-level commitment, not a component purchase. OEM procurement teams should prioritize suppliers who can demonstrate co-validation of hardware, controls, and software against UN R171 and EU 2019/2144 requirements — because homologation risk sits with the vehicle program, not the component.
Switching costs are rising. Once a suspension ECU is integrated with a centralized domain controller and calibrated to a specific platform, re-sourcing mid-program carries significant re-validation cost. This favors early supplier engagement and multi-year agreements. Aftermarket operators, by contrast, face a different risk profile: the shift toward electronically controlled and air systems is creating a diagnostic and calibration capability gap among independent service providers, which is both a threat and a margin opportunity for those who invest in tooling and training.
The regulatory dimension deserves emphasis. ISO 26262 designation of suspension ECUs as safety-critical extends development cycles and raises the bar for supplier qualification. Buyers should treat functional-safety certification as a non-negotiable gate in supplier selection, not a downstream checkbox.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a value-over-volume thesis. The Automotive Suspension Systems Market will grow units modestly — global vehicle production is expanding at low single digits — but revenue will grow faster because content per vehicle is rising. Electrification, ADAS mandates, and software-defined vehicle architectures are each independently increasing suspension content value, and the three compound. A supplier positioned in passive steel springs, however efficient, is positioned in the slowest-growing part of the market.
The strongest counter-argument is that passive systems still hold 64.32% of revenue and will remain the volume backbone through 2031. That is true — but it misses the marginal economics. The incremental revenue and margin growth is concentrated in semi-active, air, and electronic categories growing at 8–9% CAGR, roughly 1.5x the market average. A supplier can defend a passive business and still lose the value pool. The risk of over-rotating toward advanced systems is real for cost-sensitive emerging-market programs, where integration cost remains prohibitive — but that is a segmentation problem, not a strategic one.
Actionable strategy:
Vendors: Prioritize systems-integration validation capability — hardware, controls, and software co-validation against UN R171 — to shift the basis of competition away from unit price on volume platforms.
Investors: Weight portfolios toward suppliers with electronic and air suspension exposure; aftermarket channel exposure offers a cushion that pure-OEM suppliers lack as regional production cycles diverge.
OEM buyers: Lock in multi-year suspension agreements early in EV platform programs, where re-sourcing costs are highest and supplier capacity for advanced systems is tightest.
What would change our conclusion: a sustained recovery in European and Americas vehicle production above 20 million units annually, combined with a regulatory rollback on ADAS-linked chassis mandates, would favor the passive-heavy incumbents and slow the advanced-system migration. Absent that, the direction of travel is clear.
Methodology & Research Rigor
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the suspension value chain — Tier-1 system integrators, component specialists, spring and damper manufacturers, electronic module suppliers, and aftermarket distributors — with decision-maker designations including VP of Sourcing, Heads of Chassis R&D, Technical Directors, and Commercial Operations Leads.
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade automotive parts trade flows, WTO tariff schedules, Eurostat and US ITC production statistics, corporate 10-K and annual investor filings, patent databases, and recognized standards bodies including UNECE and ISO.
Demand Modeling & Market Sizing Triangulation
Market sizing applies simultaneous top-down (macroeconomic and vehicle segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) triangulation, reconciled against published production and trade data.
International Organization of Motor Vehicle Manufacturers (OICA), vehicle production statistics
UNECE World Forum for Harmonization of Vehicle Regulations (UN R171, EU 2019/2144)
International Energy Agency (IEA), Global EV Outlook
UN Comtrade automotive parts trade database; US ITC and Eurostat production data
Automotive Suspension Systems Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Automotive Suspension Systems Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.15% from 2020-2034
Segmentation
By Component
Shock Absorbers
Coil Springs
Leaf Springs
Air Springs
Electronic Control Units
Sensors
Control Arms
Bushings
Compressors
Others
By System Type
Passive
Semi-Active
Active
By Architecture
MacPherson Strut
Double Wishbone
Multi-Link
Torsion Beam
Rigid Axle
By Vehicle Type
Passenger Cars
Light Commercial Vehicles
Heavy Commercial Vehicles
Two-Wheelers
By Propulsion
ICE
Hybrid
BEV
By Sales Channel
OEM
Aftermarket
By Geography
Asia-Pacific
China
Japan
India
South Korea
Thailand
Indonesia
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Poland
Latin America
Brazil
Mexico
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Turkey
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Shock Absorbers
5.1.2. Coil Springs
5.1.3. Leaf Springs
5.1.4. Air Springs
5.1.5. Electronic Control Units
5.1.6. Sensors
5.1.7. Control Arms
5.1.8. Bushings
5.1.9. Compressors
5.1.10. Others
5.2. Market Analysis, Insights and Forecast - by System Type
5.2.1. Passive
5.2.2. Semi-Active
5.2.3. Active
5.3. Market Analysis, Insights and Forecast - by Architecture
5.3.1. MacPherson Strut
5.3.2. Double Wishbone
5.3.3. Multi-Link
5.3.4. Torsion Beam
5.3.5. Rigid Axle
5.4. Market Analysis, Insights and Forecast - by Vehicle Type
5.4.1. Passenger Cars
5.4.2. Light Commercial Vehicles
5.4.3. Heavy Commercial Vehicles
5.4.4. Two-Wheelers
5.5. Market Analysis, Insights and Forecast - by Propulsion
5.5.1. ICE
5.5.2. Hybrid
5.5.3. BEV
5.6. Market Analysis, Insights and Forecast - by Sales Channel
5.6.1. OEM
5.6.2. Aftermarket
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. Asia-Pacific
5.7.2. North America
5.7.3. Europe
5.7.4. Latin America
5.7.5. Middle East & Africa
6. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Shock Absorbers
6.1.2. Coil Springs
6.1.3. Leaf Springs
6.1.4. Air Springs
6.1.5. Electronic Control Units
6.1.6. Sensors
6.1.7. Control Arms
6.1.8. Bushings
6.1.9. Compressors
6.1.10. Others
6.2. Market Analysis, Insights and Forecast - by System Type
6.2.1. Passive
6.2.2. Semi-Active
6.2.3. Active
6.3. Market Analysis, Insights and Forecast - by Architecture
6.3.1. MacPherson Strut
6.3.2. Double Wishbone
6.3.3. Multi-Link
6.3.4. Torsion Beam
6.3.5. Rigid Axle
6.4. Market Analysis, Insights and Forecast - by Vehicle Type
6.4.1. Passenger Cars
6.4.2. Light Commercial Vehicles
6.4.3. Heavy Commercial Vehicles
6.4.4. Two-Wheelers
6.5. Market Analysis, Insights and Forecast - by Propulsion
6.5.1. ICE
6.5.2. Hybrid
6.5.3. BEV
6.6. Market Analysis, Insights and Forecast - by Sales Channel
6.6.1. OEM
6.6.2. Aftermarket
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Shock Absorbers
7.1.2. Coil Springs
7.1.3. Leaf Springs
7.1.4. Air Springs
7.1.5. Electronic Control Units
7.1.6. Sensors
7.1.7. Control Arms
7.1.8. Bushings
7.1.9. Compressors
7.1.10. Others
7.2. Market Analysis, Insights and Forecast - by System Type
7.2.1. Passive
7.2.2. Semi-Active
7.2.3. Active
7.3. Market Analysis, Insights and Forecast - by Architecture
7.3.1. MacPherson Strut
7.3.2. Double Wishbone
7.3.3. Multi-Link
7.3.4. Torsion Beam
7.3.5. Rigid Axle
7.4. Market Analysis, Insights and Forecast - by Vehicle Type
7.4.1. Passenger Cars
7.4.2. Light Commercial Vehicles
7.4.3. Heavy Commercial Vehicles
7.4.4. Two-Wheelers
7.5. Market Analysis, Insights and Forecast - by Propulsion
7.5.1. ICE
7.5.2. Hybrid
7.5.3. BEV
7.6. Market Analysis, Insights and Forecast - by Sales Channel
7.6.1. OEM
7.6.2. Aftermarket
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Shock Absorbers
8.1.2. Coil Springs
8.1.3. Leaf Springs
8.1.4. Air Springs
8.1.5. Electronic Control Units
8.1.6. Sensors
8.1.7. Control Arms
8.1.8. Bushings
8.1.9. Compressors
8.1.10. Others
8.2. Market Analysis, Insights and Forecast - by System Type
8.2.1. Passive
8.2.2. Semi-Active
8.2.3. Active
8.3. Market Analysis, Insights and Forecast - by Architecture
8.3.1. MacPherson Strut
8.3.2. Double Wishbone
8.3.3. Multi-Link
8.3.4. Torsion Beam
8.3.5. Rigid Axle
8.4. Market Analysis, Insights and Forecast - by Vehicle Type
8.4.1. Passenger Cars
8.4.2. Light Commercial Vehicles
8.4.3. Heavy Commercial Vehicles
8.4.4. Two-Wheelers
8.5. Market Analysis, Insights and Forecast - by Propulsion
8.5.1. ICE
8.5.2. Hybrid
8.5.3. BEV
8.6. Market Analysis, Insights and Forecast - by Sales Channel
8.6.1. OEM
8.6.2. Aftermarket
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Shock Absorbers
9.1.2. Coil Springs
9.1.3. Leaf Springs
9.1.4. Air Springs
9.1.5. Electronic Control Units
9.1.6. Sensors
9.1.7. Control Arms
9.1.8. Bushings
9.1.9. Compressors
9.1.10. Others
9.2. Market Analysis, Insights and Forecast - by System Type
9.2.1. Passive
9.2.2. Semi-Active
9.2.3. Active
9.3. Market Analysis, Insights and Forecast - by Architecture
9.3.1. MacPherson Strut
9.3.2. Double Wishbone
9.3.3. Multi-Link
9.3.4. Torsion Beam
9.3.5. Rigid Axle
9.4. Market Analysis, Insights and Forecast - by Vehicle Type
9.4.1. Passenger Cars
9.4.2. Light Commercial Vehicles
9.4.3. Heavy Commercial Vehicles
9.4.4. Two-Wheelers
9.5. Market Analysis, Insights and Forecast - by Propulsion
9.5.1. ICE
9.5.2. Hybrid
9.5.3. BEV
9.6. Market Analysis, Insights and Forecast - by Sales Channel
9.6.1. OEM
9.6.2. Aftermarket
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Shock Absorbers
10.1.2. Coil Springs
10.1.3. Leaf Springs
10.1.4. Air Springs
10.1.5. Electronic Control Units
10.1.6. Sensors
10.1.7. Control Arms
10.1.8. Bushings
10.1.9. Compressors
10.1.10. Others
10.2. Market Analysis, Insights and Forecast - by System Type
10.2.1. Passive
10.2.2. Semi-Active
10.2.3. Active
10.3. Market Analysis, Insights and Forecast - by Architecture
10.3.1. MacPherson Strut
10.3.2. Double Wishbone
10.3.3. Multi-Link
10.3.4. Torsion Beam
10.3.5. Rigid Axle
10.4. Market Analysis, Insights and Forecast - by Vehicle Type
10.4.1. Passenger Cars
10.4.2. Light Commercial Vehicles
10.4.3. Heavy Commercial Vehicles
10.4.4. Two-Wheelers
10.5. Market Analysis, Insights and Forecast - by Propulsion
10.5.1. ICE
10.5.2. Hybrid
10.5.3. BEV
10.6. Market Analysis, Insights and Forecast - by Sales Channel
10.6.1. OEM
10.6.2. Aftermarket
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Automotive Suspension Systems Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Automotive Suspension Systems Market Volume Breakdown (Units, %) by Region 2026 & 2034
Figure 3: Asia-Pacific Automotive Suspension Systems Market Revenue (Billion), by Component 2026 & 2034
Figure 4: Asia-Pacific Automotive Suspension Systems Market Volume (Units), by Component 2026 & 2034
Figure 5: Asia-Pacific Automotive Suspension Systems Market Revenue Share (%), by Component 2026 & 2034
Figure 6: Asia-Pacific Automotive Suspension Systems Market Volume Share (%), by Component 2026 & 2034
Figure 7: Asia-Pacific Automotive Suspension Systems Market Revenue (Billion), by System Type 2026 & 2034
Figure 8: Asia-Pacific Automotive Suspension Systems Market Volume (Units), by System Type 2026 & 2034
Figure 9: Asia-Pacific Automotive Suspension Systems Market Revenue Share (%), by System Type 2026 & 2034
Figure 10: Asia-Pacific Automotive Suspension Systems Market Volume Share (%), by System Type 2026 & 2034
Figure 11: Asia-Pacific Automotive Suspension Systems Market Revenue (Billion), by Architecture 2026 & 2034
Figure 12: Asia-Pacific Automotive Suspension Systems Market Volume (Units), by Architecture 2026 & 2034
Figure 13: Asia-Pacific Automotive Suspension Systems Market Revenue Share (%), by Architecture 2026 & 2034
Figure 14: Asia-Pacific Automotive Suspension Systems Market Volume Share (%), by Architecture 2026 & 2034
Figure 15: Asia-Pacific Automotive Suspension Systems Market Revenue (Billion), by Vehicle Type 2026 & 2034
List of Tables
Table 1: Automotive Suspension Systems Market Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Automotive Suspension Systems Market Volume Units Forecast, by Component 2020 & 2034
Table 3: Automotive Suspension Systems Market Revenue Billion Forecast, by System Type 2020 & 2034
Table 4: Automotive Suspension Systems Market Volume Units Forecast, by System Type 2020 & 2034
Table 5: Automotive Suspension Systems Market Revenue Billion Forecast, by Architecture 2020 & 2034
Table 6: Automotive Suspension Systems Market Volume Units Forecast, by Architecture 2020 & 2034
Table 7: Automotive Suspension Systems Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 8: Automotive Suspension Systems Market Volume Units Forecast, by Vehicle Type 2020 & 2034
Table 9: Automotive Suspension Systems Market Revenue Billion Forecast, by Propulsion 2020 & 2034
Table 10: Automotive Suspension Systems Market Volume Units Forecast, by Propulsion 2020 & 2034
Table 11: Automotive Suspension Systems Market Revenue Billion Forecast, by Sales Channel 2020 & 2034
Table 12: Automotive Suspension Systems Market Volume Units Forecast, by Sales Channel 2020 & 2034
Table 13: Automotive Suspension Systems Market Revenue Billion Forecast, by Region 2020 & 2034
Table 14: Automotive Suspension Systems Market Volume Units Forecast, by Region 2020 & 2034
Table 15: Asia-Pacific Automotive Suspension Systems Market Revenue Billion Forecast, by Component 2020 & 2034
Asia-Pacific Automotive Suspension Systems Market Volume Units Forecast, by Component 2020 & 2034
Frequently Asked Questions
1. How big is the Automotive Suspension Systems Market in 2026?
The market is valued at approximately 151.71 Billion in 2026, according to the most defensible published estimate. This figure covers OEM fitment and aftermarket replacement across passenger cars, commercial vehicles, and two-wheelers, and is projected to reach 204.46 Billion by 2031.
2. Why do estimates of the Automotive Suspension Systems Market differ so much?
The divergence is definitional, not analytical. Narrower estimates capture OEM-fitment hardware only, while broader figures include aftermarket service value and the full component set. Our analysis treats the higher figure as the addressable revenue pool and the lower as a conservative OEM-only proxy.
3. Which region dominates the Automotive Suspension Systems Market?
Asia-Pacific led with 48.96% of 2025 revenue, reflecting production concentration in China, Japan, India, and South Korea. The Middle East & Africa is the fastest-growing region at 7.65% CAGR, anchored by Gulf EV manufacturing investment.
4. What is the fastest-growing suspension system type?
Semi-active systems are forecast to grow at 8.74% CAGR through 2031, well above the market average. Electronic control units and sensors are the fastest-growing components at 9.22% CAGR, as suspension integrates with centralized vehicle domain controllers.
5. Who are the leading companies in the Automotive Suspension Systems Market?
ZF Friedrichshafen AG leads with over 9.5% market share. Continental AG, Astemo Ltd., Tenneco Inc., and Hyundai Mobis round out the top five, which collectively held 38.5% of the market in 2025, indicating moderate concentration.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the suspension value chain — Tier-1 system integrators, component specialists, spring and damper manufacturers, electronic module suppliers, and aftermarket distributors — with decision-maker designations including VP of Sourcing, Heads of Chassis R&D, Technical Directors, and Commercial Operations Leads.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chassis R&D & Technical Directors
40%
Procurement & Sourcing Leads
32%
Commercial Operations Leads
18%
Regulatory & Homologation Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Tier-1 System Integrators
40%
Component & Damper Specialists
30%
Electronic Module Suppliers
18%
Aftermarket Distributors
12%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade automotive parts trade flows, WTO tariff schedules, Eurostat and US ITC production statistics, corporate 10-K and annual investor filings, patent databases, and recognized standards bodies including UNECE and ISO. These sources anchor the market sizing and competitive mapping to observable, verifiable data.
Demand Modeling & Market Sizing Triangulation
Market sizing applies simultaneous top-down (macroeconomic and vehicle segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) triangulation, reconciled against published production and trade data. Regional splits are validated against cross-border trade flow analysis and regional vehicle assembly statistics.
 Automotive Suspension Systems Market