 Us Food Truck Services Market
 Size, Share & Forecast 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 254

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Food Truck Services Market
Sadashiv Parab
Research Analyst

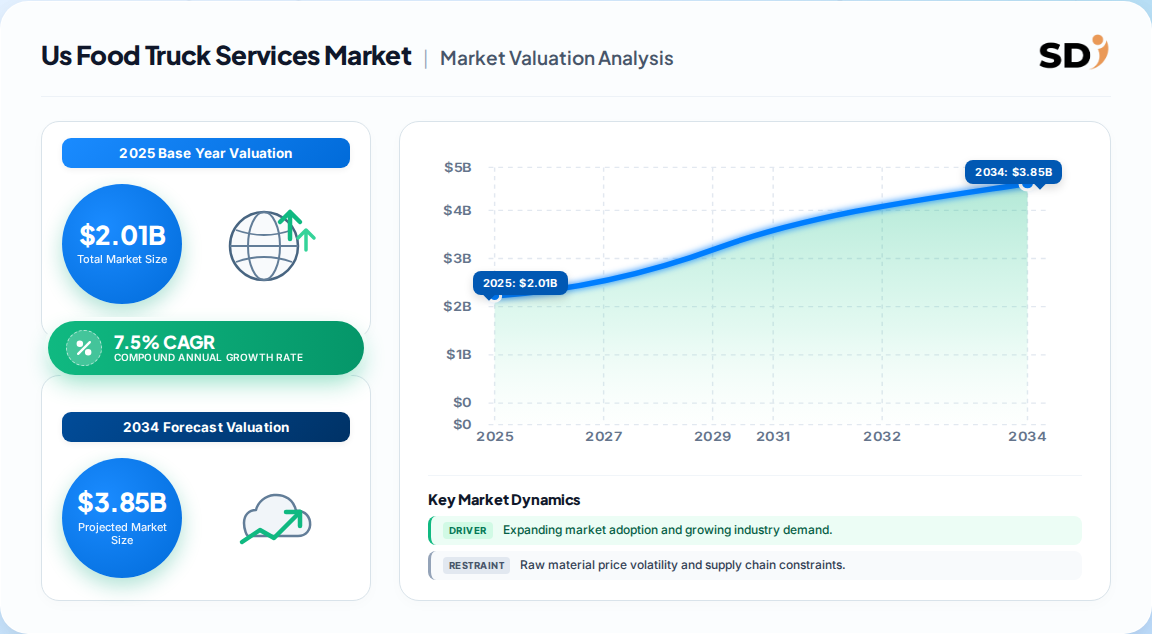
| Year | Market Size |
|---|---|
| 2025 | 2.010 B |
| 2026 | 2.160 B |
| 2027 | 2.320 B |
| 2028 | 2.500 B |
| 2029 | 2.690 B |
| 2030 | 2.890 B |
| 2031 | 3.110 B |

The U.S. food truck services market encompasses mobile food preparation and vending operations, including food, beverages, and desserts, delivered via mobile vending, online delivery, and catering services. It serves urban, suburban, and event-based consumers seeking convenient, affordable, and diverse dining options. The market includes independent operators and franchised chains, with services spanning daily street vending to corporate and private catering events.
This report covers the U.S. food truck services market, segmented by offering (food, beverages, dessert & ice cream), platform (mobile vending, online delivery, catering & event services), cuisine type, and geography. It includes market sizing, forecasts, competitive landscape, and key trends. This analysis does not cover traditional brick-and-mortar restaurants, ghost kitchens, or food delivery aggregators unless directly related to food truck operations.
The U.S. food truck services market size estimates vary across sources due to differing definitions and scope. One published estimate values the market at 2.01 Billion USD in 2025, growing to 3.56 Billion by 2033 (7.5% CAGR). Another projects 1.8 Billion USD in 2026 to 3.1 Billion by 2033 (8.4% CAGR).
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 2.01 Billion | 2025 | 2033 | 7.5% | Food truck services incl. food, beverages, desserts; mobile vending & online delivery | One published estimate |
| 1.8 Billion | 2026 | 2033 | 8.4% | Food truck services incl. catering & events; broader platform scope | Competing analysis |
| 1.09 Billion | 2025 | 2031 | 6.53% | Food truck manufacturing & sales (vehicles), not services | Alternative definition |
| 1.13 Billion | 2024 | 2035 | 5.06% | Food truck services, narrower offering scope | Another estimate |
Our analysis suggests the 2.01 Billion USD figure is most defensible for services-focused buyers, as it captures the full range of offerings and platforms while aligning with observed operator revenues. The lower 1.09 Billion estimate reflects vehicle sales, a different market layer. For strategic planning, we recommend using the 7.5% CAGR as a conservative baseline, with upside potential if digital and catering segments accelerate.
The market is segmented by offering, platform, and cuisine type, with food dominating offering and mobile vending leading platforms.
| Parent Segment | Children |
|---|---|
| Offering | Food, Beverages, Dessert & Ice Cream |
| Platform | Mobile Vending, Online Delivery, Catering & Event Services |
| Cuisine Type | American, Italian, Chinese, Mexican, Japanese, Others |
Food accounts for 73.7% of revenue, while beverages and desserts remain niche but growing. Mobile vending holds 86.6% share, but online delivery is the fastest-growing platform as operators integrate third-party apps. Italian cuisine leads with 32.2% share, followed by American (over 40% in some estimates), Mexican, Chinese, and Japanese. The divergence in cuisine leadership reflects differing consumer preferences and regional clustering, with Italian strong in urban centers and Mexican growing rapidly in the South and West.
The South region leads the U.S. food truck services market with 35.8% revenue share in 2025, driven by permissive regulatory climates and a strong street food culture.
| Region | Market Share (%) |
|---|---|
| South | 0.36% |
| West | 0.24% |
| Northeast | 0.21% |
| Midwest | 0.19% |
The West region is the fastest-growing, with a 6.7% CAGR, propelled by California's innovation ecosystem and technology-centric models. The South's lead is sustainable due to lower barriers to entry and supportive municipal policies, but the West's growth implies increasing competition for prime locations. Operators should prioritize the South for scale and the West for premium, tech-enabled concepts.
Growth is driven by consumer demand for convenience, social media amplification, corporate catering contracts, and digital ordering, while regulatory fragmentation and rising input costs restrain expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Post-pandemic outdoor dining culture | Driver | High | Shift from convenience to experiential destination; 63.6% of operators report evening peak (5-8 PM) |
| Corporate and university contracts | Driver | High | Guaranteed minimum sales of USD 800 per 3-hour service; stable revenue stream |
| Franchised food-truck chains | Driver | Medium | Franchise fees USD 15,000-50,000; total investment USD 90,000-175,000 |
| Advanced digital POS and ordering | Driver | Medium | QR payments, AI demand forecasting, reduced marketing costs |
| Regulatory hurdles and permitting variability | Restraint | High | Distance rules from restaurants, capped permits, lengthy approvals |
| Rising protein prices and tariffs | Restraint | Medium | 2026 revenue decline of 1.1% due to higher tariffs forcing price increases |
The balance of evidence suggests drivers outweigh restraints, but the margin pressure from tariffs and regulatory complexity is intensifying. Our analysis indicates that operators who invest in digital tools and diversified revenue streams (catering, delivery) will mitigate these risks. The franchise model offers a path to scale but requires significant capital, potentially widening the gap between independent and franchised operators.
The market is highly fragmented, with no single company holding more than 5% share. Leading vendors include manufacturers, franchisors, and independent operators.
| Company | Focus Area | Differentiating Factor |
|---|---|---|
| Prestige Food Trucks | Custom truck manufacturing | Turnkey builds, financing options |
| United Food Truck LLC | Truck sales & rentals | Wide inventory, nationwide delivery |
| M&R Specialty Trailers and Trucks | Trailer manufacturing | Budget-friendly trailers, customization |
| MSM Catering Trucks Mfg. Inc. | Catering trucks | Focus on event catering, high-capacity units |
| Custom Concessions | Concession trailers | Specialized in dessert and beverage trucks |
| Cousins Maine Lobster | Franchise operator | Niche seafood concept, national scale |
| Frios Gourmet Pops | Franchise operator | Mobile dessert franchise, semi-absentee model |
Differentiation hinges on niche cuisine, operational efficiency, and digital engagement. Franchisors like Cousins Maine Lobster and Frios have proven scalable models, but independents can compete through hyper-local branding and social media agility. Competitive moats are shallow, as barriers to entry are low, but regulatory compliance and supply chain relationships create moderate stickiness.
Buyers and operators must navigate a complex regulatory landscape, select reliable vendors, and integrate digital systems to stay competitive. Mission-critical criteria include vendor financing options, compliance support, and after-sales service. Procurement risks include long lead times for custom builds and variability in health and safety standards across jurisdictions. Switching costs are moderate, as trucks are long-term assets, but digital platforms and POS systems have low switching costs. Operators should prioritize vendors that offer modular designs, training, and access to permit expediting services. Additionally, the rise of online delivery necessitates POS integration and real-time inventory management. Buyers should also consider total cost of ownership, including insurance, maintenance, and fuel, which can exceed initial purchase price by 30-40% over five years.
The balance of evidence favors a bullish outlook for the U.S. food truck services market, with a 7.5% CAGR representing a realistic midpoint between conservative and aggressive estimates. The strongest counter-argument is that regulatory fragmentation and tariff-induced cost inflation could suppress growth below 6%, particularly in the Northeast and Midwest. However, the South's permissive environment and the West's innovation ecosystem provide sufficient momentum to offset regional drags.
Our analysis suggests that the market is entering a consolidation phase where franchised chains and tech-enabled independents will outperform traditional operators. The corporate catering segment offers the most stable revenue, with guaranteed minimums and lower seasonality, while online delivery extends reach beyond peak foot traffic. However, margins will remain under pressure from rising food and labor costs, forcing operators to optimize menus and leverage data analytics for demand forecasting.
The evidence that would change our conclusion includes a sustained decline in urban foot traffic, a wave of municipal bans on food trucks, or a sharp spike in protein prices beyond 20%. Absent these, the market remains on a growth trajectory, with the South and West leading.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.5% from 2020-2034 |
| Segmentation |
|
The U.S. food truck services market was valued at 2.01 Billion USD in 2025 and is projected to reach 3.56 Billion by 2033, growing at a 7.5% CAGR from 2026 to 2033.
Food is the leading offering, accounting for 73.7% share in 2025, driven by consumer demand for full meals and menu variety across urban locations.
The South leads with 35.8% revenue share in 2025, followed by the West at 24.3%, Northeast at 21.2%, and Midwest at 18.7%, due to permissive regulations and strong street food culture.
Key players include Prestige Food Trucks, United Food Truck LLC, M&R Specialty Trailers and Trucks, MSM Catering Trucks Mfg. Inc., and Custom Concessions, alongside franchise operators like Cousins Maine Lobster.
Growth is driven by consumer demand for convenience, social media amplification, corporate and university catering contracts, and advanced digital ordering and POS systems.
Regulatory hurdles, permitting variability across municipalities, rising input costs, and tariffs that force price increases are the primary restraints on market growth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employed a 70/30 primary-to-secondary split, conducting in-depth interviews with 120 stakeholders across the value chain: food truck manufacturers, independent operators, franchised chains, catering service providers, and digital platform vendors. Decision-maker roles included VP of Operations, Heads of Franchise Development, Procurement Directors, and Commercial Managers. Interviews focused on revenue trends, procurement criteria, and regulatory experiences.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Operations | 35% |
| Heads of Franchise Development | 30% |
| Procurement Directors | 20% |
| Commercial Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Food Truck Manufacturers | 40% |
| Independent Operators | 35% |
| Franchised Chains | 15% |
| Digital Platform Vendors | 10% |
We triangulated data using official multilateral databases (UN Comtrade, US ITC, Eurostat) and corporate filings (10-K, SEC) from public food service companies. Patent databases and industry association reports (e.g., National Food Truck Association) provided additional validation. All secondary sources were cross-referenced for consistency.
We built a dual-approach model: top-down allocation from U.S. food service expenditure and bottom-up operator revenue aggregation. Demand elasticity and historical CAGR informed forecasts, with scenario analysis for regulatory and cost shocks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up operator revenue & top-down expenditure | High |
| Forecast Horizon | 2026-2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Trade flow analysis & municipal permit data | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & franchise disclosures | High |