 Post Consumer Recycled Plastics Automotive Market
 2025
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 246

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Post Consumer Recycled Plastics Automotive Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 11.90 B |
| 2025 | 13.20 B |
| 2026 | 14.60 B |
| 2027 | 16.30 B |
| 2028 | 18.10 B |
| 2029 | 20.10 B |
| 2030 | 22.30 B |

The post consumer recycled plastics automotive market covers plastics recovered from end-of-use consumer products — bottles, packaging, textiles, electronics — then reprocessed into pellet, flake or compound form and sold into vehicle components. It spans polypropylene, polyethylene, PET and ABS grades used in interior, exterior and under-the-hood parts.
This analysis covers recycled polymer supply into light-vehicle and commercial-vehicle component manufacturing across polymer type, application and region, from 2024 base-year valuation through 2030. It includes mechanical and advanced recycling routes feeding automotive-grade compounds.
This analysis does not cover virgin polymer pricing, post-industrial scrap streams sold directly back into the same process, end-of-life vehicle dismantling economics, or recycled plastics destined for packaging, construction and consumer goods.
Estimates differ by roughly a factor of two on base-year value, which reflects genuinely different scope definitions rather than forecasting error. The table below isolates the definitions behind each figure.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 11.9 Billion | 2024 | 2030 | 11.1% | Automotive PCR plastics, polymer and application segmentation | One published estimate |
| 5.5 Billion | 2025 | 2033 | 12.5% | Automotive PCR plastics, narrower recycled-content boundary | A competing analysis |
| 15.4 Billion | 2021 | 2028 | 5.3% | All post-consumer recycled plastics, all end uses | Broader category benchmark |
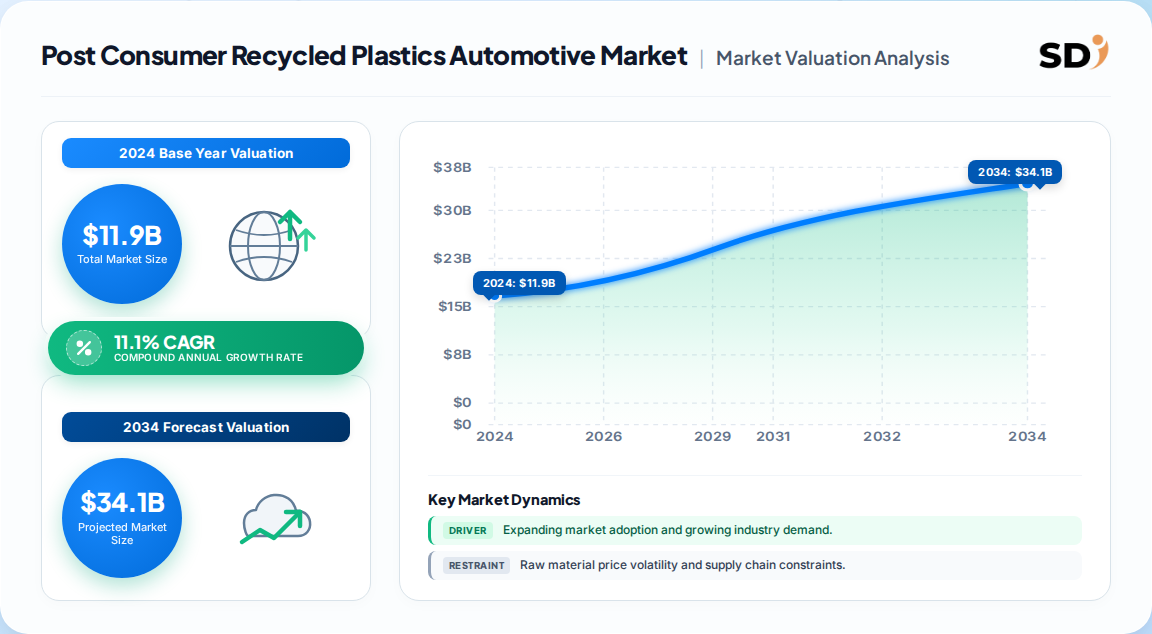
Our analysis suggests the 11.9 Billion figure is the most defensible automotive-specific anchor, because its trajectory (14.6 Billion in 2026 to 22.3 Billion by 2030) implies a substitution curve consistent with announced OEM recycled-content targets. The 5.5 Billion figure is internally coherent but appears to exclude compounded and additivated grades, which carry most of the value.
The 15.4 Billion benchmark is not comparable — it is an all-end-use number growing at 5.3%, and the automotive subset within it is growing faster. Buyers should treat the gap between 5.5 and 11.9 Billion as a scope question to resolve during diligence, not a dispute about growth.
Segmentation is driven by polymer performance economics: PP dominates on cost-to-property balance, while PET grows fastest from a small base because bottle feedstock is abundant and food-grade sorting infrastructure already exists.
| Parent segment | Children | 2024 share / growth |
|---|---|---|
| Polymer type | Polypropylene, Polyethylene, Acrylonitrile Butadiene Styrene, Polyethylene Terephthalate | PP 43.78%; PET 11.7% CAGR |
| Application | Interior components, Exterior components, Under-the-hood | Interior 60.92%; 11.9% CAGR |
| Recycled content grade | Mechanical recycled, chemically recycled | Qualifying grade dependent |
The interior concentration is the single most important structural fact in this market. Interior parts tolerate color and odor variability, face lower UV and impact certification burdens, and are replaced on shorter design cycles — all of which compress the qualification timeline that otherwise stalls recycled adoption.
Exterior components require UV stability and impact resistance, which pushes buyers toward recycled PP and PC blends plus additive packages. That is where margin and technical differentiation concentrate, and where supplier capability gaps are widest.
Asia Pacific leads with 44.36% of 2024 revenue, driven by vehicle assembly volume concentration and expanding regional recycling capacity. Regulation, however, is most binding in Europe and North America.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.44% |
| North America | 0.26% |
| Europe | 0.22% |
| South America | 0.04% |
| Middle East & Africa | 0.04% |
The divergence matters. Asia Pacific leads on volume but its growth is manufacturing-led; Europe and North America grow on mandate-led procurement, where the EU End-of-Life Vehicles Directive's 95% recyclability and recovery target converts recycled content from optional to contractual. Our analysis suggests Europe will post the highest value-per-tonne growth even without leading on absolute share, because compliance-driven buyers pay premiums for certified feedstock traceability.
North America's position rests on infrastructure quality as much as regulation — advanced sorting and processing investment has improved PCR consistency enough for demanding automotive specifications. The U.S. market is best understood as supply-enabled, while Europe is demand-mandated.
Regulation and OEM public commitments are the strongest demand signals, but the binding constraint is technical qualification capacity, not raw material availability.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Recycled-content mandates and ELV rules | Driver | Strong | Converts PCR content into compliance requirement |
| OEM sustainability pledges (Ford 20%, GM 50%) | Driver | Strong | Creates committed offtake and qualifies supply |
| Lightweighting and fuel-efficiency demand | Driver | Moderate | Favors plastic substitution for metal |
| Compounding and additive innovation | Driver | Moderate | Lifts recycled grades to OEM performance specs |
| Feedstock quality and availability variability | Restraint | Strong | Raises scrap rates and re-qualification cost |
| Virgin polymer price volatility | Restraint | Moderate | Erodes the PCR cost advantage when oil is cheap |
| Long automotive qualification cycles | Restraint | Strong | Delays revenue realization after design-in |
The balance favors continued expansion, but the growth curve is uneven by application. Cost-effectiveness is real yet conditional: PCR competes with virgin resin on price only when oil prices are elevated and sorting efficiency is high. That makes the automotive PCR case fundamentally regulatory and reputational rather than purely economic.
The competitive field splits into three groups: integrated polymer majors with recycled portfolios, dedicated recyclers moving up into compounding, and automotive tier-one suppliers offering recycled-content components directly.
| Player type | Position | Differentiation | Moat |
|---|---|---|---|
| Integrated polymer majors | Broad portfolio, OEM-specified | Virgin-plus-recycled supply continuity | Specification approval and scale |
| Dedicated mechanical recyclers | Volume feedstock | Sorting and washing capability | Collection network access |
| Advanced recycling specialists | Early-stage, high-value grades | Chemical route to food-grade quality | Process patents and certification |
| Tier-one automotive suppliers | Component-level integration | Design-for-recycling engineering | OEM program incumbency |
| Compounders and additive firms | Performance upgrading | Odor, color and impact modification | Formulation know-how |
Differentiation is migrating from feedstock access toward qualification and consistency. A recycler with abundant bales but no OEM-approved grade cannot monetize automotive demand. Conversely, compounders that can guarantee lot-to-lot mechanical properties command pricing power independent of virgin resin benchmarks.
Our analysis suggests the durable moat sits at the intersection of certified traceability and compounding capability. Players owning only one of those two assets face margin compression as feedstock and specification requirements tighten simultaneously.
Selection criteria are dominated by three things: certified recycled content with audit trail, lot-to-lot mechanical consistency, and evidence that the grade has completed OEM material approval. Price is a fourth-order consideration for interior safety-critical parts.
Procurement risk concentrates in feedstock volatility. Recycled PP supply is tied to packaging and durable goods collection rates, which are seasonally and regionally uneven. Buyers signing multi-year recycled-content commitments should secure feedstock optionality rather than single-sourcing, because a supply interruption now breaches a public sustainability target, not just a purchase order.
Switching costs are asymmetric and underappreciated. Qualifying a new recycled grade typically requires re-running dimensional, emissions and durability validation, which can consume a full design cycle. Once approved, buyers are reluctant to re-qualify, creating stickiness that favors incumbents but also traps buyers in underperforming supply relationships.
On compliance, recycled content claims increasingly require third-party certification to survive scrutiny. Operators should treat certification infrastructure — mass balance, chain of custody, and grade documentation — as a product feature, not overhead. Buyers who cannot document content origin face both regulatory exposure and reputational risk in consumer-facing vehicle marketing.
The balance of evidence favors sustained double-digit expansion, with the automotive PCR market compounding near 11% through 2030 on mandate-led demand and progressively improving material performance. The strongest counter-argument is that cheap virgin resin and slow qualification cycles could cap adoption well below forecast — and this deserves weight, because the cost advantage of PCR is genuinely conditional rather than structural. We nonetheless judge regulation the dominant variable, since compliance obligations persist regardless of oil price.
What the headline numbers obscure is that value is concentrating in qualification, not volume. Interior components dominate today because they are easy to qualify; the durable margin opportunity sits in exterior and under-the-hood grades where fewer suppliers can meet UV and impact specifications. Our analysis suggests the next competitive dislocation will occur among compounders who can certify performance, not among recyclers who can only supply tonnage.
Evidence that would change this conclusion: a sustained collapse in virgin polymer pricing combined with delayed enforcement of recycled-content mandates would compress the economics faster than regulation can compensate. While this overview establishes the strategic frame, precise sub-segment forecasting by polymer grade and OEM program requires the full report's program-level modeling.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.1% from 2020-2034 |
| Segmentation |
|
Approximately 11.1% CAGR from 2025 to 2030 under the most defensible automotive-specific estimate, taking the market from 14.6 Billion in 2026 to 22.3 Billion by 2030. Growth is regulation-led rather than purely price-led.
Polypropylene holds the largest share at 43.78% of 2024 revenue, used in door panels, dashboards, trim and under-the-hood parts. Recycled PET is the fastest-growing polymer at 11.7% CAGR, driven by seat fabrics and insulation.
Asia Pacific led with 44.36% of 2024 revenue, supported by vehicle assembly concentration and expanding recycling capacity. Europe and North America grow faster on a value basis because mandates make compliance purchasing mandatory.
Feedstock quality variability and long automotive qualification cycles. Recycled grades must clear OEM durability, emissions and appearance validation before design-in, which delays revenue realization even when material supply exists.
Interior components account for 60.92% of 2024 demand, including dashboards, door panels, consoles and trim. They tolerate minor color variation and face lower UV and impact certification burdens than exterior parts.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the recycled polymer value chain, including post-consumer feedstock collectors, mechanical and advanced recyclers, specialty compounders and additive suppliers, automotive tier-one component manufacturers, and global polymer distributors. Decision-maker designations interviewed included VP-level Sourcing and Procurement leads, Heads of Materials R&D, Technical Directors responsible for OEM material approval, and Commercial Operations Leads managing recycled-content portfolios.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Materials R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Sustainability & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Recyclers & Feedstock Processors | 40% |
| Compounders & Additive Suppliers | 30% |
| Tier-One Automotive Component Makers | 20% |
| Global Polymer Distributors | 10% |
Findings were benchmarked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K and equivalent disclosures), patent databases covering sorting, compatibilization and chemical recycling routes, and recognized technical standards and industry association publications on recycled content certification and automotive material specifications.
Sizing runs simultaneously top-down and bottom-up. The top-down track allocates macroeconomic vehicle production and material intensity by region and application. The bottom-up track models recycler and compounder capacity, grade-level pricing, and measured end-use consumption per vehicle platform. Divergence between tracks is resolved through segment-level reconciliation rather than averaging.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |