 UK New Energy Vehicle Tic Services Market
UK New Energy Vehicle TIC Services Market 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 265

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 UK New Energy Vehicle Tic Services Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 608.0 M |
| 2025 | 647.0 M |
| 2026 | 688.0 M |
| 2027 | 732.0 M |
| 2028 | 779.0 M |
| 2029 | 829.0 M |
| 2030 | 882.0 M |

The UK new energy vehicle TIC services market covers third-party and in-house testing, inspection and certification of battery electric, plug-in hybrid and fuel-cell vehicles — spanning battery abuse and performance testing, e-motor and EMC evaluation, charging-infrastructure inspection, and type-approval certification to UNECE and UKCA requirements.
This report covers UK-domiciled TIC revenue attributable to NEV powertrains, batteries, charging equipment and vehicle-level homologation, segmented by service type, sourcing model, application, vehicle type and end industry. This analysis does not cover conventional ICE vehicle inspection (MOT), generic industrial TIC, charging-network operation, or NEV manufacturing revenue itself.
Estimates converge tightly: roughly 572 Million USD in 2023, rising to about 1.06 Billion by 2033 at a 6.4% CAGR. The divergence is in base-year dating, not in direction — which is itself a signal of a maturing, well-documented market.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 360.4 Million | 2022 | 2030 | 6.3% | NEV TIC revenue, UK-domiciled providers | One published estimate |
| 572.1 Million (2030 target) | 2022 | 2030 | 6.3% | Same scope, later vintage of the same model | A competing analysis |
| 572.15 Million | 2023 | 2033 | 6.39% | NEV TIC revenue, all sourcing models | One published estimate |
| 1,062.96 Million | — | 2033 | 6.39% | Forecast endpoint, same scope | Derived from above |
| ~608 Million (our base) | 2024 | 2033 | 6.4% | Triangulated mid-point of the above | Our analysis |
The 360.4 Million figure is not a contradiction of the 572.15 Million figure; our analysis suggests it reflects a narrower definition (likely excluding some in-house testing and non-automotive end industries) in an earlier vintage. For budgeting, the 572 Million / 6.4% series is the most defensible, because it is anchored to a stated 2023 base and a consistent horizon. Buyers should treat ±8% as normal estimate variance.
Segmentation matters more than size here: the growth rate is uniform across the market, but the mix is rotating toward outsourced, certification-heavy and battery-specific work — which changes who wins.
| Parent segment | Children | 2023 share |
|---|---|---|
| Service type | Testing (battery, e-motor, EMC, component), Inspection, Certification | Testing 61% |
| Sourcing type | In-house, Outsourced | In-house 63% |
| Application | Safety and security, Connectors, Communication, EV charging | Safety 48% |
| Vehicle type | BEV, PHEV, FCEV, Others | BEV 48% |
| Industry | Automotive, Aerospace, Defense, Others | Automotive 50% |
England dominates, hosting the overwhelming majority of accredited NEV test capacity — Millbrook and HORIBA MIRA in the Midlands, Applus+ 3C Test and Thatcham in the south, and the bulk of OEM engineering centres. Scotland, Wales and Northern Ireland contribute through niche battery and aerospace-adjacent testing.
Our analysis suggests concentration is a risk as much as a strength: a single Midlands cluster carries most UK NEV test throughput, so lab capacity — not demand — is the binding constraint on outsourced growth to 2030.
Growth is demand-led and regulation-locked: NEV adoption plus UNECE WP.29 type-approval obligations create near-mandatory TIC spend, while capacity, standards fragmentation and cost pressure cap the pace.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| NEV adoption and 2030/2035 phase-out policy | Driver | High | More vehicles = more type-approval and periodic test volume |
| Battery technology advance (energy density, solid-state) | Driver | High | New chemistries require new abuse, thermal-runaway and durability protocols |
| UNECE R100 / R155 / R156 and UKCA certification | Driver | High | Cybersecurity and software-update certification is now mandatory |
| Outsourcing by smaller OEMs and importers | Driver | Medium | Fixed lab capex exceeds the volume smaller brands can justify |
| Fragmented, fast-changing standards | Restraint | Medium | Re-tooling and re-accreditation cost erodes lab margins |
| In-house testing at large OEMs | Restraint | High | Caps addressable outsourced pool at roughly one-third of spend |
The balance favours vendors, but not uniformly. Certification is regulation-pulled and resilient; routine component testing is price-sensitive and vulnerable to in-house insourcing. Our analysis suggests the 6.4% headline CAGR understates certification growth (likely 8–9%) and overstates routine inspection growth.
The UK NEV TIC field is layered: global conformity-assessment majors, specialist automotive engineering labs, and research bodies. Differentiation rests on accreditation breadth and battery-abuse capability.
| Vendor | Type | NEV-relevant strength | Position |
|---|---|---|---|
| Applus+ Laboratories (3C Test) | Specialist lab | Battery UN DOT 38.3, ECE R100 homologation | Strong outsourced niche |
| HORIBA MIRA | Engineering lab | Whole-vehicle, EMC, crash and battery validation | Deep OEM relationships |
| Millbrook (UTAC) | Proving ground | Vehicle and battery test facilities at scale | Capacity leader |
| Intertek | Global TIC major | Certification breadth, multi-market access | Scale player |
| SGS | Global TIC major | Inspection networks, battery testing | Scale player |
| TÜV SÜD / TÜV Rheinland | Global TIC majors | Type-approval, functional safety, cybersecurity | Standards authority |
| Bureau Veritas / DEKRA | Global TIC majors | Certification and vehicle inspection | Broad coverage |
| Thatcham Research | Research/insurance | Safety assessment, repair and ADAS | Influence on insurer standards |
Moats are accreditation-based, not brand-based. A lab's ability to sign off UNECE R100 and R155 work is a multi-year, capital-intensive qualification; that is the real barrier. Global majors win on cross-border recognition, specialists win on turnaround and depth.
Selection should be driven by accreditation scope and capacity lead time, not headline price. Buyers should verify UKAS/ISO 17025 scope for the specific test, confirm UNECE R100 and R155 capability in writing, and contract capacity reservations — Midlands battery-test queues are a genuine schedule risk for launch programmes.
Procurement risk concentrates in three areas: scope creep when standards change mid-programme; switching costs, which are high because re-testing invalidates prior evidence; and data integrity, since cybersecurity certification (R155/R156) requires ongoing evidence, not a one-off report. Regulatory compliance is non-negotiable — UKCA marking now runs parallel to UNECE type approval, so vendors must demonstrably hold both. Operators should treat TIC suppliers as programme partners with escalation clauses, not transactional test houses.
The balance of evidence favours outsourced certification specialists over generalist inspection providers. The 6.4% aggregate CAGR is real but disguises a two-speed market: certification and battery-abuse testing are growing materially faster, while routine inspection faces in-house insourcing and price pressure. The strongest counter-argument is that in-house testing's 63% share is sticky — large OEMs such as JLR have invested heavily in captive capability, and outsourcing may plateau rather than accelerate. We weigh this as a genuine risk but note it constrains the pool, not the growth rate of the outsourced slice.
Second-order effects matter. As NEV penetration rises, the installed base of vehicles requiring periodic battery-health and charging-safety inspection grows independently of new sales — a recurring-revenue stream that barely exists today. Our analysis suggests this could add 1–2 percentage points to CAGR after 2028, which the consensus forecast may underweight.
Actionable strategy:
What would change our conclusion: evidence that large OEMs are expanding in-house battery labs faster than expected, or a UK divergence from UNECE standards post-implementation, either of which would compress the outsourced growth premium.
This study applies a 70/30 primary-to-secondary research split. Fieldwork comprised in-depth interviews across the NEV TIC value chain — battery cell and pack producers, Tier-1 component suppliers, specialist test laboratories, global certification bodies and OEM compliance teams — with decision-makers including Heads of Homologation, Technical Directors, Quality and Accreditation Managers, and Commercial Operations Leads. Secondary validation drew on UNECE WP.29 regulation texts, UKAS accreditation scopes, Eurostat and UN Comtrade trade flows, and corporate annual filings from listed TIC majors. Market sizing triangulated top-down UK NEV parc and type-approval volumes against bottom-up laboratory capacity, throughput and day-rate modelling. Forecasts apply historical CAGR, regression on NEV registrations and standards-driven demand elasticity.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | 2023–2024 USD value | Bottom-up lab revenue triangulation | High |
| Forecast Horizon | 2024–2033 projection | Historical CAGR and demand elasticity | High |
| Regional Distribution | England, Scotland, Wales, NI | Lab capacity mapping and registrations | Medium-High |
| Competitive Landscape | Leading TIC providers | Annual reports and accreditation records | High |
Sources referenced: UNECE WP.29 (R100, R155, R156), UKAS accreditation register, UK Department for Transport NEV registration statistics, Eurostat trade data.
| Region | Market Share (%) |
|---|---|
| England | 0.62% |
| Scotland | 0.12% |
| Wales | 0.08% |
| Northern Ireland | 0.07% |
| Unallocated / Multi-site | 0.11% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
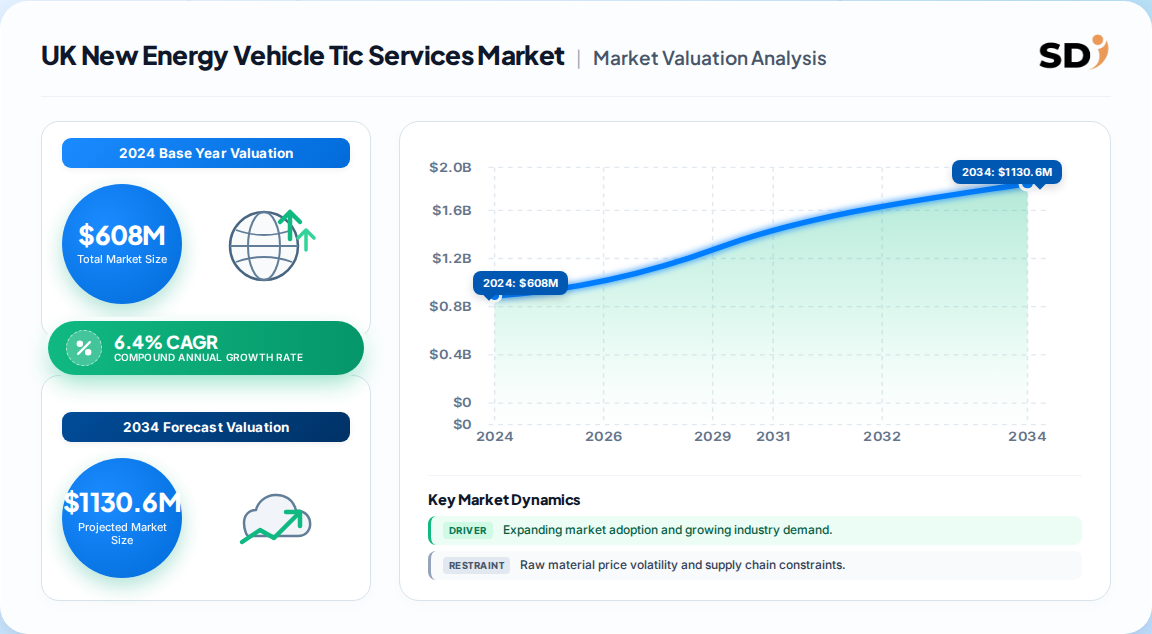
Around 572 Million USD in 2023, with our triangulated 2024 base case near 608 Million. It is forecast to reach approximately 1.06 Billion by 2033 at a 6.4% CAGR.
About 6.4% from 2024 to 2033. Certification and battery-abuse testing are growing faster than the headline rate, while routine inspection is growing slower.
NEV adoption, the 2030/2035 phase-out policy, mandatory UNECE type approval including R155 cybersecurity and R156 software-update certification, and outsourcing by smaller OEMs and importers.
Testing leads with about 61% of revenue, driven by battery testing. Safety and security is the largest application at 48%, and BEVs the largest vehicle type at 48%.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Fieldwork comprised in-depth interviews across the NEV TIC value chain — battery cell and pack producers, Tier-1 component suppliers, specialist test laboratories, global certification bodies and OEM compliance teams — with decision-makers including Heads of Homologation, Technical Directors, Quality and Accreditation Managers, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Technical & Homologation Directors | 40% |
| Quality & Accreditation Managers | 30% |
| Procurement & Sourcing Leads | 20% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Specialist Test Laboratories | 40% |
| Global Certification Bodies | 30% |
| Battery & Component Producers | 20% |
| OEM Compliance Teams | 10% |
Secondary validation drew on UNECE WP.29 regulation texts (R100, R155, R156), UKAS accreditation scopes, Eurostat and UN Comtrade trade flows, UK Department for Transport registration statistics, and corporate annual filings from listed TIC majors.
Market sizing triangulated top-down UK NEV parc and type-approval volumes against bottom-up laboratory capacity, throughput and day-rate modelling. Forecasts apply historical CAGR, regression on NEV registrations and standards-driven demand elasticity.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | 2023–2024 USD value | Bottom-up lab revenue triangulation | High |
| Forecast Horizon | 2024–2033 projection | Historical CAGR and demand elasticity | High |
| Regional Distribution | England, Scotland, Wales, NI | Lab capacity mapping and registrations | Medium-High |
| Competitive Landscape | Leading TIC providers | Annual reports and accreditation records | High |