Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Automotive Bushing Market Size, CAGR & Forecast to 2035
Automotive Bushing Market
Automotive Bushing Market Size, CAGR & Forecast to 2035
Automotive Bushing Market by Type (Suspension arm bushings, Engine mounts, Subframe bushings, Suspension mounts, Hydro bushings, Damper top mounts, Bump stops), by Vehicle Type (Passenger cars, Light commercial vehicles, Heavy commercial vehicles, Battery-electric and hybrid platforms), by Application (Suspension, Engine, Chassis, Transmission and driveline, Interior, Exhaust), by Material (Natural rubber, Synthetic rubber, Polyurethane, Composites and bio-based polymers), by Sales Channel (OEM, Aftermarket), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Spain, Czechia), by Asia Pacific (China, Japan, India, South Korea, Thailand, Indonesia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 279
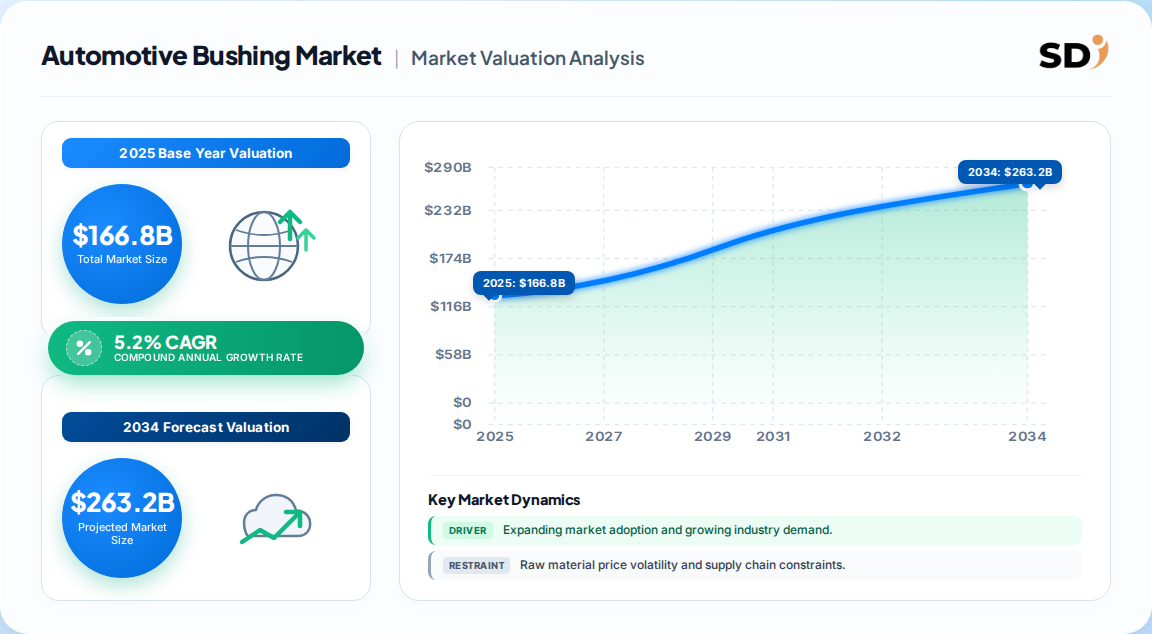
The global automotive bushing market was valued at 166.8 Billion in 2025, with a forecast of roughly 276.1 Billion by 2035 at a 5.2% CAGR (2026–2035), per one published estimate.
A competing analysis puts 2025 at 170.0 Billion rising to 251.3 Billion by 2033 at 5.0%, implying consensus size above 165 Billion but genuine forecast dispersion.
Suspension-related bushings dominate demand, capturing roughly 34–45% of application value depending on the segmentation definition used.
Asia-Pacific leads with roughly 46–60% revenue share, while North America is consistently flagged as the fastest-growing region.
Top five suppliers — Tenneco (DRiV), Continental, Vibracoustic, Sumitomo Riko and Cooper-Standard — hold about 32% combined share, confirming a fragmented, moderately concentrated field.
Electrification, NVH refinement and lightweight multi-material designs are the three forces reshaping product specifications through 2035.
Why this matters for decision-makers: Suppliers that cannot deliver EV-tuned, sensor-ready bushings will cede platform awards to rivals already co-developing with OEMs, compressing margins on commodity lines.
Automotive Bushing Market Size (In Billion)
250.0B
200.0B
150.0B
100.0B
50.0B
0
166.8 B
2025
174.2 B
2026
183.2 B
2027
192.8 B
2028
202.8 B
2029
213.3 B
2030
224.4 B
2031
Automotive Bushing Market Size (In Billion)
Year
Market Size
2025
166.8 B
2026
174.2 B
2027
183.2 B
2028
192.8 B
2029
202.8 B
2030
213.3 B
2031
224.4 B
What is the Automotive Bushing Market?
The automotive bushing market covers the design, manufacture and sale of elastomer, polyurethane and composite components that isolate vibration, absorb shock and locate suspension, engine, subframe and chassis assemblies in vehicles. Bushings protect metal interfaces, reduce noise and harshness (NVH) and preserve handling precision across passenger, commercial and electric vehicles.
Scope: what this report covers and excludes
This analysis covers original equipment and aftermarket bushings across passenger cars, light commercial vehicles, heavy commercial vehicles and battery-electric platforms, segmented by type, material, application and sales channel. Revenue is measured at manufacturer-level value in USD. This analysis does not cover tyres, springs, dampers, bearings, exhaust hangers or complete suspension module assembly, except where bushings are bundled into those systems.
How big is the market for Automotive Bushing Market?
Estimates cluster in a narrow band of roughly 165–180 Billion for 2025, but forecast endpoints diverge materially, which matters for capital planning. The table below compares the principal published figures and their underlying definitions.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
166.8 Billion to 276.1 Billion
2025
2035
5.2%
Full bushing value, all vehicle classes, OEM + aftermarket
One published estimate
170.0 Billion to 251.3 Billion
2025
2033
5.0%
Similar coverage, application-led segmentation
A competing analysis
172.5 Billion to 226.1 Billion
2025
2031
4.62%
Shorter horizon, value-based segmentation
A second competing analysis
Our analysis suggests the 5.2% CAGR is the most defensible midpoint: it sits between a conservative 4.6% and an aggressive 6.45% technology-focused view, and aligns with global light-vehicle production growth plus EV mix shift. The gap between the 276 Billion and 251 Billion endpoints reflects horizon length and inflation assumptions rather than demand disagreement.
How is the market segmented?
Segmentation follows five axes: bushing type, vehicle class, application system, material and sales channel. Type and material together determine price points and margin structure, while sales channel shapes revenue durability.
Parent segment
Children
By Type
Suspension arm bushings, engine mounts, subframe bushings, suspension mounts, hydro bushings, damper top mounts, bump stops
By Vehicle Type
Passenger cars, light commercial vehicles, heavy commercial vehicles, battery-electric and hybrid platforms
By Application
Suspension, engine, chassis, transmission and driveline, interior, exhaust
By Material
Natural rubber, synthetic rubber, polyurethane, composites and bio-based polymers
By Sales Channel
OEM, aftermarket
Suspension bushings anchor volume, but the fastest growth sits at the intersection of EV platforms and polyurethane or composite materials, where thermal load and weight targets exceed natural rubber capability.
Which region leads in Automotive Bushing Market?
Asia-Pacific leads the global market with an estimated 46–60% revenue share in 2025, driven by vehicle production concentration in China, India, Japan and South Korea. North America is consistently identified as the fastest-growing region on EV and premium NVH demand.
Automotive Bushing Market Regional Market Share
Loading chart...
Automotive Bushing Market Regional Market Share
Region
Market Share (%)
North America
0.21%
Europe
0.22%
Asia-Pacific
0.47%
Latin America
0.05%
Middle East & Africa
0.05%
Region
Share (2025)
Asia-Pacific
47%
Europe
22%
North America
21%
Latin America
5%
Middle East & Africa
5%
Asia-Pacific — China, Japan, India, South Korea, Thailand, Indonesia
Europe — Germany, France, UK, Italy, Spain, Czechia
North America — USA, Canada, Mexico
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa
The share dispersion across sources (46–60% for Asia-Pacific) reflects whether China's aftermarket and export volumes are counted domestically or attributed to destination markets. This divergence implies that suppliers planning capacity should model China both as a production base and as an export-origin distortion.
What is driving growth — and what is holding it back?
Growth is structurally supported by vehicle production recovery and electrification, offset by raw material volatility and OEM pricing pressure. The table weights each factor by evidence strength across the reference material.
Factor
Direction
Evidence strength
Mechanism
EV and hybrid volume growth
Driver
High
Bespoke bushings for battery mass, altered vibration signatures
Light-vehicle production rebound
Driver
High
Multiplier effect — each vehicle needs many bushings
NVH refinement for ride comfort
Driver
High
Engine noise masking removed in EVs exposes road noise
The balance favors drivers through 2030: electrification introduces net-new specification complexity rather than simple substitution, which supports value growth even where unit volumes plateau. Raw material volatility is the primary margin threat, not a demand threat.
Who are the leading vendors?
The competitive field is moderately concentrated, with the top five suppliers holding roughly 32% combined share and no single player commanding dominant position in bushings specifically.
Company
Typical position
Differentiator
Tenneco (DRiV)
Global Tier-1
Broad ride-control portfolio and OEM integration
Continental
Global Tier-1
Materials science depth and electronics adjacency
Vibracoustic
NVH specialist
Pure-play NVH and hydro-bushing engineering
Sumitomo Riko
Global Tier-1
Rubber compounding and Asia-Pacific footprint
Cooper-Standard
Global Tier-1
Sealing and fluid handling cross-sell
Differentiation rests on three moats: validated elastomer formulations, co-development relationships with OEM platform teams, and geographic proximity to vehicle assembly. Our analysis suggests the electronics adjacency of large Tier-1s is the most durable moat, because sensor-enabled bushings will increasingly require embedded capability that pure rubber specialists lack.
What do buyers and operators need to know?
Selection decisions hinge on validated durability data, not headline price. Buyers should demand platform-specific validation covering thermal cycling, salt-spray corrosion and fatigue life at target load spectra, because EV platforms shift both load and temperature profiles relative to ICE equivalents.
Procurement risk concentrates in three areas: raw material index exposure, single-source qualification costs and validation lead times. Switching suppliers typically requires re-validation cycles measured in months, which raises effective switching costs and argues for dual-sourcing on high-volume platforms.
Regulatory compliance is increasingly material. Recyclability and bio-based content mandates are tightening in Europe, and buyers should require material declarations and end-of-life data as standard tender documentation rather than as post-award requests.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a value-led growth story rather than a volume-led one. Unit demand tracks vehicle production at mid-single-digit rates, but specification intensity per vehicle is rising faster: EVs need more isolation points, better thermal resistance and, increasingly, embedded sensing. Suppliers positioned on that specification frontier should outgrow the headline CAGR.
The strongest counter-argument is that aftermarket economics erode OEM margins and that Chinese and regional suppliers will commoditize standard rubber bushings faster than premium specifications can offset. That view is credible for damper bushings and bump stops, but weaker for hydro bushings and EV-specific suspension mounts where validation barriers remain high. Our analysis suggests the market splits into a commoditized base and a defensible premium tier.
Actionable strategy:
Investors should prioritize NVH specialists and Tier-1s with EV-specific hydro and sensor-enabled bushing pipelines over commodity rubber producers.
Operators should build dual-sourcing on high-volume standard bushings while securing single-source co-development on EV platform awards.
Buyers should demand material declarations and recyclability data now, ahead of European mandates, to avoid late-stage re-validation costs.
The conclusion would change if EV adoption decelerated sharply and OEMs reverted to standardized bushing architectures, collapsing the premium tier toward commodity pricing.
Automotive Bushing Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Automotive Bushing Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.2% from 2020-2034
Segmentation
By Type
Suspension arm bushings
Engine mounts
Subframe bushings
Suspension mounts
Hydro bushings
Damper top mounts
Bump stops
By Vehicle Type
Passenger cars
Light commercial vehicles
Heavy commercial vehicles
Battery-electric and hybrid platforms
By Application
Suspension
Engine
Chassis
Transmission and driveline
Interior
Exhaust
By Material
Natural rubber
Synthetic rubber
Polyurethane
Composites and bio-based polymers
By Sales Channel
OEM
Aftermarket
By Geography
North America
USA
Canada
Mexico
Europe
Germany
France
UK
Italy
Spain
Czechia
Asia Pacific
China
Japan
India
South Korea
Thailand
Indonesia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Suspension arm bushings
5.1.2. Engine mounts
5.1.3. Subframe bushings
5.1.4. Suspension mounts
5.1.5. Hydro bushings
5.1.6. Damper top mounts
5.1.7. Bump stops
5.2. Market Analysis, Insights and Forecast - by Vehicle Type
5.2.1. Passenger cars
5.2.2. Light commercial vehicles
5.2.3. Heavy commercial vehicles
5.2.4. Battery-electric and hybrid platforms
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Suspension
5.3.2. Engine
5.3.3. Chassis
5.3.4. Transmission and driveline
5.3.5. Interior
5.3.6. Exhaust
5.4. Market Analysis, Insights and Forecast - by Material
5.4.1. Natural rubber
5.4.2. Synthetic rubber
5.4.3. Polyurethane
5.4.4. Composites and bio-based polymers
5.5. Market Analysis, Insights and Forecast - by Sales Channel
5.5.1. OEM
5.5.2. Aftermarket
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Suspension arm bushings
6.1.2. Engine mounts
6.1.3. Subframe bushings
6.1.4. Suspension mounts
6.1.5. Hydro bushings
6.1.6. Damper top mounts
6.1.7. Bump stops
6.2. Market Analysis, Insights and Forecast - by Vehicle Type
6.2.1. Passenger cars
6.2.2. Light commercial vehicles
6.2.3. Heavy commercial vehicles
6.2.4. Battery-electric and hybrid platforms
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Suspension
6.3.2. Engine
6.3.3. Chassis
6.3.4. Transmission and driveline
6.3.5. Interior
6.3.6. Exhaust
6.4. Market Analysis, Insights and Forecast - by Material
6.4.1. Natural rubber
6.4.2. Synthetic rubber
6.4.3. Polyurethane
6.4.4. Composites and bio-based polymers
6.5. Market Analysis, Insights and Forecast - by Sales Channel
6.5.1. OEM
6.5.2. Aftermarket
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Suspension arm bushings
7.1.2. Engine mounts
7.1.3. Subframe bushings
7.1.4. Suspension mounts
7.1.5. Hydro bushings
7.1.6. Damper top mounts
7.1.7. Bump stops
7.2. Market Analysis, Insights and Forecast - by Vehicle Type
7.2.1. Passenger cars
7.2.2. Light commercial vehicles
7.2.3. Heavy commercial vehicles
7.2.4. Battery-electric and hybrid platforms
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Suspension
7.3.2. Engine
7.3.3. Chassis
7.3.4. Transmission and driveline
7.3.5. Interior
7.3.6. Exhaust
7.4. Market Analysis, Insights and Forecast - by Material
7.4.1. Natural rubber
7.4.2. Synthetic rubber
7.4.3. Polyurethane
7.4.4. Composites and bio-based polymers
7.5. Market Analysis, Insights and Forecast - by Sales Channel
7.5.1. OEM
7.5.2. Aftermarket
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Suspension arm bushings
8.1.2. Engine mounts
8.1.3. Subframe bushings
8.1.4. Suspension mounts
8.1.5. Hydro bushings
8.1.6. Damper top mounts
8.1.7. Bump stops
8.2. Market Analysis, Insights and Forecast - by Vehicle Type
8.2.1. Passenger cars
8.2.2. Light commercial vehicles
8.2.3. Heavy commercial vehicles
8.2.4. Battery-electric and hybrid platforms
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Suspension
8.3.2. Engine
8.3.3. Chassis
8.3.4. Transmission and driveline
8.3.5. Interior
8.3.6. Exhaust
8.4. Market Analysis, Insights and Forecast - by Material
8.4.1. Natural rubber
8.4.2. Synthetic rubber
8.4.3. Polyurethane
8.4.4. Composites and bio-based polymers
8.5. Market Analysis, Insights and Forecast - by Sales Channel
8.5.1. OEM
8.5.2. Aftermarket
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Suspension arm bushings
9.1.2. Engine mounts
9.1.3. Subframe bushings
9.1.4. Suspension mounts
9.1.5. Hydro bushings
9.1.6. Damper top mounts
9.1.7. Bump stops
9.2. Market Analysis, Insights and Forecast - by Vehicle Type
9.2.1. Passenger cars
9.2.2. Light commercial vehicles
9.2.3. Heavy commercial vehicles
9.2.4. Battery-electric and hybrid platforms
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Suspension
9.3.2. Engine
9.3.3. Chassis
9.3.4. Transmission and driveline
9.3.5. Interior
9.3.6. Exhaust
9.4. Market Analysis, Insights and Forecast - by Material
9.4.1. Natural rubber
9.4.2. Synthetic rubber
9.4.3. Polyurethane
9.4.4. Composites and bio-based polymers
9.5. Market Analysis, Insights and Forecast - by Sales Channel
9.5.1. OEM
9.5.2. Aftermarket
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Suspension arm bushings
10.1.2. Engine mounts
10.1.3. Subframe bushings
10.1.4. Suspension mounts
10.1.5. Hydro bushings
10.1.6. Damper top mounts
10.1.7. Bump stops
10.2. Market Analysis, Insights and Forecast - by Vehicle Type
10.2.1. Passenger cars
10.2.2. Light commercial vehicles
10.2.3. Heavy commercial vehicles
10.2.4. Battery-electric and hybrid platforms
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Suspension
10.3.2. Engine
10.3.3. Chassis
10.3.4. Transmission and driveline
10.3.5. Interior
10.3.6. Exhaust
10.4. Market Analysis, Insights and Forecast - by Material
10.4.1. Natural rubber
10.4.2. Synthetic rubber
10.4.3. Polyurethane
10.4.4. Composites and bio-based polymers
10.5. Market Analysis, Insights and Forecast - by Sales Channel
10.5.1. OEM
10.5.2. Aftermarket
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Automotive Bushing Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Automotive Bushing Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Automotive Bushing Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Automotive Bushing Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 5: North America Automotive Bushing Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 6: North America Automotive Bushing Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Automotive Bushing Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Automotive Bushing Market Revenue (Billion), by Material 2026 & 2034
Figure 9: North America Automotive Bushing Market Revenue Share (%), by Material 2026 & 2034
Figure 10: North America Automotive Bushing Market Revenue (Billion), by Sales Channel 2026 & 2034
Figure 11: North America Automotive Bushing Market Revenue Share (%), by Sales Channel 2026 & 2034
Figure 12: North America Automotive Bushing Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Automotive Bushing Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Automotive Bushing Market Revenue (Billion), by Type 2026 & 2034
Figure 15: Europe Automotive Bushing Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Automotive Bushing Market Revenue (Billion), by Vehicle Type 2026 & 2034
List of Tables
Table 1: Automotive Bushing Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Automotive Bushing Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 16: Europe Automotive Bushing Market Revenue Billion Forecast, by Type 2020 & 2034
Frequently Asked Questions
1. How big is the automotive bushing market?
The automotive bushing market was valued at approximately 166.8 Billion in 2025, with forecasts reaching roughly 276.1 Billion by 2035. Competing analyses place 2025 between 166 and 178 Billion, so the consensus size is comfortably above 165 Billion.
2. What is the automotive bushing market growth rate?
Most published estimates place the long-term CAGR between 4.6% and 5.2%, with 5.2% the most commonly cited figure for 2026 to 2035. Technology-focused analyses reach 6.45%, reflecting faster EV-driven specification upgrading.
3. Which region dominates the automotive bushing market?
Asia-Pacific leads with roughly 46 to 60% of revenue, driven by vehicle production in China, India, Japan and South Korea. North America is consistently identified as the fastest-growing region, supported by EV manufacturing investment.
4. What are the main types of automotive bushings?
The main types are suspension arm bushings, engine mounts, subframe bushings, suspension mounts, hydro bushings and damper top mounts. Suspension-related bushings account for the largest single share of application value.
5. Why is electrification important for bushing demand?
Electric vehicles remove engine noise masking, exposing road and drivetrain noise, and add battery mass that raises suspension loads. This demands bespoke bushings with better thermal resistance, vibration isolation and lightweight construction.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split. Primary interviews were conducted across the automotive bushing value chain, including elastomer and polyurethane material suppliers, specialized bushing producers, contract manufacturing specialists, and global aftermarket distributors. Structured in-depth interviews were held with VP-level sourcing executives, heads of materials R&D, technical directors responsible for NVH validation, and commercial operations leads at Tier-1 suppliers. These engagements captured platform-level demand intent and supplier qualification realities that published filings do not reveal.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Leads
40%
R&D & Technical Directors
35%
Commercial Operations Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Elastomer & Polyurethane Material Suppliers
40%
Specialized Bushing Producers
35%
Global Aftermarket Distributors
25%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade and WTO trade flows for rubber and polyurethane components, US ITC and Eurostat automotive parts data, corporate annual filings and investor presentations, patent filings covering hydro-bushing and sensor-integration designs, and technical standards published by ISO and SAE International covering elastomer durability and fatigue testing. All secondary figures are cross-checked against at least two independent public sources before inclusion.
Demand Modeling & Market Sizing Triangulation
We run top-down and bottom-up models simultaneously. The top-down model allocates macroeconomic vehicle production by class and region to bushing value per vehicle. The bottom-up model aggregates manufacturer capacity, realized pricing and end-use consumption by application. Divergence beyond a defined threshold triggers re-interrogation of the underlying assumptions.
 Automotive Bushing Market