 Usa Motor Vehicle Sensors Market
USA Motor Vehicle Sensors Market: 2026 Outlook & Forecast
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 278

Sadashiv Parab

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Usa Motor Vehicle Sensors Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 5.730 B |
| 2026 | 6.130 B |
| 2027 | 6.570 B |
| 2028 | 7.030 B |
| 2029 | 7.530 B |
| 2030 | 8.060 B |
| 2031 | 8.620 B |

The USA motor vehicle sensors market comprises the design, manufacture, and supply of sensing devices—temperature, pressure, radar, MEMS, and NOx sensors—integrated into passenger and commercial vehicles. These sensors enable engine management, safety systems, emissions control, and advanced driver assistance systems (ADAS), forming the sensory backbone of modern vehicles.
This analysis covers the U.S. market for motor vehicle sensors by sensor type, application, vehicle type, propulsion, sales channel, and technology platform. It includes original equipment and aftermarket demand. This analysis does not cover adjacent markets such as automotive semiconductors, infotainment systems, or standalone telematics hardware.
Estimates for the U.S. motor vehicle sensors market vary significantly due to differences in scope and definition. The table below compares leading published estimates to clarify the divergence.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 6.13 billion | 2026 | 2031 | 7.05% | U.S. automotive sensors, all sensor types and applications | One published analysis (Mordor Intelligence) |
| USD 3.88 billion | 2023 | 2030 | 6.4% | U.S. motor vehicle sensors, temperature/pressure/NOx focus | One competing analysis (Grand View Research) |
| USD 5.73 billion | 2025 | 2031 | 7.05% | U.S. automotive sensors, same scope as 6.13B estimate | Derived from same source |
This divergence implies definitional differences matter: the USD 3.88 billion estimate (2023) likely excludes radar and MEMS-based perception sensors, while the USD 6.13 billion (2026) figure captures the full ADAS and electrification-driven sensor stack. Our analysis suggests the broader definition is more defensible for procurement planning, as it aligns with FMVSS 127 AEB mandates and EV battery-management requirements that are reshaping sensor content per vehicle.
The market is segmented by sensor type, application, vehicle type, propulsion, sales channel, and technology. The table below outlines the primary non-geographic segments.
| Parent Segment | Children |
|---|---|
| By Sensor Type | Temperature Sensors, Pressure Sensors, Radar Sensors, NOx Sensors, Position Sensors, Oxygen Sensors, MEMS Inertial Sensors |
| By Application | Engine & Drivetrain, Safety & Security (ADAS), Emission Control, Battery Management, Body & Comfort |
| By Vehicle Type | Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Motorcycles |
| By Propulsion | Internal Combustion Engine (ICE), Battery EV, Hybrid/PHEV, Fuel Cell |
| By Sales Channel | OEM, Aftermarket |
| By Technology Platform | MEMS, CMOS, Infrared, Ultrasonic, Lidar |
The South leads the U.S. motor vehicle sensors market, accounting for approximately 31% of national demand in 2025, driven by vehicle assembly plants in Texas, Tennessee, and South Carolina. The Midwest follows closely, anchored by Michigan's traditional automotive manufacturing base.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.22% |
| South | 0.31% |
| Midwest | 0.26% |
| West | 0.21% |
| Region | Share |
|---|---|
| South | 31% |
| Midwest | 26% |
| Northeast | 22% |
| West | 21% |
Nested Geography Tree:
This regional distribution reflects the concentration of OEM assembly and Tier 1 supplier facilities. The South's lead is amplified by EV and battery plant investments in the "Battery Belt" corridor, which is expected to increase its share by 2031.
Regulatory mandates and electrification are the primary growth engines, while supply-chain constraints and cost pressures temper the trajectory. The table below summarizes key factors.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| EV adoption pushes sensor content per vehicle | Positive | High | +2.4% CAGR impact; BEVs require 2-3x more sensors than ICE |
| Federal TPMS, ESC & NCAP upgrades | Positive | High | +1.8% CAGR impact; mandates increase sensor content |
| Software-defined vehicle architectures | Positive | Medium | +1.5% CAGR impact; centralized compute requires redundant sensing |
| CHIPS Act incentivizes on-shore MEMS fabs | Positive | Medium | +1.2% CAGR impact; reduces lead times and supply risk |
| Cost & price-erosion squeeze Tier-1 margins | Negative | High | -1.2% CAGR impact; commoditization of mature sensor lines |
| Silicon-supply water-stress | Negative | Medium | -0.9% CAGR impact; Arizona fab water constraints |
| Sensor-level cyber-security requirements | Negative | Medium | -0.8% CAGR impact; adds validation cost and complexity |
The balance favors growth, with regulatory mandates (FMVSS 127 AEB) and EV adoption providing non-deferrable demand. However, margin pressure on mature ICE sensors is real: suppliers must shift mix toward ADAS and EV-specific sensors to sustain profitability. The CHIPS Act's USD 39 billion in grants is a structural positive, reducing supply-chain risk for MEMS devices.
The U.S. market is moderately concentrated, with the top five players holding over 56% of global share. The table below compares leading vendors.
| Company | Headquarters | Key Strengths | Notable Developments |
|---|---|---|---|
| Robert Bosch GmbH | Germany | Engine management, safety systems, ADAS | Hydrogen fuel cell technology; >30% global share |
| Continental AG | Germany | ADAS, sensor fusion, braking systems | Strategic collaborations in autonomous driving |
| DENSO Corporation | Japan | Powertrain sensors, thermal management | Expansion of EV battery sensor portfolio |
| Sensata Technologies | USA | Pressure and temperature sensors | Acquisition-driven portfolio expansion |
| Valeo SA | France | LiDAR, ultrasonic, camera systems | Partnerships for autonomous vehicle sensing |
Differentiation rests on automotive-grade manufacturing qualifications (ISO 26262, IATF 16949) and system-integration capability. Tier 1 suppliers with established OEM design-ins enjoy high switching costs, as sensor qualification cycles span 3-5 years. Our analysis suggests the competitive moat is deepest for suppliers that can deliver multi-modal fusion (camera + radar + LiDAR) with software validation support.
Buyers of motor vehicle sensors face a complex procurement landscape shaped by regulatory deadlines, technology transitions, and supply-chain volatility. The FMVSS 127 automatic emergency braking rule establishes a compliance deadline that makes ADAS sensor packages non-deferrable, shifting sensor procurement from feature differentiation to regulatory necessity.
Switching costs are substantial: sensor qualification for safety-critical applications requires ISO 26262 functional safety certification, ISO 21434 cybersecurity validation, and extensive durability testing. This creates a 3-5 year design-in cycle that locks OEMs into supplier relationships, limiting flexibility but ensuring reliability.
Procurement risks include MEMS foundry capacity constraints (automotive radar sensor shipments are expected to exceed 170 million globally in 2025) and silicon-supply water-stress in Arizona, which could affect domestic fab output. Buyers should prioritize suppliers with dual-sourcing arrangements and on-shore MEMS capacity to mitigate these risks.
The balance of evidence favors a bullish outlook for the U.S. motor vehicle sensors market, with the 7.05% CAGR trajectory well-supported by regulatory mandates, EV adoption, and software-defined vehicle architectures. However, the market is not uniform: mature ICE sensor lines face margin compression, while ADAS and EV-specific sensors command premium pricing and growth.
The strongest counter-argument is that semiconductor supply-chain volatility could cap growth below forecast, particularly if MEMS foundry capacity fails to keep pace with demand for radar and inertial sensors. Additionally, cost pressures on Tier 1 suppliers could accelerate consolidation, reducing the viable supplier pool and potentially slowing innovation.
Our analysis suggests the most defensible position is that the U.S. market will grow at or slightly above the 7.05% CAGR, driven by non-deferrable regulatory demand (FMVSS 127) and the EV transition. The risk is skewed to the downside only if a major supply-chain disruption occurs in MEMS or radar sensor production.
Actionable Strategy:
Evidence that would change our conclusion: A sustained decline in U.S. vehicle production below 14 million units annually, or a major MEMS foundry disruption lasting more than 12 months, would materially alter the growth trajectory and warrant a downward revision.
This study employs a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including sensor manufacturers, Tier 1 automotive suppliers, OEM procurement teams, and aftermarket distributors. Decision-makers interviewed included VP-level sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads.
We validated findings against official trade databases (US ITC, UN Comtrade), corporate annual filings (10-K, SEC), patent databases, and technical standards from SAE International and ISO. Regulatory benchmarks included NHTSA rulemaking and EPA emissions standards.
We employed simultaneous top-down (macroeconomic and vehicle production allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling to triangulate market size and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025/2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | State-level share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
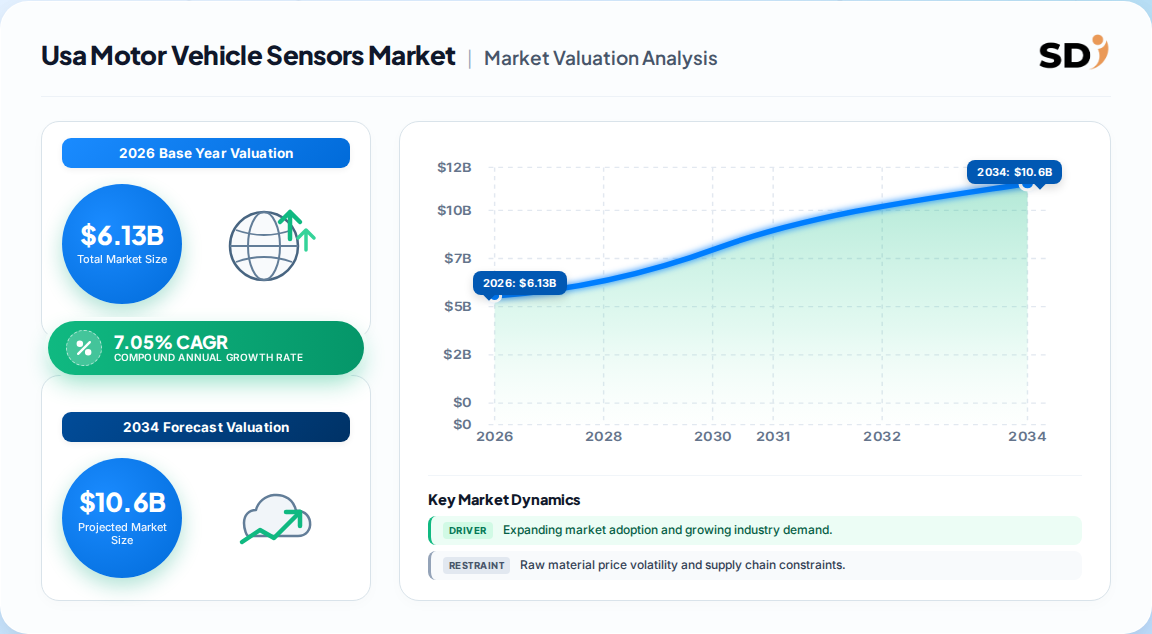
| Growth Rate | CAGR of 7.05% from 2020-2034 |
| Segmentation |
|
The U.S. motor vehicle sensors market is valued at USD 6.13 billion in 2026 and is forecast to reach USD 8.62 billion by 2031, growing at a 7.05% CAGR.
Pressure sensors led with 29.02% market share in 2025. Radar sensors are the fastest-growing category at an 8.02% CAGR, driven by ADAS adoption.
Key drivers include EV adoption (2-3x more sensors per vehicle), FMVSS 127 AEB mandates, software-defined vehicle architectures, and CHIPS Act incentives for on-shore MEMS fabs.
Leading vendors include Robert Bosch GmbH, Continental AG, DENSO Corporation, Sensata Technologies, and Valeo SA, with the top five holding over 56% of the global market.
The South leads with approximately 31% of national demand, driven by vehicle assembly plants in Texas, Tennessee, and South Carolina, followed by the Midwest at 26%.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including sensor manufacturers, Tier 1 automotive suppliers, OEM procurement teams, and aftermarket distributors. Decision-makers interviewed included VP-level sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 35% |
| Heads of R&D | 30% |
| Technical Directors | 25% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Sensor Manufacturers | 40% |
| Tier 1 Automotive Suppliers | 30% |
| OEM Procurement Teams | 20% |
| Aftermarket Distributors | 10% |
We validated findings against official trade databases (US ITC, UN Comtrade), corporate annual filings (10-K, SEC), patent databases, and technical standards from SAE International and ISO. Regulatory benchmarks included NHTSA rulemaking and EPA emissions standards.
We employed simultaneous top-down (macroeconomic and vehicle production allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling to triangulate market size and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025/2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | State-level share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |