Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Automotive Leaf Spring Market: 2026 Growth Outlook
Automotive Leaf Spring Market
Automotive Leaf Spring Market: 2026 Growth Outlook
Automotive Leaf Spring Market by Type (Semi-Elliptical, Elliptical, Parabolic, Other Types), by Material (Steel, Composite), by Vehicle Type (Passenger Cars, Light Commercial Vehicle, Medium and Heavy Commercial Vehicle), by Sales Channel (OEM, Aftermarket), by Asia-Pacific (China, India, Japan, South Korea, ASEAN), by Europe (Germany, France, UK, Italy, Spain), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 242
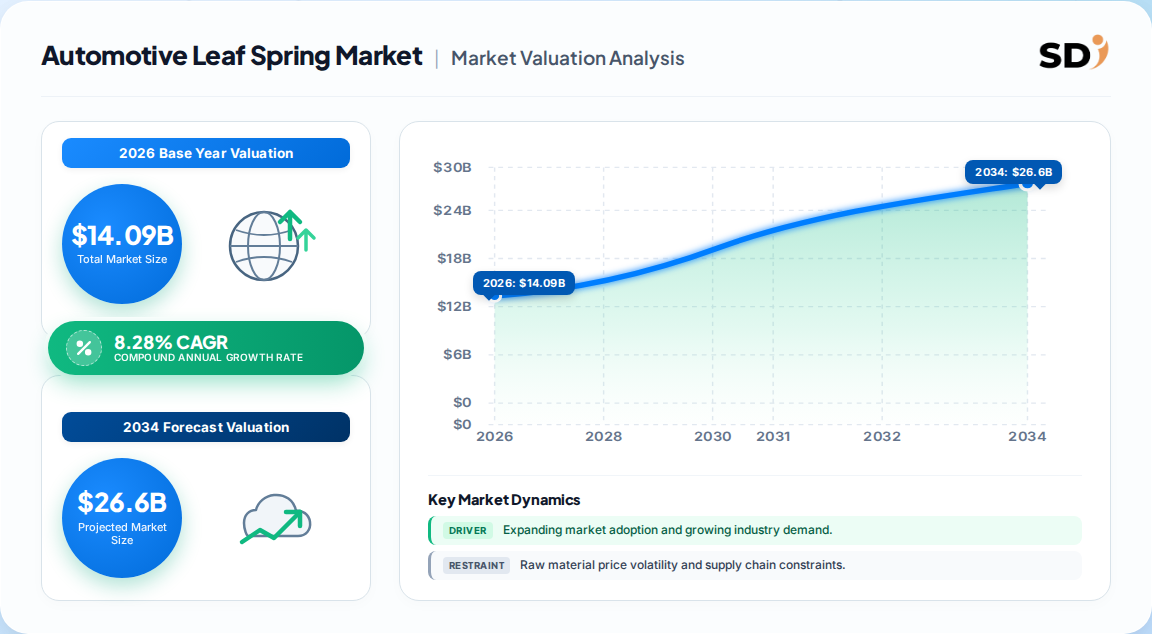
14.09 Billion USD represents the 2026 global automotive leaf spring market size, per one published estimate, with 2025 base at 13.01 Billion USD.
Forecast growth to 20.96 Billion USD by 2031 implies a fixed 8.28% CAGR across the six-year window.
Semi-elliptical configurations led with 63.58% revenue share in 2025; parabolic designs are the fastest-growing type at 7.05% CAGR.
Steel commanded 74.68% of 2025 material share, but composite leaf springs are advancing at 8.19% CAGR on lightweighting mandates.
Asia-Pacific held 44.83% of 2025 revenue and remains both the largest and fastest-growing region in the global market.
Leading vendors include Hendrickson USA, Jamna Auto, Rassini, Sogefi, and NHK Spring; the top five collectively hold a medium-concentration footprint.
Why this matters for decision-makers: Vendors tied exclusively to multi-leaf steel architectures face margin compression by 2029 as parabolic and composite specs dominate new CV and electric-van platforms.
Automotive Leaf Spring Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
14.09 B
2026
15.26 B
2027
16.52 B
2028
17.89 B
2029
19.37 B
2030
20.96 B
2031
Automotive Leaf Spring Market Size (In Billion)
Year
Market Size
2026
14.09 B
2027
15.26 B
2028
16.52 B
2029
17.89 B
2030
19.37 B
2031
20.96 B
What is the Automotive Leaf Spring Market?
The automotive leaf spring market covers the design, manufacture, and distribution of arc-shaped steel or composite spring assemblies used in vehicle suspension systems. These components bear axle loads, distribute weight uniformly, and provide ride stability — primarily in light, medium, and heavy commercial vehicles and select passenger platforms.
Scope: what this report covers and excludes
This analysis addresses global demand for semi-elliptical, elliptical, parabolic, and other leaf spring types across steel and composite materials, segmented by vehicle type (passenger cars, LCVs, MHCVs) and sales channel (OEM and aftermarket). This analysis does not cover air suspension bellows, coil springs, torsion bars, integrated damper assemblies, or non-automotive spring applications.
How big is the market for Automotive Leaf Spring Market?
The market is sized between 5.3 and 14.09 Billion USD depending on definitional treatment of value versus volume and component bundling — a 2.7x spread that demands careful reconciliation before any procurement or investment decision.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
14.09 Billion USD
2026
2031 (20.96 Billion)
8.28%
Full leaf spring assemblies, global, value terms
One published estimate (Mordor-aligned)
13.92 Billion USD
2025
2035 (28.83 Billion)
7.55%
Leaf spring assemblies, global, all vehicle types
A competing analysis
6.38 Billion USD
2025
2034 (10.39 Billion)
5.57%
Multi-leaf and mono-leaf, narrower scope
A competing analysis
5.3 Billion USD
2025
2034 (7.7 Billion)
4.2%
Leaf springs only, ex-bundled hardware
A competing analysis
Our analysis suggests the 14.09 Billion USD (2026) figure is most defensible for procurement benchmarking because its scope explicitly includes parabolic and hybrid composite assemblies — the segments responsible for the fastest demand growth. The lower 5.3 Billion USD estimate likely excludes bundled shackle, bushing, and U-bolt hardware, understating true category spend.
How is the market segmented?
Segmentation follows four non-geographic axes: spring type, material, vehicle class, and sales channel — with material and vehicle class being the most commercially decisive for vendor positioning.
Parent Segment
Children
2025 Share / Growth
By Type
Semi-Elliptical, Elliptical, Parabolic, Other
Semi-elliptical 63.58%; parabolic 7.05% CAGR
By Material
Steel, Composite
Steel 74.68%; composite 8.19% CAGR
By Vehicle Type
Passenger Cars, LCV, MHCV
LCV 42.12% revenue; 9.32% CAGR
By Sales Channel
OEM, Aftermarket
OEM 69.74%; aftermarket 6.41% CAGR
Which region leads in Automotive Leaf Spring Market?
Asia-Pacific leads with 44.83% of 2025 global revenue, supported by China and India's combined commercial vehicle output exceeding 12 million units annually and a 6.18% regional CAGR through 2031.
Automotive Leaf Spring Market Regional Market Share
Loading chart...
Automotive Leaf Spring Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.44%
Europe
0.24%
North America
0.22%
South America
0.06%
Middle East & Africa
0.04%
Asia-Pacific (44.83%)
China
India
Japan
South Korea
ASEAN
Europe (24%)
Germany
France
UK
Italy
Spain
North America (22%)
United States
Canada
Mexico
South America (6%)
Brazil
Argentina
Middle East & Africa (4%)
Saudi Arabia
UAE
South Africa
Region
2025 Share
Growth Signal
Asia-Pacific
44.83%
6.18% CAGR, largest and fastest
Europe
24%
Euro VII-driven lightweighting
North America
22%
Class 8 replacement cycles, reshoring
South America
6%
Fleet modernization, price-sensitive
Middle East & Africa
4%
Infrastructure-led, low base
What is driving growth — and what is holding it back?
Commercial vehicle production growth (+2.1% CAGR impact) and lightweighting mandates (+1.8%) are the dominant demand engines, while air and multi-link suspension substitution (-2.1%) represents the single largest structural headwind to the category.
Factor
Direction
Evidence Strength
Mechanism
Global CV production growth
Driver
High
+2.1% CAGR; electric MHDV registrations +80% in 2024
Lightweight suspension demand
Driver
High
+1.8% CAGR; composite saves up to 92% mass vs. steel
Cost advantage vs. air suspension
Driver
Medium
+1.4% CAGR; 35–50% lower upfront cost
Last-mile EV van retrofits
Driver
Medium
+1.2% CAGR; parabolic progressive-rate packages
Air / multi-link substitution
Restraint
High
-2.1% CAGR; premium pickups, SUVs, EU GSR push
Spring-steel price volatility
Restraint
Medium
-1.0% CAGR; alloy cost pass-through lag
Structural sagging / fatigue
Restraint
Medium
-1.3% CAGR; high-usage CV duty cycles
The balance of evidence favors net positive growth through 2031, with drivers out-weighing restraints by roughly 4.5 percentage points in aggregate CAGR impact. Our analysis suggests the substitution threat is concentrated in premium segments, leaving the mass-market CV and LCV aftermarket structurally intact for the forecast horizon.
Who are the leading vendors?
The competitive landscape is medium-concentration, with NHK Spring, Rassini, Sogefi, Hendrickson, and Jamna Auto anchoring OEM supply relationships across multiple regional platforms.
Company
HQ / Region
Position & Differentiator
NHK Spring Co., Ltd.
Japan / APAC
Broadest portfolio, ~19.4% automotive spring share (cross-category)
Rassini
Mexico / Americas
Dominant in North American parabolic leaf and light-vehicle programs
Sogefi S.p.A.
Italy / Europe
Steel and composite capability, Euro VII platform exposure
Hendrickson USA LLC
USA / North America
Heavy-duty CV and trailer specialization, reshoring beneficiary
Jamna Auto Industries
India / APAC
Cost leadership in India's multi-leaf and parabolic CV segments
Olgun Celik
Turkey / EMEA
Regional CV spring specialist, high-growth export footprint
Differentiation rests on three moats: integrated metallurgy and heat-treatment capability, multi-year OEM platform nomination cycles (typically 3–5 years), and validated corrosion-fatigue performance under SAE J2800. Our analysis suggests composite scale-up capability will be the decisive moat by 2029; vendors without HP-RTM or glass-fiber overwrap capacity risk exclusion from next-generation EV van and electric CV programs.
What do buyers and operators need to know?
Procurement decisions in this category are governed by total cost of ownership, fatigue validation, and platform nomination timing — not unit price alone. Buyers specifying steel multi-leaf for heavy CV applications should demand SAE J2800 corrosion-fatigue certificates and establish steel-index-linked pricing clauses to absorb alloy volatility. For electric-van and light-CV programs, parabolic and hybrid steel-composite assemblies deliver the progressive rate and mass reduction that battery-pack payload math requires, but at a 40–70% cost premium per assembly. Switching costs are non-trivial: platform re-validation typically takes 9–15 months, and aftermarket retrofit programs carry separate homologation risk. Our analysis suggests buyers should segment their supply base into a steel commodity tier and a composite engineering tier to avoid overpaying on one or under-specifying on the other.
Regulatory exposure is material in Europe, where Euro VII and General Safety Regulation mandates are already reshaping chassis weight targets. North American buyers face EPA Phase 3 GHG-driven uncertainty in the medium-duty segment but benefit from a stable aftermarket replacement cycle supported by a 12.8-year average US light-duty fleet age.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a constructive 2026–2031 outlook, with an 8.28% CAGR as the most defensible single-point forecast and the 5.57% estimate as an overly narrow-scope floor. The strongest counter-argument is that premium air-suspension substitution and EU active-safety regulation could accelerate share loss faster than the composite upside recovers — particularly in Europe's premium pickup and SUV niches. However, the commercial vehicle core, where air suspension remains cost-prohibitive in emerging markets, insulates roughly 70% of category revenue.
Our analysis suggests the market is in a structural upgrade cycle, not a volume-expansion cycle. The value pool is migrating from multi-leaf steel toward parabolic and hybrid composite assemblies, and vendors that fail to re-tool their HP-RTM and glass-fiber capability by 2028 will lose nomination access to the fastest-growing LCV and electric-van platforms even as aggregate demand rises.
Actionable Strategy:
Investors: Prioritize vendors with demonstrated composite scale-up (HP-RTM lines, glass-fiber overwrap capability) over pure steel volume players; composite CAGR at 8.19% outpaces steel's baseline by roughly 2x.
Operators: Lock 3–5 year parabolic steel supply contracts in Asia-Pacific now, before Euro VII-driven European demand tightens global parabolic capacity from 2028.
Buyers: Build a dual-tier supply base — steel commodity vendors for aftermarket and CV replacement, engineering-tier composite vendors for OEM EV platforms — to hedge both cost and technical risk.
What evidence would change this conclusion: a faster-than-anticipated collapse in steel alloy prices (OECD projects 6.7% overcapacity by 2027) combined with accelerated EU active-suspension mandates could compress the parabolic premium faster than composite scale-up recovers, pulling the market toward the 5.57% CAGR floor. Conversely, a tripling of MHDV electric truck registrations by 2030, as the IEA projects, would push demand toward the 8.28% ceiling.
Automotive Leaf Spring Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Automotive Leaf Spring Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.28% from 2020-2034
Segmentation
By Type
Semi-Elliptical
Elliptical
Parabolic
Other Types
By Material
Steel
Composite
By Vehicle Type
Passenger Cars
Light Commercial Vehicle
Medium and Heavy Commercial Vehicle
By Sales Channel
OEM
Aftermarket
By Geography
Asia-Pacific
China
India
Japan
South Korea
ASEAN
Europe
Germany
France
UK
Italy
Spain
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Semi-Elliptical
5.1.2. Elliptical
5.1.3. Parabolic
5.1.4. Other Types
5.2. Market Analysis, Insights and Forecast - by Material
5.2.1. Steel
5.2.2. Composite
5.3. Market Analysis, Insights and Forecast - by Vehicle Type
5.3.1. Passenger Cars
5.3.2. Light Commercial Vehicle
5.3.3. Medium and Heavy Commercial Vehicle
5.4. Market Analysis, Insights and Forecast - by Sales Channel
5.4.1. OEM
5.4.2. Aftermarket
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. Asia-Pacific
5.5.2. Europe
5.5.3. North America
5.5.4. South America
5.5.5. Middle East & Africa
6. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Semi-Elliptical
6.1.2. Elliptical
6.1.3. Parabolic
6.1.4. Other Types
6.2. Market Analysis, Insights and Forecast - by Material
6.2.1. Steel
6.2.2. Composite
6.3. Market Analysis, Insights and Forecast - by Vehicle Type
6.3.1. Passenger Cars
6.3.2. Light Commercial Vehicle
6.3.3. Medium and Heavy Commercial Vehicle
6.4. Market Analysis, Insights and Forecast - by Sales Channel
6.4.1. OEM
6.4.2. Aftermarket
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Semi-Elliptical
7.1.2. Elliptical
7.1.3. Parabolic
7.1.4. Other Types
7.2. Market Analysis, Insights and Forecast - by Material
7.2.1. Steel
7.2.2. Composite
7.3. Market Analysis, Insights and Forecast - by Vehicle Type
7.3.1. Passenger Cars
7.3.2. Light Commercial Vehicle
7.3.3. Medium and Heavy Commercial Vehicle
7.4. Market Analysis, Insights and Forecast - by Sales Channel
7.4.1. OEM
7.4.2. Aftermarket
8. North America Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Semi-Elliptical
8.1.2. Elliptical
8.1.3. Parabolic
8.1.4. Other Types
8.2. Market Analysis, Insights and Forecast - by Material
8.2.1. Steel
8.2.2. Composite
8.3. Market Analysis, Insights and Forecast - by Vehicle Type
8.3.1. Passenger Cars
8.3.2. Light Commercial Vehicle
8.3.3. Medium and Heavy Commercial Vehicle
8.4. Market Analysis, Insights and Forecast - by Sales Channel
8.4.1. OEM
8.4.2. Aftermarket
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Semi-Elliptical
9.1.2. Elliptical
9.1.3. Parabolic
9.1.4. Other Types
9.2. Market Analysis, Insights and Forecast - by Material
9.2.1. Steel
9.2.2. Composite
9.3. Market Analysis, Insights and Forecast - by Vehicle Type
9.3.1. Passenger Cars
9.3.2. Light Commercial Vehicle
9.3.3. Medium and Heavy Commercial Vehicle
9.4. Market Analysis, Insights and Forecast - by Sales Channel
9.4.1. OEM
9.4.2. Aftermarket
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Semi-Elliptical
10.1.2. Elliptical
10.1.3. Parabolic
10.1.4. Other Types
10.2. Market Analysis, Insights and Forecast - by Material
10.2.1. Steel
10.2.2. Composite
10.3. Market Analysis, Insights and Forecast - by Vehicle Type
10.3.1. Passenger Cars
10.3.2. Light Commercial Vehicle
10.3.3. Medium and Heavy Commercial Vehicle
10.4. Market Analysis, Insights and Forecast - by Sales Channel
10.4.1. OEM
10.4.2. Aftermarket
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Automotive Leaf Spring Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Automotive Leaf Spring Market Volume Breakdown (Units, %) by Region 2026 & 2034
Figure 3: Asia-Pacific Automotive Leaf Spring Market Revenue (Billion), by Type 2026 & 2034
Figure 4: Asia-Pacific Automotive Leaf Spring Market Volume (Units), by Type 2026 & 2034
Figure 5: Asia-Pacific Automotive Leaf Spring Market Revenue Share (%), by Type 2026 & 2034
Figure 6: Asia-Pacific Automotive Leaf Spring Market Volume Share (%), by Type 2026 & 2034
Figure 7: Asia-Pacific Automotive Leaf Spring Market Revenue (Billion), by Material 2026 & 2034
Figure 8: Asia-Pacific Automotive Leaf Spring Market Volume (Units), by Material 2026 & 2034
Figure 9: Asia-Pacific Automotive Leaf Spring Market Revenue Share (%), by Material 2026 & 2034
Figure 10: Asia-Pacific Automotive Leaf Spring Market Volume Share (%), by Material 2026 & 2034
Figure 11: Asia-Pacific Automotive Leaf Spring Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 12: Asia-Pacific Automotive Leaf Spring Market Volume (Units), by Vehicle Type 2026 & 2034
Figure 13: Asia-Pacific Automotive Leaf Spring Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 14: Asia-Pacific Automotive Leaf Spring Market Volume Share (%), by Vehicle Type 2026 & 2034
Figure 15: Asia-Pacific Automotive Leaf Spring Market Revenue (Billion), by Sales Channel 2026 & 2034
Figure 16: Asia-Pacific Automotive Leaf Spring Market Volume (Units), by Sales Channel 2026 & 2034
List of Tables
Table 1: Automotive Leaf Spring Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Automotive Leaf Spring Market Volume Units Forecast, by Type 2020 & 2034
Table 3: Automotive Leaf Spring Market Revenue Billion Forecast, by Material 2020 & 2034
Table 4: Automotive Leaf Spring Market Volume Units Forecast, by Material 2020 & 2034
Table 5: Automotive Leaf Spring Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 6: Automotive Leaf Spring Market Volume Units Forecast, by Vehicle Type 2020 & 2034
Table 7: Automotive Leaf Spring Market Revenue Billion Forecast, by Sales Channel 2020 & 2034
Table 8: Automotive Leaf Spring Market Volume Units Forecast, by Sales Channel 2020 & 2034
Table 9: Automotive Leaf Spring Market Revenue Billion Forecast, by Region 2020 & 2034
Table 10: Automotive Leaf Spring Market Volume Units Forecast, by Region 2020 & 2034
Table 11: Asia-Pacific Automotive Leaf Spring Market Revenue Billion Forecast, by Type 2020 & 2034
Table 12: Asia-Pacific Automotive Leaf Spring Market Volume Units Forecast, by Type 2020 & 2034
Table 13: Asia-Pacific Automotive Leaf Spring Market Revenue Billion Forecast, by Material 2020 & 2034
Table 14: Asia-Pacific Automotive Leaf Spring Market Volume Units Forecast, by Material 2020 & 2034
Table 15: Asia-Pacific Automotive Leaf Spring Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 16: Asia-Pacific Automotive Leaf Spring Market Volume Units Forecast, by Vehicle Type 2020 & 2034
Frequently Asked Questions
1. What is the automotive leaf spring market size in 2026?
The global automotive leaf spring market was estimated at 14.09 Billion USD in 2026, rising from 13.01 Billion USD in 2025, with a projected trajectory to 20.96 Billion USD by 2031 at an 8.28% CAGR.
2. Which region dominates the automotive leaf spring market?
Asia-Pacific leads with approximately 44.83% of 2025 global revenue, supported by India and China's combined commercial vehicle output exceeding 12 million units annually and a 6.18% regional CAGR through 2031.
3. Why are composite leaf springs growing faster than steel?
Composite leaf springs deliver 50–92% mass reduction versus steel and are advancing at an 8.19% CAGR as OEMs offset heavy EV battery packs. Steel still commands 74.68% share on cost and supply-chain maturity.
4. Which vehicle type leads leaf spring demand?
Light commercial vehicles led with 42.12% revenue share in 2025 and are expanding at a 9.32% CAGR through 2031, driven by e-commerce last-mile delivery fleet expansion and 4–5 year replacement cycles.
5. What is the biggest risk to automotive leaf spring demand?
Air and multi-link suspension substitution in premium segments carries a -2.1% CAGR impact, the largest single restraint. However, leaf springs retain a 35–50% upfront cost advantage that protects mass-market CV demand.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. Primary fieldwork comprised in-depth interviews with stakeholders across the leaf spring value chain: spring-steel wire and composite raw material suppliers, specialized leaf spring producers, contract heat-treatment and coating formulators, and global Tier-1 distributors. Interviewees were designated as VP of Sourcing, Heads of Suspension R&D, Technical Directors of Platform Engineering, and Commercial Operations Leads across OEM, Tier-1, and aftermarket channels.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Heads of Suspension R&D
35%
VP of Sourcing & Procurement
30%
Technical Directors, Platform Engineering
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Spring Steel & Composite Raw Material Suppliers
40%
Specialized Leaf Spring Producers
35%
Contract Heat-Treatment & Coating Formulators
15%
Global Tier-1 & Aftermarket Distributors
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on UN Comtrade and US ITC trade-flow datasets for spring-steel and composite leaf assemblies, Eurostat vehicle production statistics, corporate 10-K and SEC filings from listed spring manufacturers, patent databases covering composite leaf and HP-RTM processes, and recognized technical standards including SAE J2800 suspension-spring corrosion-fatigue protocols.
Demand Modeling & Market Sizing Triangulation
Market sizing applied simultaneous Top-Down allocation from macroeconomic vehicle production and segment share data, and Bottom-Up modeling from manufacturer capacity, product pricing, and end-use consumption by vehicle class. The two models were reconciled to a single base-year value with variance bands of ±4%.
 Automotive Leaf Spring Market