 Car Dvr Market
Car DVR Market Outlook: Size, Growth & Forecast 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 273

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Car Dvr Market
Sadashiv Parab
Research Analyst

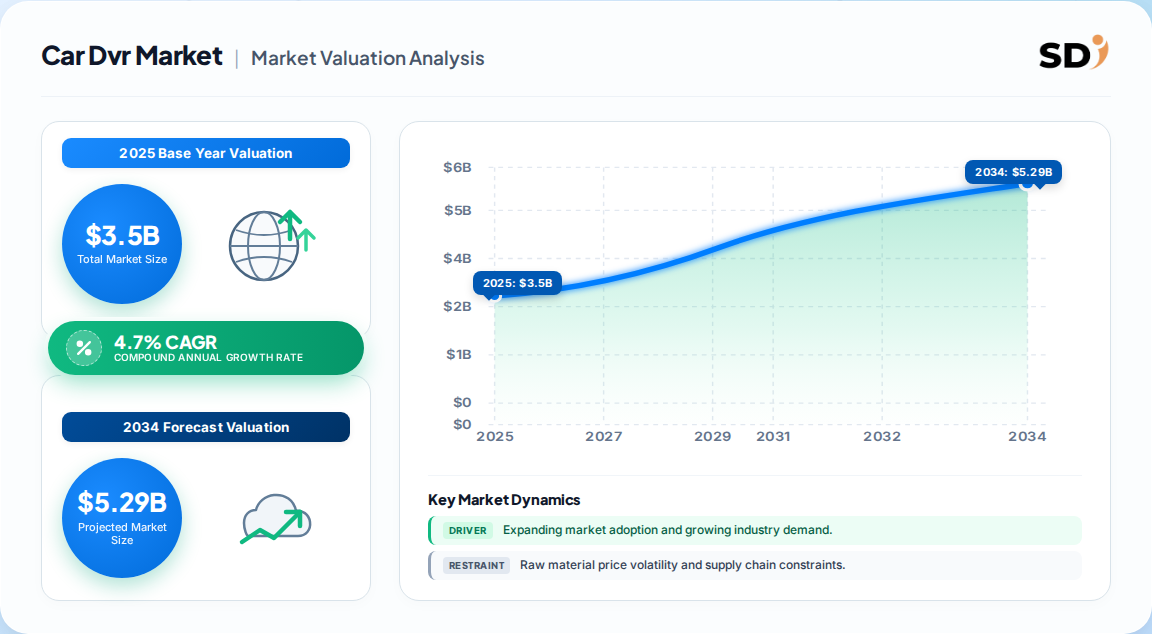
| Year | Market Size |
|---|---|
| 2025 | 3.500 B |
| 2026 | 3.660 B |
| 2027 | 3.830 B |
| 2028 | 4.010 B |
| 2029 | 4.200 B |
| 2030 | 4.400 B |
| 2031 | 4.610 B |

The Car DVR market covers vehicle-mounted digital video recorders — dash cameras — that continuously capture forward, rearward or interior footage to onboard storage for insurance evidence, collision documentation and driver-safety purposes. It spans single-, dual- and multi-channel configurations sold through aftermarket retail and OEM-fitted programmes for passenger and commercial vehicles.
This analysis covers windshield-mounted and OEM-integrated dash cameras across single-channel, dual-channel and multi-channel configurations, segmented by price tier, video quality, technology level, vehicle type and sales channel across seven global regions. Forecasts run 2026–2033.
This analysis does not cover full fleet telematics platforms sold as managed service contracts, body-worn law-enforcement cameras, fixed CCTV or parking-surveillance infrastructure, and driver-monitoring systems whose primary function is fatigue detection rather than external incident recording.
Published estimates converge on a base of roughly USD 3.3–3.5 billion in 2025, but headline figures diverge sharply because definitions differ — some include OEM-fitted ADAS-integrated camera modules, others count only standalone aftermarket hardware.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 3.3 Billion | 2025 | 2033 | 4.7% | Standalone car DVR hardware, product + application split | One published industry analysis |
| USD 3.5 Billion | 2025 | 2030 | 5.11% | Car DVR incl. ADAS-advanced and OEM-installed tiers | A competing analysis |
| USD 1.96 Billion | 2025 | 2036 | 5.2% | Consumer-centric dash camera hardware, aftermarket-weighted | A third published estimate |
| USD 7.1 Billion | 2025 | 2033 | 6.3% | Broad automotive video-recording scope incl. adjacent systems | A broader-scope estimate |
Our assessment favours the USD 3.3–3.5 billion band as the most defensible base. It aligns with plausible unit economics — roughly 20–25 million units at a blended ASP near USD 150 — whereas the USD 7.1 billion figure appears to fold in adjacent telematics and ADAS camera modules that the narrower definition excludes. The USD 1.96 billion reading is credible only as a pure aftermarket-consumer measure. This divergence implies buyers should anchor procurement and investment cases to unit volumes and ASPs rather than headline totals.
Segmentation matters because growth rates diverge by tier: entry-level single-channel units are commoditising, while dual-channel, 4K and AI-enabled connected devices carry premium pricing power.
| Parent segment | Children |
|---|---|
| Product type | Single-channel front, Rear-view-only, Dual-channel front + rear, Multi-channel |
| Vehicle type | Passenger cars, Light commercial vehicles, Heavy commercial vehicles |
| Sales channel | Aftermarket, OEM-installed |
| Technology level | Basic DVR, Advanced DVR with ADAS, Smart connected DVR |
| Video quality | SD/HD (≤720p), Full HD 1080p, 4K and above |
| Price range | Budget, Mid-priced, Premium |
Single-channel front units held roughly 42–70% of revenue depending on scope definition, while dual-channel grows fastest at ~5.3% CAGR. OEM-installed channels expand near 7.2% CAGR from a smaller base, and 4K-and-above devices grow at ~6.3% CAGR. Our analysis suggests the mid-priced tier is the volume battleground: it captures buyers who have outgrown entry-level quality concerns without committing to premium dual-channel pricing.
Europe and North America jointly lead, together commanding roughly 60% of global revenue, with Europe slightly ahead on a revenue-share basis and North America strong on insurance-incentive-driven adoption.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.3% |
| Asia-Pacific | 0.28% |
| Latin America | 0.05% |
| Middle East & Africa | 0.05% |
Europe's lead is regulation-anchored: eCall mandates and layered camera-based safety requirements have normalised in-vehicle recording at OEM level. Asia Pacific is the fastest-growing region at ~5.7% CAGR, with China combining large domestic demand and an export manufacturing base that supplies global brands — a dual demand-and-supply dynamic few regions replicate. This implies that supply-chain sourcing decisions and demand-growth decisions increasingly point to the same geography.
Insurance premium discounts and tightening ADAS/eCall regulation are the two strongest demand accelerants, each contributing roughly 0.8–1.2 percentage points to CAGR, while privacy regulation and commoditisation act as drags.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Insurance premium discounts (10–15%) | Driver | Strong | Shortens payback; converts awareness into purchase |
| EU/Korea/Japan ADAS & eCall mandates | Driver | Strong | Makes recording compulsory in regulated vehicle classes |
| Fleet video-telematics adoption | Driver | Strong | Scales B2B volumes; 75% of managers report accident reductions |
| AI driver-monitoring analytics | Driver | Moderate | Shifts value from recording to predictive intervention |
| Falling CMOS & storage costs | Driver | Moderate | Lowers BOM, expands addressable price tiers |
| Fragmented privacy law (GDPR, Brazil) | Restraint | Moderate | Caps always-on recording in some jurisdictions |
| Smartphone-app substitutes & commoditisation | Restraint | Moderate | Compresses entry-tier ASPs and margins |
The balance clearly favours growth, but the composition of that growth is shifting. Hardware-led volume expansion is being outpaced by value migration toward software, cloud subscriptions and OEM integration. The second-order effect: vendors that win unit share in budget tiers may still lose revenue share as blended ASPs fall unless they attach recurring services.
Competition is moderately concentrated, with a handful of specialists holding brand equity in premium tiers while low-cost Asian manufacturers dominate volume and OEM supply.
| Vendor | Home base | Core strength | Strategic positioning |
|---|---|---|---|
| Garmin Ltd. | USA/Switzerland | Brand, retail distribution | Premium consumer, GPS-integrated |
| Nextbase | UK | Insurance partnerships, retail | Mid-to-premium consumer, UK/EU anchor |
| Pittasoft (BlackVue) | South Korea | Cloud, dual-channel engineering | Premium connected devices |
| Thinkware | South Korea | Image quality, OEM relationships | Premium consumer and fleet |
| ABEO Technology | Taiwan | Manufacturing scale | OEM/ODM supply, value tiers |
Differentiation rests on three moats: brand trust in evidential reliability, insurance and OEM certification, and software ecosystems (cloud storage, incident alerts, AI analytics). Hardware specs are converging fast, so the durable advantage is certification and service attachment — not sensor resolution. This implies that new entrants competing purely on price will struggle to escape the budget tier.
Procurement decisions should be anchored on evidential reliability, not headline specifications. Buyers should prioritise verified loop-recording integrity, low-light performance, wide dynamic range and tamper-evident file handling — because footage that fails in a claims dispute has zero value regardless of resolution.
Regulatory compliance is a live risk. GDPR and comparable privacy regimes constrain always-on and audio recording in several jurisdictions, and rules differ by country. Fleet operators deploying multi-channel systems must build data-retention, consent and access-control policies into procurement, not bolt them on afterwards.
Switching costs rise sharply with ecosystem lock-in. Cloud subscription tiers, proprietary mounting systems and vendor-specific analytics create friction on replacement cycles. Buyers should negotiate data portability and standard-format export clauses at contract stage. For OEM programmes, automotive-grade reliability certification and multi-function integration are increasingly the entry ticket — suppliers unable to certify will be excluded from the fastest-growing channel.
The balance of evidence favours a selective-growth position rather than a uniform market-bullish one. Headline CAGR of roughly 4.7–5.1% is respectable but unspectacular, and it masks a sharp internal divergence: aftermarket entry-tier hardware is commoditising while dual-channel, connected and OEM-fitted tiers expand materially faster. The strongest counter-argument is that AI-enabled video analytics could re-rate the entire category upward by converting passive recorders into active risk-mitigation subscriptions — but that outcome depends on insurer and fleet willingness to pay recurring fees, which remains unproven at scale outside commercial fleets.
Our judgement is that the market's centre of gravity is migrating from a consumer electronics retail story to an insurance-and-fleet services story. Vendors with certification pathways into OEM programmes and insurer discount schemes hold the most defensible position; those dependent on retail shelf space and price competition face persistent margin erosion. The privacy-regulation overhang is real but narrow — it caps certain always-on use cases rather than suppressing underlying demand.
Actionable strategy:
What would change this conclusion: evidence that AI analytics subscriptions achieve meaningful attach rates in private-passenger lines, or that privacy rulings materially restrict dash-camera use in a major European market. Either would shift the risk-reward balance decisively. Precise sub-segment forecasting — particularly the OEM-versus-aftermarket split and country-level pricing — requires the full dataset beyond this overview.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.7% from 2020-2034 |
| Segmentation |
|
The global car DVR market was valued at approximately USD 3.5 billion in 2025. Broader-scope estimates reach higher figures by including OEM-fitted ADAS camera modules and adjacent telematics hardware that narrower definitions exclude.
Published forecasts cluster around a 4.7% to 5.1% CAGR through the early 2030s. The spread reflects differing scope definitions rather than genuine disagreement about underlying unit demand, which remains steady across both aftermarket and OEM channels.
Europe and North America jointly account for roughly 60% of global revenue, led by Europe's regulatory mandates and North America's insurance-incentive programmes. Asia Pacific is the fastest-growing region, driven by Chinese demand and export manufacturing scale.
Dual-channel front-and-rear systems are growing fastest among product types, at roughly 5.3% CAGR. OEM-installed channels grow faster still at around 7.2% CAGR from a smaller base, reflecting automaker bundling of camera safety suites.
Leading vendors include Garmin, Nextbase, Pittasoft (BlackVue), Thinkware and ABEO Technology. Competition is moderately concentrated, with specialists holding premium brand equity while Asian manufacturers dominate volume and OEM supply.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted with category managers at consumer-electronics retailers and e-commerce platforms, automotive-accessories distributor procurement leads, insurance telematics and risk-assessment specialists, OEM safety-suite engineers, and dash-camera contract manufacturers across Taiwan, South Korea and China. Interviewees included VP-level Sourcing, Heads of Product R&D, Commercial Operations Leads and Insurance Underwriting Directors, validating preference trends, incentive-programme penetration and channel economics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & R&D Leads | 35% |
| Sourcing & Procurement Directors | 30% |
| Commercial & Channel Operations | 20% |
| Insurance & Risk Underwriters | 15% |
| Company Type | Representation (%) |
|---|---|
| Dash Camera Manufacturers & ODMs | 40% |
| Retail & E-commerce Distributors | 25% |
| OEM & Tier-One Suppliers | 20% |
| Insurers & Fleet Operators | 15% |
Secondary research aggregated UN Comtrade bilateral trade flows for camera modules and consumer electronics, WTO tariff schedules, Eurostat and US ITC import data, corporate 10-K and annual investor filings from listed consumer-electronics firms with dash-camera lines, patent databases covering recording and ADAS integration, and road-safety statistics from national traffic authorities establishing the evidential use case.
Top-down macroeconomic allocation by vehicle parc and consumer-electronics spend ran simultaneously with bottom-up modelling of manufacturer capacity, average selling prices by tier and end-use consumption. Divergences between the two approaches were reconciled against e-commerce category gross-merchandise-value estimates and public revenue disclosures.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow & consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |