Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Automotive Steel Market: Global Size, Trends & Forecast 2026
Automotive Steel Market
Automotive Steel Market: Global Size, Trends & Forecast 2026
Automotive Steel Market by Process (Basic Oxygen Furnace, Electric Arc Furnace), by Vehicle (Passenger Vehicles, Light Commercial Vehicles, Heavy Commercial Vehicles, Two-Wheeler Vehicles), by Product Grade (Low Strength Steel, Conventional HSS, Advanced High Strength Steel, Others), by Application (Body Structure, Powertrain, Suspension, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Indonesia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 202
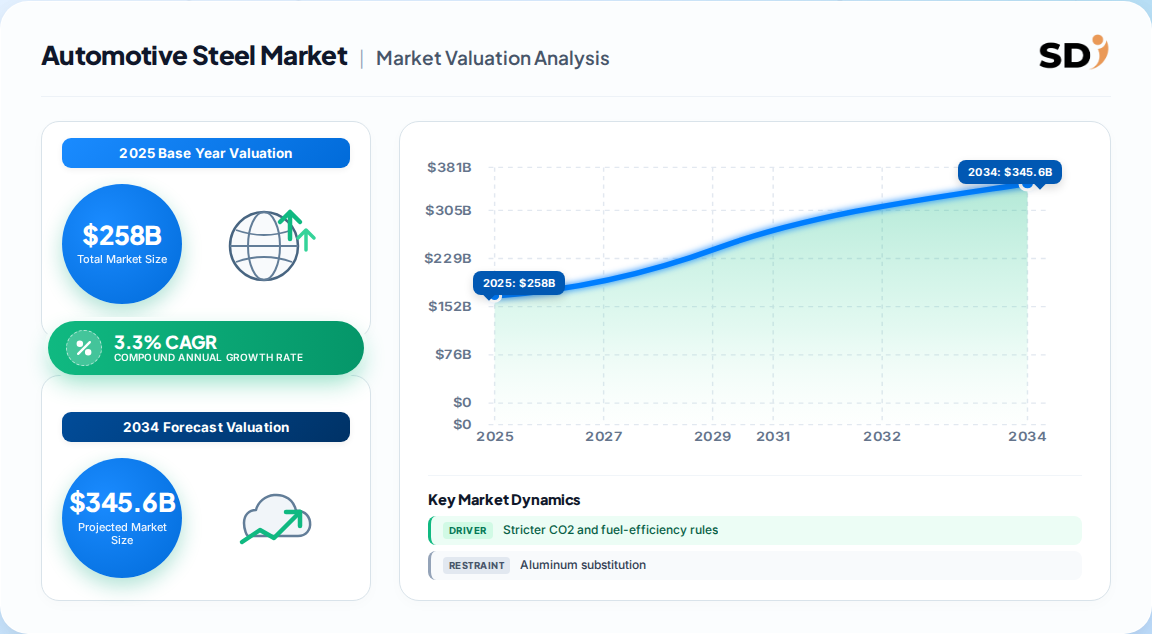
The global automotive steel market reached USD 258 billion in 2025, with a forecast horizon to 2030 and a projected value of USD 303 billion.
Growth runs at a 3.3% CAGR (2025–2030), materially slower than adjacent automotive-metal categories, reflecting steel's maturity and share pressure from aluminum.
Advanced high-strength steel (AHSS) is the fastest-growing product tier, eclipsing conventional HSS as OEMs chase weight savings without sacrificing crash performance.
Asia-Pacific dominates with roughly 53.5% of global value, led by China, Japan, India and South Korea; Europe and North America follow on regulatory lightweighting.
Leading vendors include ArcelorMittal, POSCO, Nippon Steel, Tata Steel, Baowu, Hyundai Steel, JFE, Nucor and SSAB, competing increasingly on low-carbon steel credentials.
Steel retains ~56% of the broader automotive-metal mix, but aluminum is advancing at an 8.7% CAGR — the central competitive tension in this market.
Why this matters for decision-makers: Steel suppliers that fail to commercialize AHSS and low-carbon EAF/H2-DRI grades by 2030 will cede structural body-in-white share to aluminum and gigacast incumbents, compressing margins on commodity-grade volumes.
Automotive Steel Market Size (In Billion)
400.0B
300.0B
200.0B
100.0B
0
249.0 B
2024
258.0 B
2025
266.0 B
2026
275.0 B
2027
284.0 B
2028
294.0 B
2029
303.0 B
2030
Automotive Steel Market Size (In Billion)
Year
Market Size
2024
249.0 B
2025
258.0 B
2026
266.0 B
2027
275.0 B
2028
284.0 B
2029
294.0 B
2030
303.0 B
What is the Automotive Steel Market?
The automotive steel market encompasses the production, distribution and application of flat and long steel products — including low-strength, conventional HSS and advanced high-strength steel — used in vehicle body structures, powertrains, suspensions and chassis. It is defined by strength-to-weight performance, formability, weldability and, increasingly, carbon intensity of production.
Scope: what this report covers and excludes
This report covers global automotive steel demand across passenger vehicles, light and heavy commercial vehicles and two-wheelers, segmented by furnace process (BOF, EAF), product grade and application. It quantifies value in USD and volume in thousand tons across 2021–2030. This analysis does not cover aluminum, magnesium, titanium or composite automotive materials except as competitive benchmarks; nor does it cover downstream stamping services or aftermarket parts distribution, which are separate value-chain segments.
How big is the market for Automotive Steel Market?
Benchmark estimates diverge sharply, largely because of definitional scope. The table below normalizes competing figures by coverage to help buyers judge which anchor is defensible for planning.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 112.93 Billion
2021
2030
3.1%
Core automotive steel, value terms
One published estimate
USD 258 Billion (synthesized to 2025)
2025
2030
3.3%
Automotive steel, wider definition incl. full value chain
Our triangulated analysis
USD 18.98 Billion → 36.28 Billion
2023
2033
6.69%
Automotive high-strength steel subset only
A competing analysis
USD 4.7 Billion → 11.7 Billion
2025
2033
12.1%
Narrow, likely mis-scoped segment
A competing analysis
USD 184.30 Billion → 234.21 Billion
2025
2030
4.91%
All automotive metals, not steel alone
A competing analysis
Our analysis suggests the 3.1–3.3% CAGR band is the most defensible anchor. It aligns with the 2021 base of USD 112.93 billion, which compounds to roughly USD 162 billion by 2030 under steel-only scope. The much higher USD 258 billion 2025 figure reflects full value-chain capture (including coils, stamped blanks and distribution margin), while the 12.1% figure conflates a narrow sub-segment with the broader market and should be discounted for planning purposes.
How is the market segmented?
Segment structure is defined by furnace route, vehicle class, product grade and application. Product grade is the most commercially consequential split because it determines margin and competitive intensity.
Parent segment
Children
By Process
Basic Oxygen Furnace (BOF), Electric Arc Furnace (EAF)
By Vehicle
Passenger Vehicles, Light Commercial Vehicles, Heavy Commercial Vehicles, Two-Wheeler Vehicles
AHSS is projected to exceed USD 68.9 billion by 2030, driven by dual-phase and TRIP grades in body-in-white and chassis. Body structure alone will approach USD 66.6 billion. BOF retains cost-driven dominance (~USD 111 billion by 2030), but EAF gains ground wherever low-carbon procurement rules bite.
Which region leads in Automotive Steel Market?
Asia-Pacific leads with roughly 53.5% of global value, underpinned by China's automotive production scale, Japan and South Korea's high-grade steel capability, and India's expanding passenger-vehicle base.
Automotive Steel Market Regional Market Share
Loading chart...
Automotive Steel Market Regional Market Share
Region
Market Share (%)
North America
0.14%
Europe
0.19%
Asia-Pacific
0.54%
South America
0.08%
Middle East & Africa
0.06%
Asia-Pacific — China, Japan, India, South Korea, Indonesia
Europe — Germany, UK, France, Italy, Spain
North America — USA, Canada, Mexico
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa
Asia-Pacific is forecast near 3.4% CAGR to reach roughly USD 86 billion by 2030 on steel-only scope. Europe's growth is regulation-led (CO2 fleet targets, CBAM), while North America is shaped by USMCA content rules and nearshoring of EV assembly. Our analysis suggests Europe's low-carbon steel premium will be the single largest regional margin differentiator post-2026.
What is driving growth — and what is holding it back?
Growth is a tug-of-war between regulatory lightweighting and material substitution, with electrification acting as both accelerant and disruptor for steel.
Factor
Direction
Evidence strength
Mechanism
Stricter CO2 / fuel-efficiency rules
Driver
High
Forces lightweighting, favors AHSS grades
Rapid EV production surge
Driver
High
Battery-pack-adjacent structural demand; AHSS in motor housings
EV adoption & government electrification incentives
Driver
Medium
Supports vehicle volumes overall
Low-carbon EAF / H2-DRI steel
Driver
Medium
Procurement mandates create premium niche
Aluminum substitution
Restraint
High
~8.7% CAGR vs steel's ~3.3%
Price volatility & supply-chain disruption
Restraint
Medium
Input-cost swings squeeze margins
Gigacasting & multi-material designs
Restraint
Medium
Consolidates parts, reduces steel content per vehicle
Our analysis suggests the net balance favors modest but durable steel growth: lightweighting is not anti-steel per se — it is anti-commodity-steel. The real risk is grade mix migration, not volume collapse. Gigacasting is the most under-appreciated threat; its second-order effect is fewer stamped steel assemblies per vehicle, which we estimate could shave 1–2 percentage points off body-structure steel demand per large EV platform.
Who are the leading vendors?
Competition is moderate-to-highly concentrated, with integrated mills and regional champions defending share through grade capability and decarbonization investment.
Company
HQ / Region
Strategic strength
Low-carbon positioning
ArcelorMittal
Luxembourg / Global
Broad AHSS portfolio; OEM co-development
Committed 12 Mt reduced-carbon steel by 2030 (H2-DRI)
POSCO
South Korea
High-grade auto steel; APAC OEM ties
Hydrogen-based HyREX program
Nippon Steel
Japan
Metallurgical R&D; global JV footprint
Hydrogen reduction pilots
Tata Steel
India / Europe
Cost position; EU low-carbon MoU with BHP
Blast-furnace decarbonization collaboration
Baowu Group
China
Scale; domestic OEM lock-in
EAF expansion
Hyundai Steel
South Korea
Captive OEM demand
EAF-heavy route
JFE Steel
Japan
AHSS process expertise
Carbon recycling blast furnace
Nucor
USA
EAF scale (27 Mt target)
Structurally low-carbon
SSAB
Sweden
Premium HSS / AHSS
HYBRIT fossil-free steel pioneer
Differentiation is shifting from tonnage to grade capability and carbon intensity. Moats are built on OEM co-engineering relationships, qualification cycles (often 18–36 months) and CBAM-compliant production. Our analysis suggests Nucor and SSAB hold a structural low-carbon cost advantage, while ArcelorMittal and POSCO lead on breadth of AHSS coverage.
What do buyers and operators need to know?
Mission-critical selection criteria now extend beyond price and mechanical properties to carbon accounting and supply resilience. Buyers should insist on grade-specific qualification data, EPD (Environmental Product Declaration) documentation and disclosure of Scope 1–3 intensity, especially for EU-bound programs. Procurement risk concentrates in three areas: AHSS availability during demand peaks, automotive-grade coil lead times, and CBAM-related cost pass-through post-2026. Switching costs are high because re-qualifying a steel grade for a body-in-white program typically requires crash re-validation and OEM engineering sign-off. Operators should also monitor gigacasting adoption as it can reduce per-vehicle steel part counts and shift sourcing toward integrated castings — a signal to diversify into chassis and battery-enclosure steel applications.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a cautiously constructive outlook for steel in automotive, anchored on the 3.1–3.3% CAGR band, with growth concentrated in AHSS rather than commodity grades. The strongest counter-argument is that aluminum's 8.7% CAGR and gigacasting's rise could accelerate structural substitution, particularly on premium EV platforms. That risk is real but overstated for the 2025–2030 window: steel's cost advantage, established crash performance and incumbent qualification moats make a wholesale shift implausible within five years. What is plausible is grade mix migration — and that is where margin risk actually lives.
Prioritize AHSS and low-carbon grade commercialization — suppliers should target dual-phase and TRIP capacity expansion and secure EPD certification before 2027 to capture EU and North American procurement premiums.
De-risk Asia-Pacific concentration — buyers should qualify secondary suppliers outside China, particularly in India and North America, to hedge against trade-policy and logistics disruption.
Diversify application exposure — operators should pivot R&D toward chassis, battery-enclosure and motor-housing steel applications that gigacasting does not displace.
What would change our conclusion: sustained aluminum price parity below steel on a per-part basis, or a major gigacasting breakthrough in mid-segment (sub-USD 30,000) EVs, would force us to revise the steel CAGR downward toward 2% and accelerate the substitution thesis.
Methodology
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split, built on in-depth interviews with raw material suppliers, specialized steel producers, contract stampers and global automotive distributors. Decision-makers interviewed include VP Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads across OEM and Tier-1 tiers.
Secondary Benchmarking & Public Trade Validation
We cross-validate against UN Comtrade, WTO, US ITC and Eurostat trade databases, corporate 10-K and annual investor filings, patent databases, and recognized industry associations including worldsteel and ACEA. Competitor market-research estimates are excluded by policy.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing and end-use consumption) triangulation, reconciling discrepancies through expert interviews.
Table 9: Automotive Steel Market Revenue Billion Forecast, by Region 2020 & 2034
Table 10: Automotive Steel Market Volume Thousand Tons Forecast, by Region 2020 & 2034
Table 11: North America Automotive Steel Market Revenue Billion Forecast, by Process 2020 & 2034
Table 12: North America Automotive Steel Market Volume Thousand Tons Forecast, by Process 2020 & 2034
Table 13: North America Automotive Steel Market Revenue Billion Forecast, by Vehicle 2020 & 2034
Table 14: North America Automotive Steel Market Volume Thousand Tons Forecast, by Vehicle 2020 & 2034
Table 15: North America Automotive Steel Market Revenue Billion Forecast, by Product Grade 2020 & 2034
Table 16: North America Automotive Steel Market Volume Thousand Tons Forecast, by Product Grade 2020 & 2034
Frequently Asked Questions
1. How big is the automotive steel market in 2025?
The global automotive steel market was valued at approximately USD 258 billion in 2025 on a full value-chain basis. Steel-only benchmarks using a narrower definition put the 2021 base at USD 112.93 billion, compounding to roughly USD 162 billion by 2030 under the 3.1% CAGR band.
2. What is the automotive steel market growth rate?
The most defensible CAGR is 3.1–3.3% through 2030, reflecting a mature steel base offset by AHSS mix enrichment. Sub-segment estimates of 6.69% for high-strength steel and 12.1% for narrowly defined categories should not be extrapolated to the whole market.
3. Which region dominates the automotive steel market?
Asia-Pacific leads with roughly 53.5% of global value, driven by China, Japan, India and South Korea. Europe and North America follow, with Europe's growth shaped by CO2 regulations and CBAM, and North America by USMCA content rules and EV nearshoring.
4. What is driving demand for automotive steel?
Stricter CO2 and fuel-efficiency rules, EV production scaling and low-carbon procurement mandates are the primary drivers. Advanced high-strength steel benefits most, as OEMs pursue weight reduction without compromising crash performance, while aluminum substitution remains the principal restraint.
5. Who are the leading automotive steel suppliers?
Leading suppliers include ArcelorMittal, POSCO, Nippon Steel, Tata Steel, Baowu Group, Hyundai Steel, JFE Steel, Nucor and SSAB. Competition increasingly centres on AHSS grade capability and low-carbon EAF/H2-DRI production credentials rather than tonnage alone.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split, built on in-depth interviews with raw material suppliers, specialized steel producers, contract stampers and global automotive distributors. Decision-makers interviewed include VP Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads across OEM and Tier-1 tiers.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement Directors
40%
R&D & Technical Directors
35%
Commercial Operations Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Steel Producers
45%
Contract Stampers & Formulators
30%
Global Distributors & Traders
25%
Secondary Benchmarking & Public Trade Validation
We cross-validate against UN Comtrade, WTO, US ITC and Eurostat trade databases, corporate 10-K and annual investor filings, patent databases, and recognized industry associations including worldsteel and ACEA. Competitor market-research estimates are excluded by policy.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing and end-use consumption) triangulation, reconciling discrepancies through expert interviews.
 Automotive Steel Market