 Automotive Appearance Chemicals Market
 Outlook 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 257

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Automotive Appearance Chemicals Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
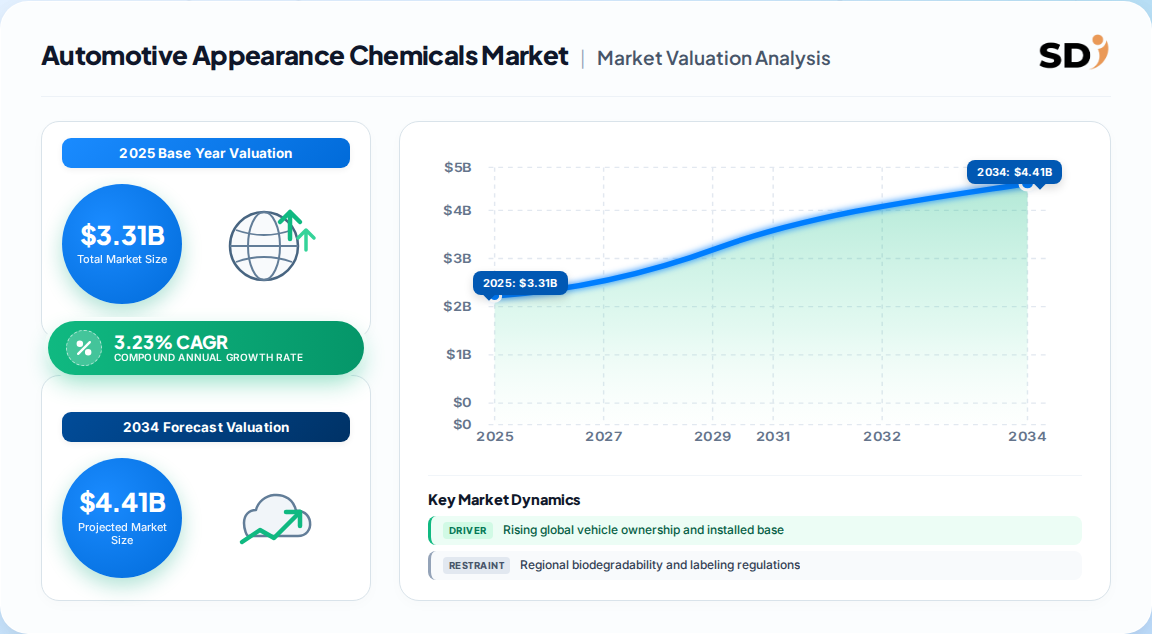
| 2025 | 3.310 B |
| 2026 | 3.420 B |
| 2027 | 3.530 B |
| 2028 | 3.640 B |
| 2029 | 3.760 B |
| 2030 | 3.880 B |
| 2031 | 4.010 B |

The automotive appearance chemicals market covers formulated products that clean, polish, protect, and restore vehicle exterior and interior surfaces. Core categories include waxes and polishes, protectants, wheel and tire cleaners, windshield washer fluids, and specialty care products, sold through DIY retail, e-commerce, and professional detailing channels.
This report covers formulated appearance and care chemicals for passenger cars, light commercial vehicles, and heavy commercial vehicles, segmented by product type, vehicle type, sales channel, and region. It excludes automotive refinish coatings used in collision repair, OEM paint systems, industrial lubricants, fuel additives, and car wash equipment hardware. This analysis does not cover adjacent markets such as automotive fluids beyond washer fluid, tire manufacturing materials, or vehicle interior electronics.
Published estimates diverge sharply on absolute size, from roughly USD 3.3 Billion to over USD 30 Billion, largely because competing analyses define product boundaries differently — some include only consumer-care chemistries, others fold in refinish coatings and OEM paint supply.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 3.31 Billion → 4.40 Billion | 2025 | 2034 | 3.23% | Consumer and professional appearance care; waxes, protectants, cleaners, washer fluid | One published estimate |
| USD 30.38 Billion → 49.05 Billion | 2024 | 2035 | 4.45% | Broader appearance chemicals including sealants and glass/wheel care | A competing analysis |
| USD 27.2 Billion → 43.8 Billion | 2026 | 2036 | 4.9% | Includes windshield washer fluids at 51.3% and refinish-adjacent coatings | A competing analysis |
| ~5.09% CAGR, ~USD 4 Billion by 2030 | 2025 | 2033 | 5.09% | Narrower car-care product set | A competing analysis |
Our analysis suggests the ~USD 3.3 Billion figure is the most defensible for the core appearance-chemical category. The USD 27–30 Billion estimates appear to aggregate refinish coatings, OEM paint, and washer fluid at volumes that materially overstate the pure car-care chemical spend. Buyers should anchor budgets to the 3.2–4.5% CAGR band and treat the higher absolute figures as adjacent-market totals.
Segmentation separates the chemical job performed on the vehicle from the installed vehicle pool and the point of purchase, which is critical because aftermarket purchases dominate revenue.
| Parent segment | Children | 2025 share / growth signal |
|---|---|---|
| By Application | Waxes and polishes; Protectants; Wheel and tire cleaners; Windshield washer fluids; Others | Waxes and polishes 33.2%; protectants ~3.8% CAGR |
| By Vehicle Type | Passenger cars; Light commercial vehicles; Heavy commercial vehicles | Passenger cars 65.0% |
| By Sales Channel | Aftermarket; OEM supply | Aftermarket 94.5% |
| By Product Form | Liquid; Gel; Spray; Concentrate | Premium sprays fastest-growing |
Our analysis suggests the protectants sub-segment is the strategic battleground: ceramic-infused sprays and sealants compress the wax category's share over time, while washer fluid remains a high-frequency, low-margin traffic driver tied to road use and climate rather than discretionary detailing.
Asia-Pacific leads with 37.5% of global revenue in 2025 and grows fastest at ~4.1% CAGR, reflecting China's and India's expanding vehicle parcs, rising disposable incomes, and emerging car care culture.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.38% |
| North America | 0.24% |
| Europe | 0.22% |
| South America | 0.09% |
| Middle East & Africa | 0.08% |
| Region | 2025 share | Growth signal |
|---|---|---|
| Asia-Pacific | 37.5% | ~4.1% CAGR |
| North America | 24.0% | Innovation leader; mature |
| Europe | 22.0% | Regulation-driven reformulation |
| South America | 9.0% | Mid-single-digit growth |
| Middle East & Africa | 7.5% | Emerging, climate-driven demand |
Regional economics diverge by fleet age and resale activity. Italy's 3.15 million used-car transfers in 2024 (up 8.5%) support restoration work before resale, while German demand skews toward preservation and technical fit — a different route to comparable aftermarket spending.
Growth rests on structural demand permanence: roughly 90 million vehicles sold annually and a 297.5 million-unit US registered fleet convert ownership into repeat chemical purchases. Restraints are regulatory and labor-cost driven, not demand-driven.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising global vehicle ownership | Driver | High | Expands installed base and replenishment occasions |
| DIY car care and social media culture | Driver | High | Premiumizes consumer spend; sustains post-COVID shift |
| Professional detailing expansion | Driver | Medium-High | Creates B2B professional-grade channel demand |
| EV adoption (20M+ units in 2025) | Driver | Medium | New surfaces and paint-care needs; new product formats |
| Ceramic coating democratization | Driver | High | Protectants ~3.8% CAGR; premium conversion |
| Biodegradability and labeling rules (e.g., EU 2026/405) | Restraint | High | Regional reformulation raises testing cost; limits one-formula rollout |
| Application time and trained labor | Restraint | Medium | Raises effective cost per premium treatment |
The balance favors growth, but the constraint is margin, not volume. Our analysis suggests regulation-driven reformulation is a scale barrier: small brands lose manufacturing scale when one formula cannot serve multiple national markets, accelerating consolidation toward 3M, BASF, and refinish platforms with compliance infrastructure.
Competition spans consumer auto-care specialists, diversified chemical majors, and refinish coating platforms, with differentiation anchored in brand, formulation IP, and distribution depth rather than raw chemistry alone.
| Company | Category | Core strength | Strategic signal |
|---|---|---|---|
| 3M | Diversified chemical | Brand, abrasives, retail reach | Broad portfolio, premium positioning |
| BASF | Chemical major | Formulation scale, refinish integration | Compliance and OEM adjacency |
| Turtle Wax | Consumer specialist | Legacy brand, DIY retail | Value-to-mid premium |
| Meguiar's | Consumer specialist | Enthusiast brand, premium care | Detailing culture alignment |
| Sonax | Consumer specialist | European premium care | Tech-forward formulations |
| PPG Industries | Refinish platform | Coatings, body-shop network | Fast-cure professional economics |
| Energizer (Armor All) | Consumer specialist | Mass retail, distribution | Volume-led; e-commerce expansion |
| SOFT99 | Consumer specialist | Japan/Asia premium | Regional depth |
| Axalta | Refinish platform | Independent distribution (40+ EU centers) | Aftermarket access moat |
Our analysis suggests the deepest moat sits with players combining formulation IP and aftermarket distribution — Axalta's February 2025 acquisition of three European distributors shows channel control can shift chemical availability independently of factory output. Consumer-only brands face margin pressure as ceramic hybrids commoditize the wax premium.
Selection criteria should weight durability and curing time over unit price, because labor and bay occupancy dominate total treatment cost in professional channels. Buyers should verify biodegradability documentation and regional labeling compliance before multi-country rollout; EU surfactant rules already force portfolio-specific reformulation. Switching costs are moderate at the formulation level but high at the training and distribution level, where technician support locks in repeat purchases. Procurement risk concentrates in single-formula dependence: a supplier unable to serve multiple regulatory regimes creates stock-out and compliance exposure. Operators should also stress-test supply against washer-fluid seasonality and climate-driven demand swings, and negotiate volume tiers that reflect the 94.5% aftermarket replenishment economics rather than OEM cycle timing.
The balance of evidence favors a moderate-growth, structurally resilient market rather than a high-growth one. The 3.23% CAGR is credible because demand is tied to the installed vehicle base and repeat consumption, not discretionary spending; the higher 4.4–5.1% estimates likely reflect broader product boundaries. The strongest counter-argument is that ceramic coating democratization could accelerate premium conversion faster than forecast, pulling protectants and sealants above the headline CAGR and lifting average revenue per treatment.
Our judgment is that value migrates to the professional/DIY interface: products that shorten application steps or curing time justify premium pricing without weakening finish quality, and distribution alliances determine who captures that premium. Vendors relying on legacy wax volumes face gradual share erosion, while those pairing eco-compliant formulations with technician support and e-commerce discovery are best positioned. Precise sub-segment forecasting — particularly ceramic hybrid pricing and country-level washer-fluid volumes — requires the full model, since public benchmarks diverge too widely for confident planning.
Evidence that would change this conclusion: sustained ceramic-coating price deflation, a regulatory harmonization that lowers reformulation costs, or EV-specific care products scaling faster than current adoption signals suggest.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.23% from 2020-2034 |
| Segmentation |
|
The global market reached USD 3.31 Billion in 2025 and is projected to reach USD 4.40 Billion by 2034 at a 3.23% CAGR. Broader estimates of USD 27–30 Billion include refinish coatings and OEM paint, inflating the core car-care category.
Asia-Pacific leads with 37.5% of global revenue in 2025 and grows fastest at roughly 4.1% CAGR, driven by China and India vehicle parc expansion, rising disposable incomes, and emerging car care culture.
Protectants grow at about 3.8% CAGR and wheel and tire cleaners at 3.5%, outpacing the overall market as ceramic coating technology moves from professional-only to consumer-accessible formats and wheel diversity increases.
Key players include 3M, BASF, Turtle Wax, Meguiar's, Sonax, PPG Industries, Energizer (Armor All), SOFT99, Axalta, and Valvoline, spanning consumer auto-care specialists, chemical majors, and refinish coating platforms.
Biodegradability and labeling regulations, such as EU 2026/405, force regional reformulation and raise testing costs, limiting one-formula global commercialization. Application time and trained labor also constrain premium conversion in professional channels.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material and surfactant suppliers, specialty chemical producers, contract formulators and blenders, and global distributors serving retail and professional channels. Decision-maker designations interviewed included VP-level Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring both chemistry and route-to-market perspectives inform demand estimates.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Directors | 30% |
| Technical & Quality Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Surfactant Suppliers | 30% |
| Specialty Chemical Producers | 40% |
| Contract Formulators & Blenders | 20% |
| Global Distributors & Retailers | 10% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and 10-K disclosures, patent databases for formulation innovation tracking, and recognized technical standards and industry associations. Regulatory texts covering surfactant biodegradability and labeling requirements are reviewed to model reformulation cost exposure across regions.
Sizing runs simultaneously top-down (macroeconomic vehicle parc and segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling). Discrepancies are reconciled through volume-price cross-checks, with washer-fluid consumption tied to vehicle-miles traveled and detailing frequency to channel data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |