Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Electric Vehicle EV Traction Motor Market 2026
Electric Vehicle EV Traction Motor Market 2026
Electric Vehicle Ev Traction Motor Market
Electric Vehicle EV Traction Motor Market 2026
Electric Vehicle Ev Traction Motor Market by Vehicle Type (Battery Electric, Plug-in Hybrid, Mild Hybrid, Full Hybrid), by Motor Type (PMSM, Induction, Switched Reluctance, Wound Rotor Synchronous, BLDC), by Voltage Rating (High Voltage, Low Voltage), by Power Output (Below 200 kW, 200-400 kW, Above 400 kW), by Application (Passenger EV, Electric Bus, Electric Truck, Railway, Industrial Machinery), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Poland, Romania), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 261
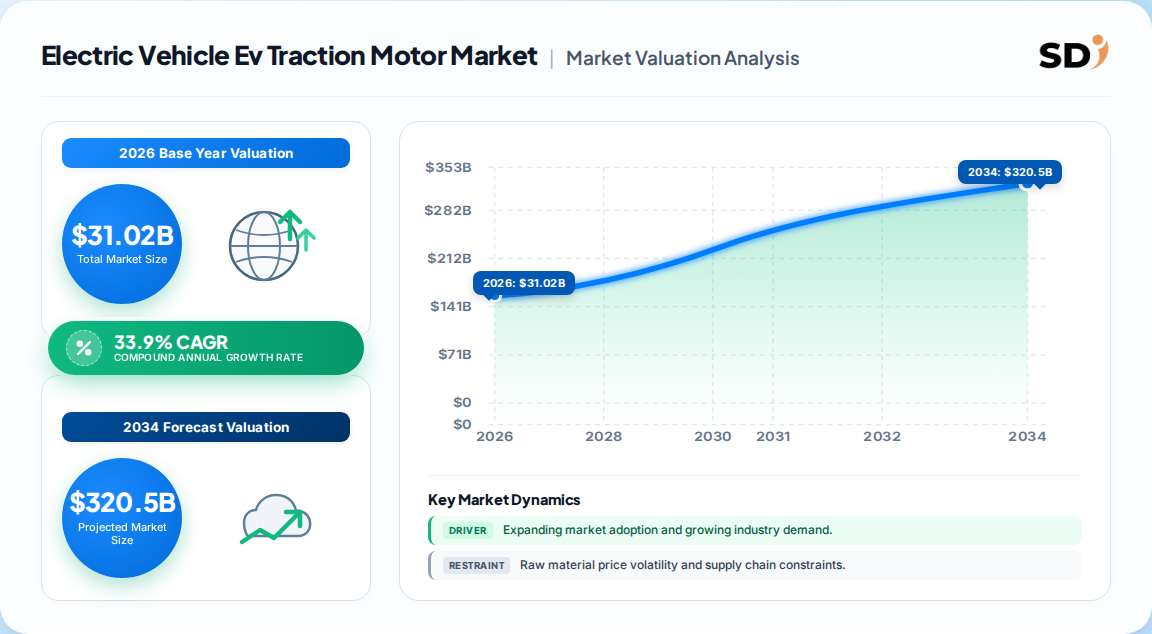
The global EV traction motor market was valued at roughly 31.0 Billion in 2026, with aggressive published forecasts spanning 74.1 Billion by 2030 to 494 Billion by 2034.
Forecast CAGR estimates diverge sharply — from ~30% to ~41% — because analysts treat mild hybrids, commercial vehicles, and power electronics integration differently.
Battery electric vehicles dominate demand (~52–74% of revenue), and permanent magnet synchronous motors remain the default architecture at roughly two-thirds of motor revenue.
Asia-Pacific leads with 45–55% share, anchored by China's dominance in both passenger EV and electric truck production.
High-voltage architectures (≥400V) hold roughly 73% of value, while 200–400 kW is the fastest-growing power band on commercial-vehicle traction.
Bosch, BYD, Nidec, ZF, Magna, and Valeo anchor the competitive field; the top five commercial-vehicle suppliers hold about 62% share.
Why this matters for decision-makers: unit volumes are growing faster than revenue, so suppliers that cannot drive down cost-per-motor while holding thermal durability will face structural margin compression regardless of demand.
Electric Vehicle Ev Traction Motor Market Size (In Billion)
150.0B
100.0B
50.0B
0
21.95 B
2025
31.02 B
2026
41.53 B
2027
55.61 B
2028
74.46 B
2029
99.70 B
2030
133.5 B
2031
Electric Vehicle Ev Traction Motor Market Size (In Billion)
Year
Market Size
2025
21.95 B
2026
31.02 B
2027
41.53 B
2028
55.61 B
2029
74.46 B
2030
99.70 B
2031
133.5 B
What is the Electric Vehicle Ev Traction Motor Market?
The EV traction motor market covers the propulsion motors — predominantly permanent magnet synchronous, induction, and switched reluctance machines — plus integrated e-axle assemblies that convert battery energy into wheel torque in battery, plug-in, mild, and full hybrid vehicles. It spans passenger cars, buses, and commercial trucks across high- and low-voltage architectures.
Scope: what this report covers and excludes
This analysis covers traction motors and integrated motor-inverter-gearing assemblies for on-road electric and hybrid vehicles, segmented by vehicle type, motor technology, voltage class, power output, and application (passenger EV, bus, commercial truck, rail, industrial).
It excludes battery cells and packs, on-board chargers, charging infrastructure, power-semiconductor supply chains treated as standalone markets, and off-highway mining or marine traction. This analysis does not cover adjacent motor markets such as HVAC blowers, pumps, or stationary industrial drives.
How big is the market for Electric Vehicle Ev Traction Motor Market?
Published 2026 base estimates cluster near 31 Billion, but horizon values diverge dramatically because each analyst defines the boundary between "traction motor" and "integrated e-axle" differently.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
31.0B → 494.1B
2026
2034
41.3%
EV traction motors incl. hybrid, broad application set
One published estimate
30.7B → 74.1B
2026
2030
30.2%
BEV/PHEV traction motors only
A competing analysis
17.1B → 316.8B
2025
2035
33.9%
BEV, PHEV, FCEV, hybrid; BLDC/induction/PMSM
A competing analysis
3.4B → 16.0B
2025
2035
16.8%
Electric commercial vehicle traction motors only
A competing analysis
Our analysis suggests the 30–34% CAGR band is the most defensible for the pure passenger-plus-commercial EV motor market through 2030; the 41% figure likely embeds aggressive hybrid inclusion and price-inflation assumptions. The 16.8% commercial-vehicle figure is credible but reflects a narrower, lower-volume segment with faster unit growth (~21%) than revenue growth.
How is the market segmented?
Segmentation matters commercially because motor architecture, voltage class, and power band determine which suppliers can compete — a 200 kW passenger PMSM and a 400 kW heavy-truck e-axle share little supply base.
Parent segment
Children
By Vehicle Type
Battery Electric, Plug-in Hybrid, Mild Hybrid, Full Hybrid
Passenger EV, Electric Bus, Electric Truck, Railway, Industrial Machinery
By Integration
Standalone motor, Integrated e-axle
PMSM holds roughly 67–75% of motor-type revenue thanks to torque density and efficiency, while switched reluctance is the fastest-growing niche as OEMs pursue rare-earth-free designs.
Which region leads in Electric Vehicle Ev Traction Motor Market?
Asia-Pacific leads with an estimated 45–55% revenue share, driven by China's combined dominance in passenger EV output, electric bus manufacturing, and more than 80% of global electric truck sales.
Electric Vehicle Ev Traction Motor Market Regional Market Share
Loading chart...
Electric Vehicle Ev Traction Motor Market Regional Market Share
Region
Market Share (%)
North America
0.21%
Europe
0.24%
Asia-Pacific
0.6%
South America
0.04%
Middle East & Africa
0.03%
Asia-Pacific
China (dominant; passenger EV + commercial truck volume center)
Japan (PMSM, SiC inverter leadership)
South Korea (cell and motor integration)
India (PLI-backed localization, emerging)
Europe
Germany, France, UK, Italy, Poland, Romania (EU CO₂ mandates, CBAM localization)
North America
USA, Canada, Mexico (fastest-growing region by CAGR)
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — UAE, Saudi Arabia, South Africa
Region
Est. share (2025–26)
Asia-Pacific
60%
Europe
24%
North America
21%
Latin America
4%
Middle East & Africa
3%
Note: shares are indicative consensus ranges; regional definitions vary by source.
What is driving growth — and what is holding it back?
Demand is essentially derivative of EV production volume: global electric car sales exceeded 20 million units in 2025, and each BEV requires one or more propulsion motors.
Factor
Direction
Evidence strength
Mechanism
Record EV production (20M+ cars, 90k+ e-trucks)
Driver
Strong
Direct unit pull for motors
Emission mandates (EPA Phase 3, EU 2024/1610)
Driver
Strong
Converts targets into sourcing requirements
Axial-flux and SiC adoption
Driver
Moderate
Higher power density, new tooling demand
Commercial fleet TCO parity
Driver
Moderate
Route-specific electrification
Rare-earth concentration (~91% China refining)
Restraint
Strong
Cost and supply risk on PMSM
Thermal limits above 400 kW
Restraint
Moderate
Engineering cost, derating
Recycling infrastructure (<2% EU magnet recovery)
Restraint
Moderate
Secondary supply constraint
Price compression per motor
Restraint
Strong
Volume growth outpaces revenue
The balance favors demand decisively through 2030. The binding constraint is not willingness to buy motors but the ability to manufacture them at declining unit prices while securing magnet supply.
Who are the leading vendors?
The competitive field is bifurcated: integrated Tier-1 system suppliers dominate e-axle value, while Chinese motor specialists dominate volume.
Vendor
Position
Differentiation
Bosch
Commercial-vehicle leader (~20% share)
System integration, fleet service
BYD
Vertically integrated
In-house motors, cost scale
Nidec
High-volume motor specialist
Traction motor dedicated capacity
ZF
E-axle systems
Integrated drivetrain, 800V
Magna
Powertrain integration
OEM contract manufacturing
Valeo
Broad portfolio
48V to high-voltage range
Mercedes-Benz / BMW
In-house premium
Axial-flux, eDrive vertical integration
Moats are shifting from motor design toward thermal management, software calibration, and manufacturing precision. Premium OEMs are insourcing e-axle production, pressuring incumbents toward higher-power and service-oriented niches.
What do buyers and operators need to know?
Selection criteria have moved beyond nameplate efficiency. Buyers should weight continuous thermal performance under real duty cycles, because a motor that derates in sustained load destroys fleet economics more than a 2% efficiency gap.
Procurement risk concentrates in rare-earth exposure. PMSM designs depend on NdFeB magnets with ~91% of refining concentrated in one country; dual-sourcing or switched-reluctance alternatives carry qualification costs but reduce trade-restriction exposure.
Integration depth is a hidden switching cost. Once an OEM designs around a specific e-axle envelope, re-sourcing requires re-validating cooling, inverter calibration, and NVH — typically 18–24 months. Regulatory compliance (EU CO₂ rules, CBAM landed-cost premiums up to ~12%, IEC 60349 for rail) should be priced into total cost, not treated as a post-award issue.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors volume-led cost leadership in standardized light and medium-duty applications, where PMSM plus single-speed architectures are commoditizing and price compression is most acute. Suppliers competing there must win on manufacturing yield and magnet sourcing, not differentiation.
Counter-argument: the premium and heavy-duty segments resist commoditization because thermal durability and system validation cannot be substituted component-by-component. A supplier betting entirely on scale could be outflanked by system integrators defending e-axle value. Our assessment is that both strategies are viable — but not within the same organization without distinct cost structures.
Actionable strategy:
Vendors should prioritize rare-earth-light or switched-reluctance platforms for the 2028+ model cycle to hedge supply and CBAM exposure.
Investors should favor suppliers with integrated e-axle capability and 800V validation over standalone motor capacity.
Operators should contract on continuous-power guarantees and thermal derating curves, not peak specifications.
Evidence that would change this conclusion: a sustained rare-earth price collapse, or a breakthrough in magnet recycling above 20% recovery, would erode the strategic premium now attached to magnet-independent architectures.
Electric Vehicle Ev Traction Motor Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Electric Vehicle Ev Traction Motor Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 33.9% from 2020-2034
Segmentation
By Vehicle Type
Battery Electric
Plug-in Hybrid
Mild Hybrid
Full Hybrid
By Motor Type
PMSM
Induction
Switched Reluctance
Wound Rotor Synchronous
BLDC
By Voltage Rating
High Voltage
Low Voltage
By Power Output
Below 200 kW
200-400 kW
Above 400 kW
By Application
Passenger EV
Electric Bus
Electric Truck
Railway
Industrial Machinery
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Poland
Romania
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Vehicle Type
5.1.1. Battery Electric
5.1.2. Plug-in Hybrid
5.1.3. Mild Hybrid
5.1.4. Full Hybrid
5.2. Market Analysis, Insights and Forecast - by Motor Type
5.2.1. PMSM
5.2.2. Induction
5.2.3. Switched Reluctance
5.2.4. Wound Rotor Synchronous
5.2.5. BLDC
5.3. Market Analysis, Insights and Forecast - by Voltage Rating
5.3.1. High Voltage
5.3.2. Low Voltage
5.4. Market Analysis, Insights and Forecast - by Power Output
5.4.1. Below 200 kW
5.4.2. 200-400 kW
5.4.3. Above 400 kW
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Passenger EV
5.5.2. Electric Bus
5.5.3. Electric Truck
5.5.4. Railway
5.5.5. Industrial Machinery
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Vehicle Type
6.1.1. Battery Electric
6.1.2. Plug-in Hybrid
6.1.3. Mild Hybrid
6.1.4. Full Hybrid
6.2. Market Analysis, Insights and Forecast - by Motor Type
6.2.1. PMSM
6.2.2. Induction
6.2.3. Switched Reluctance
6.2.4. Wound Rotor Synchronous
6.2.5. BLDC
6.3. Market Analysis, Insights and Forecast - by Voltage Rating
6.3.1. High Voltage
6.3.2. Low Voltage
6.4. Market Analysis, Insights and Forecast - by Power Output
6.4.1. Below 200 kW
6.4.2. 200-400 kW
6.4.3. Above 400 kW
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Passenger EV
6.5.2. Electric Bus
6.5.3. Electric Truck
6.5.4. Railway
6.5.5. Industrial Machinery
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Vehicle Type
7.1.1. Battery Electric
7.1.2. Plug-in Hybrid
7.1.3. Mild Hybrid
7.1.4. Full Hybrid
7.2. Market Analysis, Insights and Forecast - by Motor Type
7.2.1. PMSM
7.2.2. Induction
7.2.3. Switched Reluctance
7.2.4. Wound Rotor Synchronous
7.2.5. BLDC
7.3. Market Analysis, Insights and Forecast - by Voltage Rating
7.3.1. High Voltage
7.3.2. Low Voltage
7.4. Market Analysis, Insights and Forecast - by Power Output
7.4.1. Below 200 kW
7.4.2. 200-400 kW
7.4.3. Above 400 kW
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Passenger EV
7.5.2. Electric Bus
7.5.3. Electric Truck
7.5.4. Railway
7.5.5. Industrial Machinery
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Vehicle Type
8.1.1. Battery Electric
8.1.2. Plug-in Hybrid
8.1.3. Mild Hybrid
8.1.4. Full Hybrid
8.2. Market Analysis, Insights and Forecast - by Motor Type
8.2.1. PMSM
8.2.2. Induction
8.2.3. Switched Reluctance
8.2.4. Wound Rotor Synchronous
8.2.5. BLDC
8.3. Market Analysis, Insights and Forecast - by Voltage Rating
8.3.1. High Voltage
8.3.2. Low Voltage
8.4. Market Analysis, Insights and Forecast - by Power Output
8.4.1. Below 200 kW
8.4.2. 200-400 kW
8.4.3. Above 400 kW
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Passenger EV
8.5.2. Electric Bus
8.5.3. Electric Truck
8.5.4. Railway
8.5.5. Industrial Machinery
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Vehicle Type
9.1.1. Battery Electric
9.1.2. Plug-in Hybrid
9.1.3. Mild Hybrid
9.1.4. Full Hybrid
9.2. Market Analysis, Insights and Forecast - by Motor Type
9.2.1. PMSM
9.2.2. Induction
9.2.3. Switched Reluctance
9.2.4. Wound Rotor Synchronous
9.2.5. BLDC
9.3. Market Analysis, Insights and Forecast - by Voltage Rating
9.3.1. High Voltage
9.3.2. Low Voltage
9.4. Market Analysis, Insights and Forecast - by Power Output
9.4.1. Below 200 kW
9.4.2. 200-400 kW
9.4.3. Above 400 kW
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Passenger EV
9.5.2. Electric Bus
9.5.3. Electric Truck
9.5.4. Railway
9.5.5. Industrial Machinery
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Vehicle Type
10.1.1. Battery Electric
10.1.2. Plug-in Hybrid
10.1.3. Mild Hybrid
10.1.4. Full Hybrid
10.2. Market Analysis, Insights and Forecast - by Motor Type
10.2.1. PMSM
10.2.2. Induction
10.2.3. Switched Reluctance
10.2.4. Wound Rotor Synchronous
10.2.5. BLDC
10.3. Market Analysis, Insights and Forecast - by Voltage Rating
10.3.1. High Voltage
10.3.2. Low Voltage
10.4. Market Analysis, Insights and Forecast - by Power Output
10.4.1. Below 200 kW
10.4.2. 200-400 kW
10.4.3. Above 400 kW
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Passenger EV
10.5.2. Electric Bus
10.5.3. Electric Truck
10.5.4. Railway
10.5.5. Industrial Machinery
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Electric Vehicle Ev Traction Motor Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Electric Vehicle Ev Traction Motor Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 3: North America Electric Vehicle Ev Traction Motor Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 4: North America Electric Vehicle Ev Traction Motor Market Revenue (Billion), by Motor Type 2026 & 2034
Figure 5: North America Electric Vehicle Ev Traction Motor Market Revenue Share (%), by Motor Type 2026 & 2034
Figure 6: North America Electric Vehicle Ev Traction Motor Market Revenue (Billion), by Voltage Rating 2026 & 2034
Figure 7: North America Electric Vehicle Ev Traction Motor Market Revenue Share (%), by Voltage Rating 2026 & 2034
Figure 8: North America Electric Vehicle Ev Traction Motor Market Revenue (Billion), by Power Output 2026 & 2034
Figure 9: North America Electric Vehicle Ev Traction Motor Market Revenue Share (%), by Power Output 2026 & 2034
Figure 10: North America Electric Vehicle Ev Traction Motor Market Revenue (Billion), by Application 2026 & 2034
Figure 11: North America Electric Vehicle Ev Traction Motor Market Revenue Share (%), by Application 2026 & 2034
Figure 12: North America Electric Vehicle Ev Traction Motor Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Electric Vehicle Ev Traction Motor Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Electric Vehicle Ev Traction Motor Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 15: Europe Electric Vehicle Ev Traction Motor Market Revenue Share (%), by Vehicle Type 2026 & 2034
List of Tables
Table 1: Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 2: Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Motor Type 2020 & 2034
Table 3: Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Voltage Rating 2020 & 2034
Table 4: Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 5: Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 8: North America Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Motor Type 2020 & 2034
Table 9: North America Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Voltage Rating 2020 & 2034
Table 10: North America Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 11: North America Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: North America Electric Vehicle Ev Traction Motor Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Electric Vehicle Ev Traction Motor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Electric Vehicle Ev Traction Motor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Electric Vehicle Ev Traction Motor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the EV traction motor market in 2026?
Published estimates cluster around 31 Billion for 2026, though ranges from roughly 17 to 31 Billion appear depending on whether hybrids and integrated e-axles are included. The 30–34% CAGR band through 2030 is the most defensible consensus.
2. Which motor type dominates EV traction motors?
Permanent magnet synchronous motors hold roughly two-thirds to three-quarters of revenue due to high torque density and efficiency. Switched reluctance is the fastest-growing alternative as automakers reduce rare-earth dependence.
3. Which region leads the EV traction motor market?
Asia-Pacific leads with an estimated 45–60% share, driven by China's dominance in passenger EV and electric truck production. North America is the fastest-growing region by CAGR.
4. What is holding back EV traction motor growth?
Rare-earth supply concentration, with roughly 91% of magnet refining in China, plus thermal management limits above 400 kW and limited magnet recycling infrastructure. These raise cost and qualification risk rather than capping demand.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary weighting. Structured interviews and expert consultations were conducted across the traction-motor value chain, including magnet and electrical-steel suppliers, dedicated motor manufacturers, integrated e-axle and power-electronics producers, and global Tier-1 distributors. Interviewees included VP-level sourcing executives, heads of powertrain R&D, technical directors for thermal and electromagnetic design, and commercial operations leads at fleet-facing suppliers. This fieldwork calibrates capacity, pricing, and qualification timelines that public data cannot resolve.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Powertrain R&D & Technical Directors
40%
Procurement & Sourcing Leads
30%
Commercial & Fleet Operations
20%
Regulatory & Compliance Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Motor & Magnet Producers
40%
Integrated E-Axle & Power Electronics
30%
OEM Powertrain Groups
20%
Distributors & Fleet Suppliers
10%
Secondary Benchmarking & Public Trade Validation
Estimates are cross-validated against UN Comtrade and Eurostat motor and parts trade flows, US ITC tariff schedules, corporate 10-K and annual investor disclosures, patent filings covering axial-flux and switched-reluctance architectures, and technical standards from IEC and SAE. Regulatory baselines — EPA Phase 3, EU Regulation 2024/1610, and China GB 30510-2024 — anchor the demand-side forecast.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down allocation from macroeconomic vehicle-production forecasts and bottom-up modeling of manufacturer capacity, per-unit pricing, and end-use consumption by vehicle class. Divergences between the two approaches are reconciled at the segment level before aggregation.
 Electric Vehicle Ev Traction Motor Market