 Enterprise Mobility Management Emm Market
Enterprise Mobility Management (EMM) Market 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 185

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Enterprise Mobility Management Emm Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
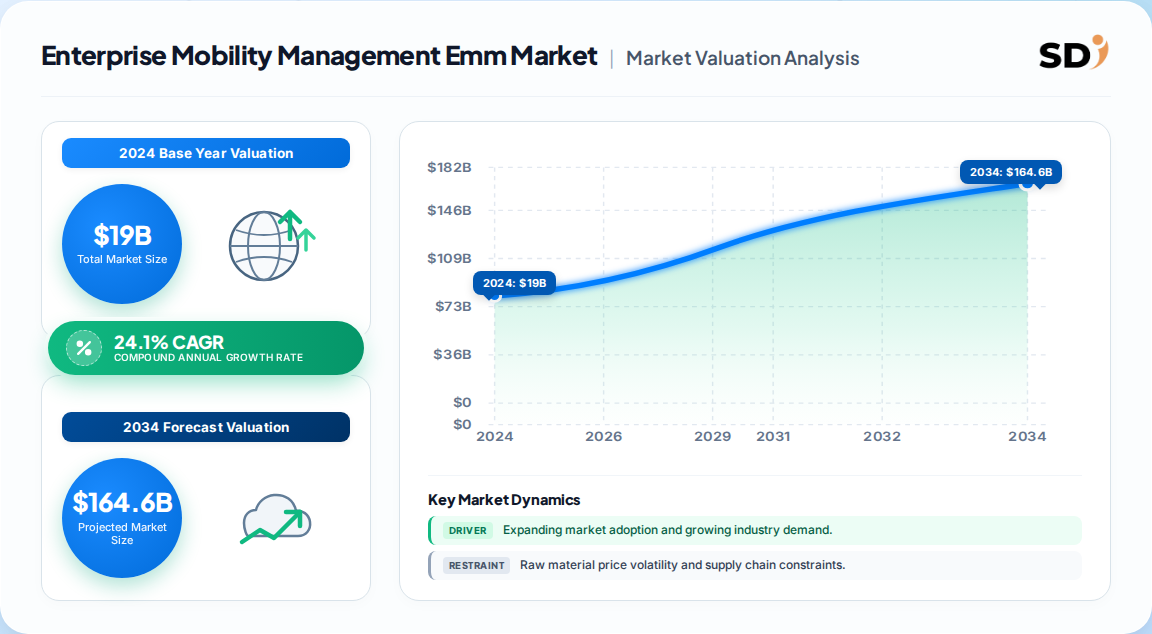
| 2024 | 19.00 B |
| 2025 | 23.60 B |
| 2026 | 28.90 B |
| 2027 | 35.90 B |
| 2028 | 44.50 B |
| 2029 | 55.20 B |
| 2030 | 69.10 B |

Enterprise Mobility Management (EMM) is the combined software, services, and policy framework organizations use to secure and administer corporate-owned and personally enabled mobile devices, applications, content, and access. It enforces device posture, application policy, and identity context — translating them into access decisions across MDM, MAM, MCM, and identity functions.
This analysis covers the global EMM market across solutions (MDM, MAM, MCM, IAM, UEM) and services (consulting, implementation, support, training), across cloud, on-premises, and hybrid deployment, in large and mid-sized enterprises. This analysis does not cover standalone consumer mobile security, carrier MDM bundles, or pure telecom expense management outside mobility policy.
Estimates range from USD 15.7 billion to USD 33.9 billion for the 2025 base year, with forecast horizons stretching to 2035 at CAGRs between 18.6% and 25.2%. The spread reflects definitional breadth, not disagreement about underlying demand.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 15.7 B | 2025 | 2035 (USD 129.4 B) | 24.5% | Broad: devices, apps, content, identity, expense, services | One published estimate |
| USD 19.0 B | 2024 | 2030 (USD 69.1 B) | 24.1% | Core EMM software + services | Competing analysis |
| USD 33.9 B | 2025 | 2031 (USD 94.5 B) | 18.6% | Includes UEM and adjacent endpoint governance | Competing analysis |
| USD 29.8 B | 2025 | 2030 (USD 92.3 B) | 25.2% | Solutions + services across nine verticals | Competing analysis |
Our analysis suggests the USD 19–30 billion band is the most defensible 2024–2025 range. The lower USD 15.7 billion figure under-weights services revenue; the higher USD 33.9 billion figure is credible only if UEM and identity spend are fully consolidated. For procurement planning, we recommend anchoring on roughly USD 20–30 billion today with a 20–24% CAGR — implying a market of USD 70–95 billion by 2030–2031.
Segmentation follows four primary axes — component, deployment, organization size, and vertical — with security management the fastest-advancing sub-segment inside solutions.
| Parent | Children |
|---|---|
| By Component | Solutions (MDM, MAM, MCM, IAM, UEM); Services (Consulting, Implementation, Support & Maintenance, Training) |
| By Deployment | Cloud-based, On-premises, Hybrid |
| By Organization Size | Large Enterprises, SMEs |
| By Vertical | BFSI, Healthcare & Life Sciences, IT & Telecom, Manufacturing, Retail & eCommerce, Government, Transportation & Logistics, Travel & Hospitality |
Software held over 63% of 2024 revenue, while services is the fastest-growing component as buyers shift from license purchase to managed outcomes. Cloud holds 56–58% and is compounding near 19%, but on-premises persists at roughly 22% CAGR because regulated buyers still prize control over sensitive data and compliance evidence. Healthcare is the fastest-growing vertical at ~19.8% CAGR, driven by HIPAA mandates for MFA and encryption.
North America leads the global EMM market with roughly 32–38% revenue share, anchored by mature breach-reporting regimes and premium security spending; Asia Pacific is the fastest-growing region at approximately 21–22% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.24% |
| Asia-Pacific | 0.28% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
The North America–Asia Pacific split is the single most important geographic insight for vendors. North America rewards depth — auditability, policy evidence, and zero-trust integration — and sustains premium pricing. Asia Pacific rewards scale and price elasticity, with mobile-first digital transformation programs driving rapid deployment. Our analysis suggests the winning vendor posture is a single control plane with regionally variable pricing and data residency, not a bifurcated product line.
BYOD expansion and rising mobile cyber threats are the strongest near-term drivers, adding an estimated 7.0 and 6.5 percentage points of CAGR impact respectively; high implementation cost is the principal brake.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| BYOD workforce expansion | Driver (+7.0%) | Strong | Extends addressable endpoints; raises value of containerization and selective wipe |
| Rising mobile cyber threats | Driver (+6.5%) | Strong | 1.2M+ enterprise phishing/malicious web attacks in Q3 2025 |
| Cloud migration | Driver (+6.0%) | Strong | Subscription delivery lowers infrastructure burden for distributed workforces |
| Data privacy regulation | Driver (+5.0%) | Strong | GDPR, NIS2, HIPAA, PCI DSS convert endpoint discipline into governance requirement |
| Implementation & upgrade cost | Restraint (−4.5%) | Moderate | Hidden compliance, certificate, and disposal spend exceeds year-one subscription |
| Legacy integration complexity | Restraint (−3.5%) | Moderate | Long-term drag in North America and Europe |
Net of these forces, the market still compounds in the low-to-mid twenties. The critical nuance: cost is not a demand problem, it is a packaging problem. Vendors that unbundle compliance automation from base licensing — as several already have — convert the top restraint into expansion revenue.
Microsoft (Intune/UEM Suite) leads with over 28.7% share; the top five players collectively hold roughly 44.6%, indicating a moderately concentrated market with room for specialists.
| Vendor | Position | Primary differentiation |
|---|---|---|
| Microsoft (Intune/UEM Suite) | Leader, >28.7% share | Bundled with identity and productivity estate; zero-trust adjacency |
| IBM (MaaS360) | Top five | Analytics-led, regulated-industry depth |
| Jamf | Top five | Apple ecosystem depth and field workflows |
| Omnissa (Workspace ONE) | Top five | Cross-platform virtualization and workspace integration |
| SOTI | Top five | Ruggedized and frontline device management |
The competitive moat is increasingly integration breadth rather than enrollment features. Our analysis suggests specialists retain viable positions where operating-system depth, field workflows, or regulated deployment requirements demand control that a bundled suite cannot deliver.
Selection criteria have shifted from device enrollment and remote wipe to conditional access, containerization, telemetry, and integration with endpoint and identity platforms. Buyers should weight API depth, data residency, and privacy-preserving BYOD boundaries above raw feature counts.
Switching costs are material and frequently underestimated. Migration involves policy re-authoring, certificate renewal, device re-enrollment, and workflow retraining; these costs often exceed the first-year subscription delta between competing platforms. Total cost of ownership remains opaque — surveys indicate roughly 31% of corporate phone managers cite cost clarity as the top selection barrier.
Regulatory compliance is now a procurement gate, not a checkbox. GDPR, NIS2, HIPAA, and PCI DSS each impose distinct evidence, auditability, and encryption-enforcement requirements. Buyers in these environments should demand policy evidence exports and documented data-movement boundaries before contracting. Note that full sub-segment forecasting and vendor-level pricing benchmarks sit outside this overview and require the complete report.
The balance of evidence favors a consolidated, integration-led market rather than a standalone EMM console business. The unit of protection has moved from the corporate handset to a context-sensitive combination of device, user, application, data, and network access — and buyers are reallocating budget accordingly. Our analysis suggests the USD 19–30 billion 2025 consensus band is sound, and the 20–24% growth trajectory is credible because it is underwritten by regulatory obligation, not discretionary IT spend.
The strongest counter-argument is that UEM absorption will compress the standalone EMM category, making today's forecasts overstated. That view has merit at the low end, but it misreads where value is accumulating: absorption expands the control plane rather than shrinking the spend, and specialized providers retain defensible ground in regulated and frontline deployments. The real risk is margin, not demand.
Actionable strategy:
What would change this conclusion: a sustained deceleration in cloud migration, or regulatory rollback in North America or Europe, would materially compress the forecast. Absent those signals, the 20–24% trajectory remains the defensible planning assumption.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 24.1% from 2020-2034 |
| Segmentation |
|
Estimates for 2025 range from USD 15.7 billion to USD 33.9 billion depending on scope. The most defensible band is roughly USD 19–30 billion, with forecasts reaching USD 70–95 billion by 2030–2031.
Published CAGRs range from 18.6% to 25.2%. The 20–24% range is the most credible planning assumption, underwritten by regulatory obligation and BYOD expansion rather than discretionary IT budgets.
North America leads with roughly 32–38% of global revenue, supported by mature breach-reporting regimes. Asia Pacific is the fastest-growing region at approximately 21–22% CAGR.
Microsoft Intune/UEM Suite leads with over 28.7% share. The top five — Microsoft, IBM MaaS360, Jamf, Omnissa Workspace ONE, and SOTI — collectively hold about 44.6% of the market.
The divergence is definitional. Broader estimates include unified endpoint management, identity, and expense management; narrower ones cover core MDM, MAM, and MCM software plus services. Scope, not demand, explains the spread.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the mobility value chain, including device and endpoint OEMs, EMM software vendors, managed security service providers, systems integrators, and enterprise IT buyers. Interviewees were drawn from 150+ organizations spanning North America, Europe, and Asia Pacific.
Decision-maker designations interviewed included Chief Information Security Officers, VP-level IT Infrastructure and Endpoint leaders, Heads of Mobile Engineering, and Procurement and Vendor Management Directors. Interviews probed deployment timelines, total cost of ownership, migration barriers, and regulatory evidence requirements.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CISOs & Security Leaders | 35% |
| IT Infrastructure & Endpoint VPs | 30% |
| Procurement & Vendor Management | 20% |
| Mobile Engineering Heads | 15% |
| Company Type | Representation (%) |
|---|---|
| EMM Software Vendors | 38% |
| Managed Security Service Providers | 27% |
| Systems Integrators | 20% |
| Enterprise IT Buyers | 15% |
Secondary validation draws on official multilateral and standards sources, including ITU mobile subscription statistics, NIST mobile-device and zero-trust guidance, ENISA and GDPR/NIS2 regulatory text, HIPAA and PCI DSS frameworks, national cybersecurity agency checklists, and corporate annual filings (10-K, SEC disclosures, investor presentations). Patent filings and vendor technical documentation were reviewed to map capability roadmaps.
Market sizing runs a simultaneous top-down and bottom-up approach. Top-down allocation uses enterprise IT security spend by vertical and region; bottom-up modeling aggregates vendor seat counts, average revenue per device, and end-use consumption by organization size. Divergences between the two are reconciled through segment-level elasticity checks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up seat and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, seat mapping & commercial filings | High |