 Us Veterinary Oncology Diagnostics Market
US Veterinary Oncology Diagnostics Market 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 207

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Veterinary Oncology Diagnostics Market
Amit Mardhekar
Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 980.0 M |
| 2026 | 1.060 B |
| 2027 | 1.140 B |
| 2028 | 1.230 B |
| 2029 | 1.330 B |
| 2030 | 1.440 B |
| 2031 | 1.550 B |

The US veterinary oncology diagnostics market covers laboratory tests, imaging, and molecular assays used to detect, stage, and monitor cancer in companion animals — principally dogs and cats — sold to veterinary hospitals, specialty practices, and reference laboratories. It excludes therapeutics, oncology drugs, and radiation equipment.
This report covers diagnostic testing only: blood tests, biopsy (tissue and liquid), urinalysis, endoscopy, genome testing, and imaging, segmented by animal type and end-use across US census regions. This analysis does not cover veterinary oncology therapeutics, chemotherapy protocols, radiotherapy capital equipment, or pet insurance products, which are addressed in adjacent coverage.
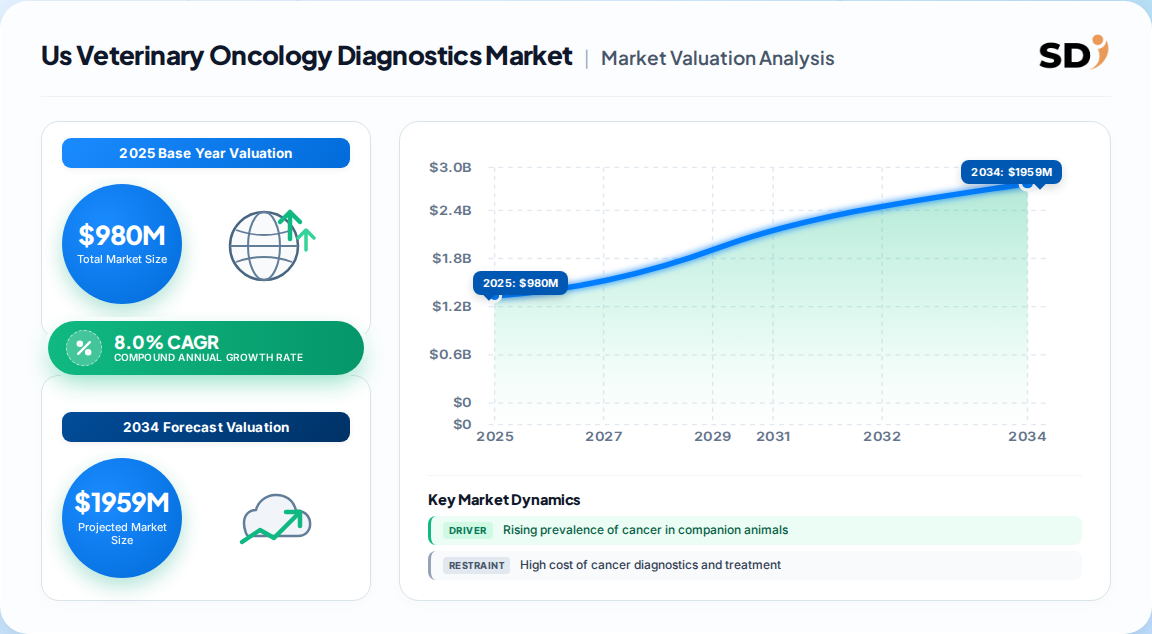
The most defensible estimate places the US market at approximately USD 980 Million in 2025, growing at roughly 8% annually toward USD 2.1 Billion by 2033. Higher global figures reflect the inclusion of therapeutics and imaging capital equipment, not a larger diagnostics opportunity.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 980 Million | 2023 | 2033 | 7.99% | US diagnostics only | One published estimate |
| USD 2.2 Billion | 2024 | 2030 | 8.4% | Global diagnostics, all geographies | A competing analysis |
| USD 2.0 Billion | 2025 | 2035 | 10.3% | Global oncology incl. therapeutics | A competing analysis |
Our analysis favors the USD 980 Million US-only figure because it isolates diagnostics from therapeutics, which inflate the two global series. The implied US share of roughly 40-45% of global diagnostics is consistent with US pet-owner spending patterns and specialist infrastructure density.
Segmentation follows four non-geographic axes: animal type, test type, end-use, and cancer type. Canine dominates on animal type, biopsy on test type, and hospitals and clinics on end-use, with genome testing the fastest-growing test category.
| Parent segment | Children |
|---|---|
| Animal type | Canine, Feline, Others |
| Test type | Blood tests, Biopsy, Urinalysis, Endoscopy, Genome testing, Imaging |
| End-use | Veterinary hospitals & clinics, Reference laboratories |
| Cancer type | Lymphoma, Mast cell tumor, Osteosarcoma, Melanoma, Mammary, Others |
The South leads the US market on absolute diagnostics revenue, driven by the largest pet population and a dense base of general practices. The Northeast and West follow, with the West showing the strongest per-clinic specialty penetration.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.22% |
| South | 0.34% |
| Midwest | 0.21% |
| West | 0.23% |
| Region | Estimated share |
|---|---|
| South | 34% |
| West | 23% |
| Northeast | 22% |
| Midwest | 21% |
Growth is driven primarily by rising canine cancer prevalence and rapid adoption of non-invasive liquid biopsy and molecular testing. Restraints are cost, uneven specialist access, and thin insurance penetration that caps owner willingness to pay for advanced workups.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising companion-animal cancer prevalence | Driver | High | 1 in 4 dogs affected; larger senior cohorts |
| Liquid biopsy and NGS adoption | Driver | High | Non-invasive, lower-cost screening |
| AI-assisted cytology and imaging | Driver | Medium | Extends specialist capacity |
| R&D funding and translational programs | Driver | Medium | New assays and validation |
| High cost of diagnostics and treatment | Restraint | High | Limits addressable owner base |
| Limited rural specialist access | Restraint | Medium | Slower adoption outside metros |
| Low pet-insurance penetration | Restraint | Medium | Price sensitivity at point of care |
Our analysis suggests the balance favors expansion: the cost restraint is structural but offset by falling assay prices, while prevalence and longevity effects compound demand well beyond 2033.
The US market is anchored by IDEXX and Zoetis, with Antech (Mars), PetDx, and Neogen supplying differentiated reference-lab, liquid-biopsy, and molecular capabilities. Consolidation across reference laboratories is the defining competitive dynamic.
| Vendor | Primary position | Differentiator |
|---|---|---|
| IDEXX Laboratories | Reference lab + in-clinic analyzer | Installed base and pathology network |
| Zoetis | Diagnostics + therapeutics adjacency | Portfolio breadth and oncology pipeline |
| Antech (Mars) | Reference lab | Mars ecosystem and scale |
| PetDx | Liquid biopsy (OncoK9) | Early-detection cfDNA screening |
| Neogen | Genomics and pathology | Molecular testing depth |
| Embark / VolitionRx | Niche molecular assays | Research-stage innovation |
Moats rest on installed analyzer bases, reference-lab logistics, and validated clinical evidence. Our analysis suggests liquid biopsy will commoditize over time, shifting advantage toward those owning the patient pathway from screening through staging.
Buyers should prioritize assay validation depth, turnaround time, and integration with existing practice-management systems. Sensitivity and specificity data published in peer-reviewed journals — not vendor marketing — should be the selection anchor.
Procurement risk concentrates in single-source reference-lab dependencies and in liquid biopsy assays that lack longitudinal validation. Switching costs rise sharply once a practice embeds a specific analyzer or lab workflow, so multi-year contracts should be negotiated with exit clauses.
Regulatory compliance is comparatively light for veterinary diagnostics, but state practice acts and laboratory certification requirements vary. Operators should verify CLIA-alignment where human-analog assays are used, and confirm data-handling compliance for AI-assisted pathology tools.
The balance of evidence favors a bullish view: the US market should roughly double by 2033, with the fastest value migration toward early-detection liquid biopsy and AI-assisted interpretation. The strongest counter-argument is that cost and insurance penetration cap the addressable base below headline prevalence — a real constraint, but one that erodes as assay prices fall.
Our judgment is that diagnostics will become the gateway to oncology revenue, not a standalone lab line. Vendors that own screening will influence staging, treatment selection, and monitoring, capturing disproportionate share of the patient pathway. Those that remain pure-play reference labs face margin compression.
What would change our conclusion: sustained evidence that insurance penetration stalls below 5% or that liquid biopsy sensitivity disappoints in real-world screening would materially temper the 2033 forecast.
This study applied a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including reference-laboratory operators, in-clinic diagnostics distributors, assay developers, veterinary specialty hospitals, and imaging-equipment suppliers. Decision-maker designations interviewed included VP of Diagnostics, Heads of R&D, Technical Directors, and Commercial Operations Leads.
Secondary validation drew on US ITC trade statistics, US Census Bureau import-export data, corporate 10-K and SEC filings, patent databases, and recognized veterinary and standards bodies including the AVMA, USDA APHIS, and ISO technical committees.
Market sizing triangulated a top-down macroeconomic allocation against bottom-up modeling of reference-lab volumes, in-clinic analyzer placements, and average revenue per test.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |

| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.0% from 2020-2034 |
| Segmentation |
|
The US veterinary oncology diagnostics market is approximately USD 980 Million in 2025, the largest country market globally. It is forecast to reach about USD 2.11 Billion by 2033 at an 8% CAGR.
Genome testing is the fastest-growing test type, expanding above 9% annually. Liquid biopsy and next-generation sequencing are driving adoption by enabling non-invasive early detection during routine wellness visits.
Canine diagnostics dominate, accounting for roughly 67% of US revenue. Higher cancer incidence in dogs and greater owner willingness to fund workups explain the segment's lead over feline testing.
IDEXX Laboratories and Zoetis lead, followed by Antech (Mars), PetDx, and Neogen. Differentiation rests on installed analyzer bases, reference-lab logistics, and validated liquid biopsy portfolios.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applied a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including reference-laboratory operators, in-clinic diagnostics distributors, assay developers, veterinary specialty hospitals, and imaging-equipment suppliers. Decision-maker designations interviewed included VP of Diagnostics, Heads of R&D, Technical Directors, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory Affairs Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Reference Laboratories | 35% |
| Assay & Reagent Developers | 30% |
| Specialty Veterinary Hospitals | 20% |
| Imaging & Equipment Suppliers | 15% |
Secondary validation drew on US ITC trade statistics, US Census Bureau import-export data, corporate 10-K and SEC filings, patent databases, and recognized veterinary and standards bodies including the AVMA, USDA APHIS, and ISO technical committees.
Market sizing triangulated a top-down macroeconomic allocation against bottom-up modeling of reference-lab volumes, in-clinic analyzer placements, and average revenue per test.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |