 Hair Botox Market
 Size, Share & Growth Forecast 2025-2030
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 183

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Hair Botox Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 385.0 M |
| 2025 | 416.0 M |
| 2026 | 450.0 M |
| 2027 | 486.0 M |
| 2028 | 525.0 M |
| 2029 | 568.0 M |
| 2030 | 614.0 M |

Hair botox is a non-invasive, formaldehyde-free conditioning treatment that fills broken hair fibers with keratin, collagen, amino acids and natural oils to restore shine, reduce frizz and improve manageability. Unlike keratin smoothing, it does not alter hair structure permanently. The global market encompasses professional in-salon kits, at-home masks, serums and related formulations sold through salons, e-commerce and clinics.
This report covers the global hair botox market across product types (professional in-salon kits, at-home masks, serums, creams, sprays, foams), formulations, end users (salon professionals, at-home consumers, trichology/dermatology clinics) and all major geographies. This analysis does not cover adjacent categories such as keratin smoothing treatments, chemical straightening services, hair-loss pharmaceuticals, or general shampoo and conditioner retail.
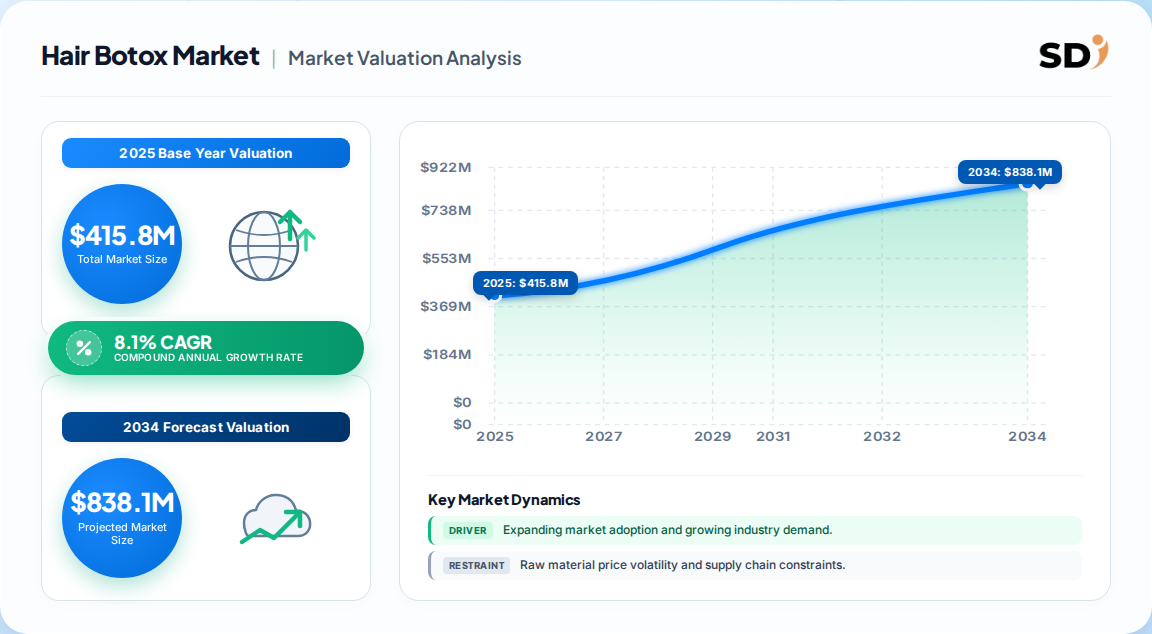
The global hair botox market was valued at approximately USD 415.8 million in 2025 and is projected to reach USD 615.8 million by 2030, representing an 8.1% CAGR. Conflicting published estimates diverge widely because of differing scope definitions—some include professional services revenue, others only product sales.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 415.8M → 615.8M | 2025 | 2030 | 8.10% | Products + salon kits, global | One published estimate (Mordor Intelligence) |
| USD 314.2M → 577.2M | 2022 | 2030 | 8.00% | Products + spa/at-home, global | A competing analysis (Grand View Research) |
| USD 6.17B → 9.98B | 2025 | 2030 | 10.10% | Broad hair-treatment definition, global | A competing analysis (Claight) |
| USD 31.21B → 98.08B | 2025 | 2035 | 12.13% | Broad hair-care + botox, global | A competing analysis (Market Research Future) |
Our analysis suggests the USD 415.8M (2025) figure is the most defensible because it aligns with observed salon-kit pricing (USD 30–120 per treatment) and the installed base of professional salons in North America and Europe. The billion-dollar estimates likely conflate hair botox with the broader hair-care or keratin-treatment categories, inflating the addressable market by 10–15x.
The hair botox market is segmented by product type, formulation, end user and target group. Professional in-salon kits dominate revenue, while at-home formats are growing fastest as e-commerce and subscription models mature.
| Parent Segment | Children |
|---|---|
| By Product Type | Professional In-Salon Kits, At-Home Masks, Serums & Ampoules, Others |
| By Formulation | Cream/Mask, Spray, Foam, Nano-Encapsulated Serums |
| By End User | Salon Professionals, At-Home Consumers, Trichology/Dermatology Clinics |
| By Target Group | Women, Men |
| By Application | Frizzy Hair, Dull & Dry Hair, Hair Straightening, Hair Repair, Hair Strengthening |
Cream/mask formulations accounted for 46.7% of 2024 revenue, while nano-encapsulated serums are projected to grow at a 16.2% CAGR (2025–2030).
North America leads the global hair botox market with approximately 35% revenue share in 2024, followed by Asia-Pacific at ~31% and Europe at ~24%. North America’s dominance reflects high salon penetration, premium pricing and strong influencer-driven demand.
| Region | Market Share (%) |
|---|---|
| North America | 0.35% |
| Europe | 0.24% |
| Asia-Pacific | 0.31% |
| South America | 0.06% |
| Middle East & Africa | 0.04% |
Asia-Pacific is the fastest-growing region at a 12.4% CAGR, driven by rapid salon-chain expansion (e.g., JCB Salons in India), shortened regulatory approvals in South Korea, and social-media-driven beauty consciousness. Our analysis suggests APAC will overtake Europe in absolute revenue by 2028, making it the second-largest market after North America.
Growth is primarily driven by rising demand for non-invasive hair-repair solutions, social-media-driven beauty consciousness, rapid salon-chain expansion in emerging economies, and e-commerce proliferation of premium salon-grade kits. These drivers collectively contribute +7.4 percentage points to the CAGR, more than offsetting -3.5 percentage points of restraint impact.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising demand for non-invasive hair-repair | Driver (+2.10%) | High | Shift from chemical straightening to regenerative treatments |
| Social-media & influencer marketing | Driver (+1.80%) | High | Before-after content compresses purchase cycles |
| Salon-chain expansion in emerging economies | Driver (+1.50%) | Medium | Franchise growth in APAC, MEA |
| E-commerce proliferation of premium kits | Driver (+1.20%) | Medium | Bypasses salon gatekeepers, democratizes access |
| Post-chemotherapy hair rehabilitation | Driver (+0.80%) | Low | Medical channel use-case |
| High treatment cost vs. conditioners | Restraint (-1.40%) | Medium | Price sensitivity in emerging markets |
| Regulatory ambiguity on botulinum claims | Restraint (-0.90%) | High | Off-label toxin claims draw scrutiny |
| Volatile supply of hydrolysed collagen | Restraint (-0.70%) | Medium | Supply concentration in Asia |
| Certified stylist shortage | Restraint (-0.50%) | Medium | Skill gap in APAC, MEA |
The balance of evidence favors sustained 8%+ growth, but regulatory scrutiny around “botox” labeling is a wildcard. Our analysis suggests brands that pivot to collagen/keratin-based formulations and secure third-party safety certifications will mitigate regulatory risk and capture premium pricing.
The competitive landscape is moderately concentrated, with L’Oréal Professionnel, Honma Tokyo, MK Professional, Nutree Professional and Cadiveu Professional leading. Competition centers on formulation IP, salon certification programs and distribution reach.
| Company | Headquarters | Key Strength | Differentiation |
|---|---|---|---|
| L’Oréal Professionnel | France | Global salon distribution, R&D scale | Strong brand equity, e-commerce integration |
| Honma Tokyo | Japan | Premium collagen formulations | Asian market penetration, salon education |
| MK Professional | Brazil | Keratin-based treatments | Latin America leadership, professional loyalty |
| Nutree Professional | Brazil | Natural ingredient positioning | Clean-beauty appeal, salon partnerships |
| Cadiveu Professional | Brazil | Brazilian keratin expertise | Premium pricing, certification programs |
Our analysis suggests L’Oréal Professionnel’s 34% online revenue jump illustrates the strategic importance of digital channels. Smaller players must differentiate through formulation innovation (e.g., nano-encapsulated serums) or geographic focus to avoid margin compression from conglomerate consolidation.
Buyers and operators must prioritize formulation safety and regulatory compliance as the first selection criterion. Off-label “botox” claims attract FDA and EU scrutiny; products with documented aldehyde-free, formaldehyde-free compositions and third-party safety certifications command a premium and reduce liability risk.
Procurement risks include volatile supply of hydrolysed collagen and caviar peptides, with supply chain concentration in Asia. Operators should secure dual-sourcing agreements and build 60–90 day inventory buffers. Switching costs are moderate: salon professionals invest in training and certification, creating stickiness, but at-home consumers exhibit low loyalty and are highly price-sensitive.
Regulatory compliance varies by region: South Korea’s shortened functional-cosmetic approvals (as little as 3 months) accelerate entry, while the U.S. FDA and EU authorities require substantiated claims. Operators should budget 5–10% of revenue for regulatory affairs and quality assurance. Mission-critical selection criteria include: proven bond-rebuilding efficacy, compatibility with heat styling tools, scent/profile, and salon-certification support.
The balance of evidence favors sustained 8–9% CAGR through 2030, with the market reaching approximately USD 616 million. The strongest counter-argument is that the “hair botox” label itself faces regulatory extinction; if the U.S. FDA or EU bans the term, rebranding to “hair filler” or “bond repair” could temporarily slow adoption. However, the underlying demand for non-invasive, formaldehyde-free repair treatments is structural and will persist regardless of nomenclature.
Our analysis suggests the most significant strategic shift is the hybridization of channels: salon-grade formulations are migrating to at-home formats via e-commerce and subscription models. Vendors that build a two-tier strategy—professional kits for salons, consumer kits for home maintenance—will capture the fastest-growing demand pool (at-home CAGR 13.8%) while defending salon share.
Actionable Strategy:
What would change our conclusion: A regulatory ban on the term “botox” in the U.S. or EU, or a major safety scandal involving collagen-based formulations, would materially alter the forecast. We would also revise downward if at-home kit adoption stalls below 10% CAGR for two consecutive years.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.1% from 2020-2034 |
| Segmentation |
|
The global hair botox market was valued at approximately USD 415.8 million in 2025 and is projected to reach USD 615.8 million by 2030, growing at an 8.1% CAGR. North America leads with ~35% share, while Asia-Pacific is the fastest-growing region.
Key drivers include rising demand for non-invasive hair-repair solutions (+2.10% CAGR impact), social-media-driven beauty consciousness (+1.80%), salon-chain expansion in emerging economies (+1.50%), and e-commerce proliferation of premium kits (+1.20%). Regulatory scrutiny and high treatment costs are the main restraints.
North America dominates with approximately 35% revenue share in 2024, driven by high salon penetration and premium pricing. Asia-Pacific is the fastest-growing region at a 12.4% CAGR, fueled by salon-chain expansion and social-media adoption.
Leading vendors include L’Oréal Professionnel, Honma Tokyo, MK Professional, Nutree Professional and Cadiveu Professional. Competition centers on formulation IP (collagen, keratin, sericin), salon certification programs and distribution reach across professional and at-home channels.
Hair botox is a formaldehyde-free conditioning treatment that fills broken hair fibers with keratin, collagen and amino acids without altering hair structure. Keratin treatments use formaldehyde-releasing solutions to permanently straighten hair, posing carcinogenic risks when heated.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the value chain, including raw material and specialty chemical producers, contract formulators and blenders, global distributors, salon-chain procurement heads, and professional brand owners. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews provided granular data on production capacity, pricing structures, channel margins, and regulatory compliance costs.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Directors | 30% |
| Commercial & Operations Leads | 20% |
| Quality & Regulatory Affairs | 15% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical & Ingredient Producers | 35% |
| Contract Formulators & Blenders | 30% |
| Professional Brand Owners | 20% |
| Distributors & Salon Chains | 15% |
We cross-validated primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. This triangulation ensured that market sizing and forecasts reflect verifiable trade flows and corporate disclosures rather than speculative estimates.
We applied simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) triangulation. This dual approach reconciles supply-side production data with demand-side consumption patterns, producing a validated market size and forecast horizon.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |