 Medical Supply Delivery Service Market
 Outlook 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 233

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Medical Supply Delivery Service Market
Amit Mardhekar
Research Analyst

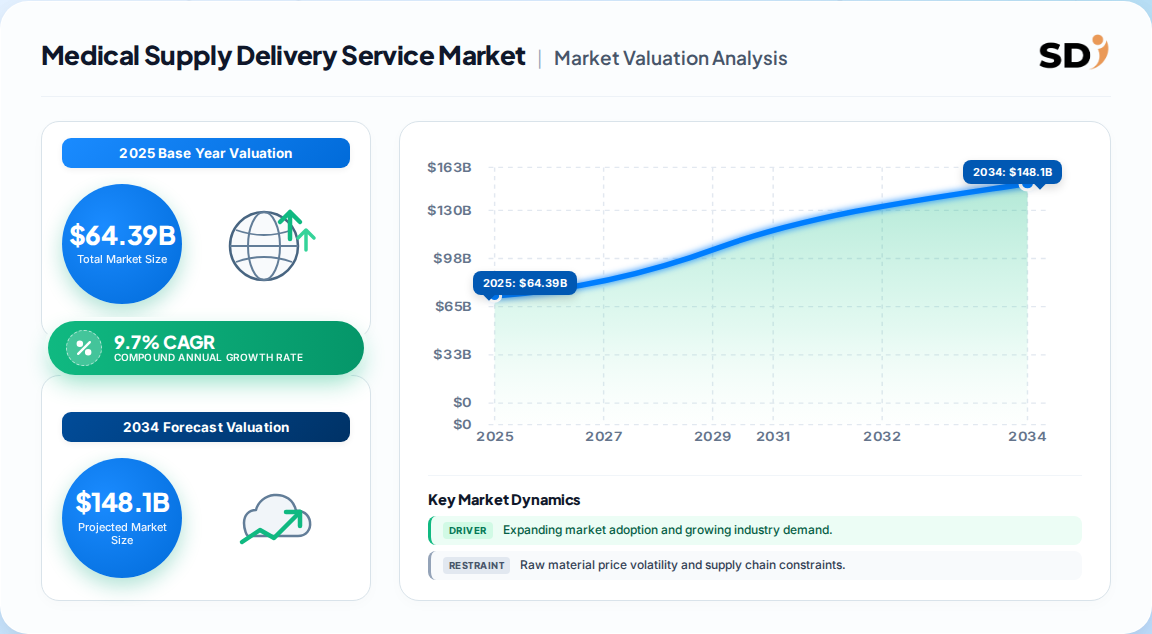
| Year | Market Size |
|---|---|
| 2025 | 64.39 B |
| 2026 | 70.64 B |
| 2027 | 77.49 B |
| 2028 | 85.01 B |
| 2029 | 93.26 B |
| 2030 | 102.3 B |
| 2031 | 112.2 B |

The Medical Supply Delivery Service Market covers contracted transport of medical supplies, pharmaceuticals, lab specimens, blood components and emergency medical items between manufacturers, distributors, pharmacies, laboratories, hospitals and patients. It includes courier and drone modes, scheduled and STAT delivery, and value-added services such as temperature control, chain-of-custody tracking and compliance documentation.
This analysis covers courier and drone delivery of medical supplies, drug supplies, laboratory specimens and reports, and emergency medical services across hospital, clinic, laboratory, pharmacy and patient end uses globally. It includes scheduled, express, STAT and temperature-controlled delivery formats. This analysis does not cover wholesale pharmaceutical distribution, retail pharmacy sales, medical device manufacturing, or general non-medical parcel logistics.
Published estimates diverge meaningfully on base-year value and growth, largely because analysts draw the category boundary differently on drone delivery, home-care logistics and lab-specimen transport. The table below reconciles the competing figures and their defining assumptions.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 62.1 Billion | 2022 | 2030 | 7.5% | Supplies, lab specimens, drugs, emergency; courier + drone | One published estimate |
| USD 52.4 Billion | 2022 | 2033 | 10.7% | Same application set; narrower base definition | A competing analysis |
| USD 64.39 Billion | 2025 | 2035 | 9.70% | Courier and drone; drug, medical, lab, emergency | A third published estimate |
| USD 76.48 Billion | 2026 | 2033 | 8.5% | Adds hospital equipment and blood-bank end uses | A fourth published estimate |
Our analysis suggests the 2025 base of roughly USD 64 Billion is the most defensible anchor, because it sits between the narrower 2022 figure and the broader 2026 figure after adjusting for two to three years of growth. The 10.7% CAGR appears to reflect a low starting base rather than a faster underlying market; on a common definition, growth converges near 8.5–9.7%. Buyers should insist on a stated definition before comparing any forecast.
Segmentation matters because growth rates differ sharply by mode and end use, and a vendor's addressable revenue depends on which cells it can credibly serve.
| Parent segment | Children | Note |
|---|---|---|
| By Application | Medical supplies, Pharmaceutical supplies, Lab specimens & reports, Emergency services, Others | Pharmaceutical supplies lead at ~31% of 2026 revenue |
| By Mode of Service | Courier delivery, Drone delivery | Courier holds ~91% share |
| By Delivery Type | Scheduled, Express/urgent, STAT, Others | Scheduled leads at ~38% |
| By End Use | Hospitals & clinics, Diagnostic laboratories, Pharmacies, Blood banks, Patients, Government agencies | Hospitals dominate; patients fastest-growing |
North America leads with roughly 36–43% of global revenue, supported by dense road networks, mature healthcare logistics contracting and payer willingness to fund same-day and STAT delivery.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.24% |
| Asia-Pacific | 0.28% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
Asia Pacific is the structural growth engine, with digitization, medical tourism and drone pilots in India, Malawi-linked programs and Eastern African corridors demonstrating viable unit economics in low-density geographies. Europe sits mid-range, with pooled stockpiling and rescEU-style coordination creating institutional demand but fragmented national courier contracting.
Growth is driven by time-critical clinical need and logistics modernization, while restraint comes from cost sensitivity, fragmented regulation and thin drone economics outside subsidized corridors.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising surgical and transplant volumes | Driver | Strong | Increases specimen, blood and device movements |
| Chronic disease and aging populations | Driver | Strong | Sustains recurring pharmaceutical and home-care deliveries |
| Drone and AI route optimization | Driver | Moderate | Cuts turnaround time and per-delivery cost |
| Strategic stockpiling and pandemic preparedness | Driver | Moderate | Creates institutional contract demand |
| Temperature-control and compliance costs | Restraint | Strong | Raises operating cost and capital intensity |
| Fragmented cross-border regulation | Restraint | Moderate | Slows network scale-up |
| Courier labor availability and wage inflation | Restraint | Moderate | Compresses margins in dense urban markets |
Our analysis suggests demand-side drivers are structurally stronger than restraints over the decade, but the profit pool will not grow evenly. Compliance-heavy, temperature-controlled segments reward scale, while commodity same-day courier work faces wage and price pressure. The OECD's pandemic-preparedness work reinforces this: stockpiling creates short-term buffer demand, but stockpiles are explicitly a finite first-layer response, not a recurring logistics substitute.
Competition splits between global integrators with network density and specialist medical couriers with clinical compliance depth; drone operators remain partners rather than scale competitors.
| Company | Category | Core strength | Strategic position |
|---|---|---|---|
| DHL International | Global integrator | Cold chain and healthcare logistics | Broadest compliant network |
| UPS | Global integrator | Temperature-controlled healthcare units | Strong US and cross-border |
| FedEx | Global integrator | Express network and tracking | Speed-led differentiation |
| Agility Public Warehousing | Logistics and distribution | Emerging-market reach | Regional depth |
| ModivCare Solutions | Specialist medical courier | Non-emergency medical transport | Payer-linked contracts |
| CEVA Logistics | Contract logistics | Healthcare vertical integration | Contract-led growth |
| Matternet, Zipline, Swoop Aero, Flirtey | Drone delivery | Beyond-visual-line-of-sight capability | Niche and partnership-led |
Differentiation rests on chain-of-custody integrity, temperature validation, HIPAA-compliant handling and software integration with electronic health records. Our analysis suggests integrators will win large hospital-network contracts, while specialists defend margin through regulatory depth and payer relationships.
Selection should be weighted toward validated cold-chain capability, documented chain-of-custody, real-time tracking that integrates with clinical systems, and proven STAT response times under surge conditions. Procurement risk concentrates in single-vendor dependence for time-critical routes and in the gap between promised and measured on-time performance. Switching costs are moderate for scheduled courier work but high once tracking, compliance documentation and EHR integration are embedded in hospital workflows. Regulatory exposure varies by jurisdiction; buyers should confirm handling credentials for biological specimens, controlled drugs and blood components, and verify business-continuity coverage for weather, labor action and supply-chain disruption. Notably, a 2024 patient survey cited in trade coverage found 38% of chronic-care patients experienced at least one delivery delay or error in six months, with nearly half causing treatment interruption — a service-quality gap that buyers should price into contract terms.
The balance of evidence favors a market growing near 9% through the mid-2030s, anchored on roughly USD 64 Billion in 2025, but the more important signal is internal mix shift. Courier delivery will retain dominant share, yet the fastest incremental value accrues to operators who pair courier fleets with tracking software, temperature assurance and drone capability in low-density or congested corridors. The strongest counter-argument is that drone economics remain unproven at scale and that courier wage inflation plus regulatory fragmentation could suppress margins faster than volume grows — a scenario that would validate the lower, 7.5% end of the published range.
Our judgment is that consolidation favors integrated platforms with compliance depth, and that specialist couriers without software differentiation face systematic margin compression. Investors should weight exposure toward vendors with contracted hospital-network revenue and validated cold chain rather than speculative drone pure-plays. Operators should treat real-time visibility and EHR integration as table stakes, not differentiators.
Actionable strategy:
Evidence that would change this conclusion: sustained sub-7% courier volume growth, broad drone authorization with materially lower per-delivery cost, or a sharp rise in regulatory compliance costs that erodes specialist viability.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.7% from 2020-2034 |
| Segmentation |
|
The global market was valued at approximately USD 64.39 Billion in 2025 and is projected to reach about USD 162.51 Billion by 2035, expanding at a compound annual growth rate of 9.70% over the forecast period.
Courier delivery holds roughly 91% of service-mode revenue, reflecting established urban networks, real-time tracking and proven reliability. Drone delivery is the fastest-evolving niche but remains a small share, concentrated in remote and low-density corridors.
North America currently leads with approximately 36–43% of global revenue on advanced healthcare infrastructure. Asia Pacific is the fastest-growing region, driven by healthcare facility expansion, digitization and government-backed drone delivery pilots.
Rising surgical and transplant volumes, aging populations with chronic conditions, demand for faster specimen turnaround and adoption of AI-enabled route optimization and tracking all support sustained growth across the forecast period.
Major players include DHL, UPS, FedEx, Agility, ModivCare, CEVA Logistics and specialist drone operators such as Matternet, Zipline, Swoop Aero and Flirtey, competing on network density, compliance and technology integration.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including medical courier fleet operators, third-party logistics integrators, cold-chain packaging specialists, drone delivery platform providers and hospital procurement groups. Decision-maker designations interviewed included VP of Supply Chain, Director of Laboratory Operations, Head of Clinical Logistics and Pharmacy Operations Leads, ensuring both commercial and clinical perspectives informed demand assumptions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Supply Chain & Procurement Leads | 38% |
| Laboratory & Clinical Operations | 32% |
| Regulatory & Compliance Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| Courier & Fleet Operators | 40% |
| Logistics Integrators | 30% |
| Cold-Chain & Packaging Specialists | 18% |
| Drone Platform Providers | 12% |
Estimates were cross-checked against official multilateral and standards sources, including UN Comtrade and WTO trade statistics, US ITC and Eurostat classifications, corporate 10-K filings and investor presentations from listed logistics providers, patent databases covering cold-chain and drone delivery technology, and non-profit technical standards bodies governing specimen transport and temperature assurance.
We run simultaneous top-down allocation from macroeconomic healthcare expenditure and logistics spend, and bottom-up modeling of courier fleet capacity, per-delivery pricing, route density and end-use consumption across hospitals, laboratories, pharmacies and patients. Divergences between the two approaches are reconciled against reported revenue of major vendors.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up capacity and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |