Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Medical X Ray Generator Market Outlook 2025
Medical X Ray Generator Market
Medical X Ray Generator Market Outlook 2025
Medical X Ray Generator Market by Type (Stationary Generators, Portable Generators), by End User (Hospitals, Diagnostic Imaging Centres, Clinics, Industrial, Others), by Application (Radiography, Fluoroscopy, Mammography, Computed Tomography), by Technology (Digital Radiography, Computed Radiography), by Component (X-Ray Tube, Control Panel, Power Supply, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 185
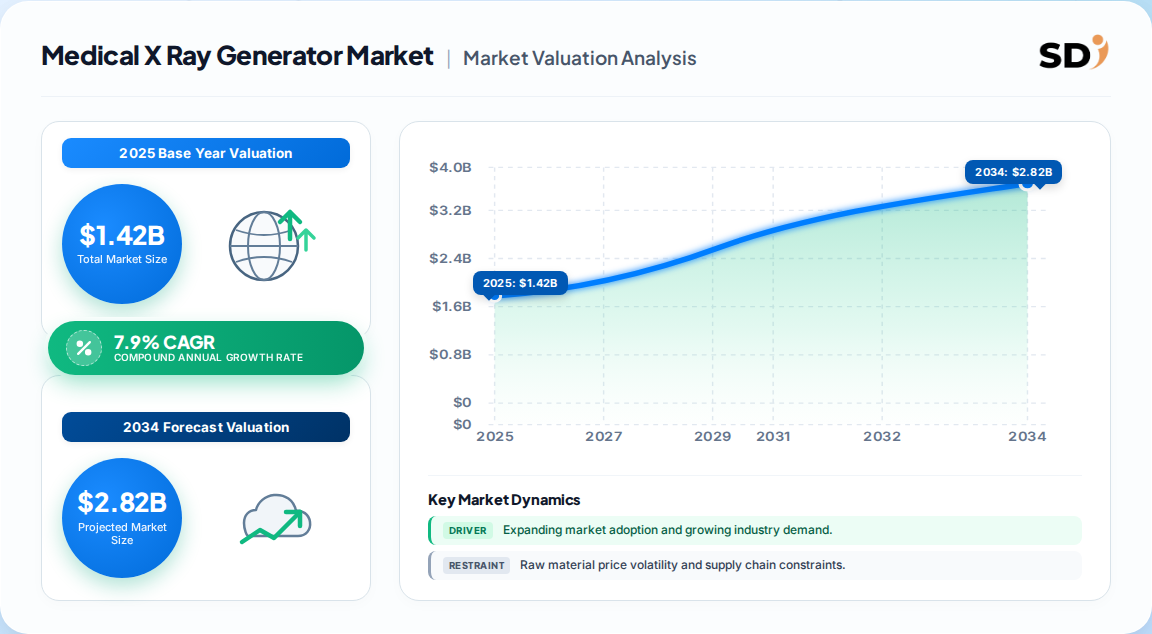
Size & base: 1.42 Billion in 2025 for the global Medical X Ray Generator Market; next forecast year reaches 1.53 Billion.
Forecast horizon: 2.58 Billion by 2033, a 7.9% fixed CAGR over 2026–2033.
Leading segment: Medical end-use holds the dominant share, with stationary generators commanding the majority of deployments.
Leading regions: North America leads at ~41% share; Asia Pacific is the fastest-growing region at ~9.6% CAGR.
Key players: Spellman High Voltage, Siemens Healthineers, GE Healthcare, Teledyne ICM and Philips Healthcare dominate a highly concentrated vendor field.
Why this matters for decision-makers: Vendors must pivot to high-voltage, dose-optimized and AI-integrated generator platforms to avoid margin compression as digital radiography commoditizes.
Medical X Ray Generator Market Size (In Billion)
2.5B
2.0B
1.5B
1.0B
500.0M
0
1.420 B
2025
1.530 B
2026
1.650 B
2027
1.780 B
2028
1.920 B
2029
2.070 B
2030
2.240 B
2031
Medical X Ray Generator Market Size (In Billion)
Year
Market Size
2025
1.420 B
2026
1.530 B
2027
1.650 B
2028
1.780 B
2029
1.920 B
2030
2.070 B
2031
2.240 B
What is the Medical X Ray Generator Market?
The Medical X Ray Generator Market covers the design, manufacture and sale of high-voltage power supply units that drive X-ray tubes in diagnostic imaging systems. Generators convert low-voltage input into stable high-voltage waveforms, governing image quality, radiation dose and system uptime across radiography, fluoroscopy, mammography and CT.
Scope: what this report covers and excludes
This report covers stationary and portable medical X-ray generators sold to hospitals, diagnostic imaging centres, clinics and OEM system integrators across North America, Europe, Asia Pacific, Latin America and Middle East & Africa. This analysis does not cover X-ray tubes, detectors, imaging software, industrial non-destructive testing generators or security screening generators.
How big is the market for Medical X Ray Generator Market?
The most defensible base for the global Medical X Ray Generator Market is approximately 1.42 Billion in 2025, with a 7.9% CAGR to 2.58 Billion by 2033. Competing published estimates diverge sharply because of scope differences, as shown below.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
1.42 Billion
2025
2033
7.9%
X-ray generators, medical + industrial
One published estimate
8.4 Billion
2024
2034
3.3%
Full X-ray systems market
A competing analysis
~0.9 Billion
2021
2033
8.9%
Industrial X-ray generators
Another published source
The 8.4 Billion figure covers complete X-ray systems, including tubes and detectors, and is therefore not comparable. The 1.42 Billion base is the most defensible because it isolates generator hardware, which grows faster than complete systems as digital upgrades replace aging power supplies.
How is the market segmented?
The market segments primarily by generator type, end user and application, with portable and stationary configurations driving distinct procurement economics. Medical use dominates revenue, but industrial inspection is the fastest-growing niche.
Stationary generators anchor hospital imaging suites and command premium pricing due to higher power output and tighter waveform control. Portable generators are the fastest-growing sub-segment, driven by emergency, field and point-of-care demand.
Which region leads in Medical X Ray Generator Market?
North America leads with approximately 41% of global revenue, supported by advanced healthcare infrastructure, high chronic disease prevalence and early digital radiography adoption. Asia Pacific is the fastest-growing region at roughly 9.6% CAGR.
Medical X Ray Generator Market Regional Market Share
Loading chart...
Medical X Ray Generator Market Regional Market Share
Region
Market Share (%)
North America
0.41%
Europe
0.27%
Asia-Pacific
0.24%
South America
0.04%
Middle East & Africa
0.04%
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Region
Share
North America
41%
Europe
27%
Asia-Pacific
24%
South America
4%
Middle East & Africa
4%
Our analysis suggests Asia Pacific's growth premium reflects healthcare infrastructure investment and portable X-ray penetration into underserved areas, not yet a shift in installed base share.
What is driving growth — and what is holding it back?
Growth is driven by chronic disease prevalence, CT and digital radiography expansion, and portable imaging adoption, while stringent regulatory validation and high switching costs restrain replacement cycles.
Factor
Direction
Evidence strength
Mechanism
Rising chronic disease & geriatric population
Driver
High
Increases diagnostic imaging volume and replacement demand
Digital radiography transition
Driver
High
Requires generator upgrades for dose and image quality
Portable/point-of-care imaging
Driver
Medium
Expands addressable sites beyond hospitals
AI-assisted detection integration
Driver
Medium
Demands stable, high-fidelity generator output
Stringent regulations & validation
Restraint
High
Lengthens certification cycles and raises compliance cost
High system switching costs
Restraint
Medium
Slows replacement of legacy generators
The balance favours growth. Regulatory friction delays but rarely cancels procurement because compliance is non-discretionary. The stronger second-order effect is that dose-optimization regulation favors premium generators, concentrating value among fewer qualified vendors.
Who are the leading vendors?
The market is highly concentrated, with Spellman High Voltage, Siemens Healthineers, GE Healthcare, Teledyne ICM and Philips Healthcare holding prominent shares through vertical integration and OEM relationships.
Vendor
Positioning
Key strength
Spellman High Voltage Electronics
High-voltage specialist
Monoblock and OEM power supplies
Siemens Healthineers
Integrated systems
CT and angiography generator integration
GE Healthcare
Integrated systems
AI-enabled imaging and service network
Teledyne ICM
Portable/industrial
Rugged portable generator design
Philips Healthcare
Integrated systems
DRF and interventional systems
Differentiation rests on waveform stability, dose precision and integration with imaging chains. Our analysis suggests OEM lock-in and service contracts are the deepest moats, making standalone generator vendors dependent on system-integrator partnerships.
What do buyers and operators need to know?
Buyers should prioritize waveform stability, dose reproducibility and service network depth over headline power ratings, because generator downtime halts entire imaging suites. Procurement risk concentrates in single-source OEM contracts and long validation cycles for regulated markets.
Switching costs are material: generators are validated with specific tubes and detectors, so replacement often triggers re-certification. Operators should verify IEC 60601 compliance and ALARA dose-management features, and negotiate uptime SLAs. Multi-vendor sourcing reduces supply risk but complicates service accountability.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours a growth-oriented position: the generator market grows faster than complete X-ray systems because digital and dose-optimization upgrades force power-supply replacement independent of new scanner purchases. The strongest counter-argument is that integrated OEMs could internalize generator production, squeezing standalone vendors; however, specialist high-voltage suppliers retain cost and design advantages.
Vendors: Prioritize high-voltage, dose-optimized platforms with AI-ready interfaces to capture premium hospital upgrades.
Investors: Favour component specialists with OEM contracts over fully integrated system players, where generator value is bundled.
Operators: Lock multi-year service SLAs and validate IEC compliance before committing to single-source procurement.
Evidence that would change this conclusion: a sustained decline in digital radiography replacement rates or regulatory harmonization that lowers re-certification costs, which would weaken the upgrade-driven demand thesis.
While this overview frames the strategic landscape, precise sub-segment forecasting and country-level vendor share require the full report's modelled datasets.
Medical X Ray Generator Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Medical X Ray Generator Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.9% from 2020-2034
Segmentation
By Type
Stationary Generators
Portable Generators
By End User
Hospitals
Diagnostic Imaging Centres
Clinics
Industrial
Others
By Application
Radiography
Fluoroscopy
Mammography
Computed Tomography
By Technology
Digital Radiography
Computed Radiography
By Component
X-Ray Tube
Control Panel
Power Supply
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Stationary Generators
5.1.2. Portable Generators
5.2. Market Analysis, Insights and Forecast - by End User
5.2.1. Hospitals
5.2.2. Diagnostic Imaging Centres
5.2.3. Clinics
5.2.4. Industrial
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Radiography
5.3.2. Fluoroscopy
5.3.3. Mammography
5.3.4. Computed Tomography
5.4. Market Analysis, Insights and Forecast - by Technology
5.4.1. Digital Radiography
5.4.2. Computed Radiography
5.5. Market Analysis, Insights and Forecast - by Component
5.5.1. X-Ray Tube
5.5.2. Control Panel
5.5.3. Power Supply
5.5.4. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Stationary Generators
6.1.2. Portable Generators
6.2. Market Analysis, Insights and Forecast - by End User
6.2.1. Hospitals
6.2.2. Diagnostic Imaging Centres
6.2.3. Clinics
6.2.4. Industrial
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Radiography
6.3.2. Fluoroscopy
6.3.3. Mammography
6.3.4. Computed Tomography
6.4. Market Analysis, Insights and Forecast - by Technology
6.4.1. Digital Radiography
6.4.2. Computed Radiography
6.5. Market Analysis, Insights and Forecast - by Component
6.5.1. X-Ray Tube
6.5.2. Control Panel
6.5.3. Power Supply
6.5.4. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Stationary Generators
7.1.2. Portable Generators
7.2. Market Analysis, Insights and Forecast - by End User
7.2.1. Hospitals
7.2.2. Diagnostic Imaging Centres
7.2.3. Clinics
7.2.4. Industrial
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Radiography
7.3.2. Fluoroscopy
7.3.3. Mammography
7.3.4. Computed Tomography
7.4. Market Analysis, Insights and Forecast - by Technology
7.4.1. Digital Radiography
7.4.2. Computed Radiography
7.5. Market Analysis, Insights and Forecast - by Component
7.5.1. X-Ray Tube
7.5.2. Control Panel
7.5.3. Power Supply
7.5.4. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Stationary Generators
8.1.2. Portable Generators
8.2. Market Analysis, Insights and Forecast - by End User
8.2.1. Hospitals
8.2.2. Diagnostic Imaging Centres
8.2.3. Clinics
8.2.4. Industrial
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Radiography
8.3.2. Fluoroscopy
8.3.3. Mammography
8.3.4. Computed Tomography
8.4. Market Analysis, Insights and Forecast - by Technology
8.4.1. Digital Radiography
8.4.2. Computed Radiography
8.5. Market Analysis, Insights and Forecast - by Component
8.5.1. X-Ray Tube
8.5.2. Control Panel
8.5.3. Power Supply
8.5.4. Others
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Stationary Generators
9.1.2. Portable Generators
9.2. Market Analysis, Insights and Forecast - by End User
9.2.1. Hospitals
9.2.2. Diagnostic Imaging Centres
9.2.3. Clinics
9.2.4. Industrial
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Radiography
9.3.2. Fluoroscopy
9.3.3. Mammography
9.3.4. Computed Tomography
9.4. Market Analysis, Insights and Forecast - by Technology
9.4.1. Digital Radiography
9.4.2. Computed Radiography
9.5. Market Analysis, Insights and Forecast - by Component
9.5.1. X-Ray Tube
9.5.2. Control Panel
9.5.3. Power Supply
9.5.4. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Stationary Generators
10.1.2. Portable Generators
10.2. Market Analysis, Insights and Forecast - by End User
10.2.1. Hospitals
10.2.2. Diagnostic Imaging Centres
10.2.3. Clinics
10.2.4. Industrial
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Radiography
10.3.2. Fluoroscopy
10.3.3. Mammography
10.3.4. Computed Tomography
10.4. Market Analysis, Insights and Forecast - by Technology
10.4.1. Digital Radiography
10.4.2. Computed Radiography
10.5. Market Analysis, Insights and Forecast - by Component
10.5.1. X-Ray Tube
10.5.2. Control Panel
10.5.3. Power Supply
10.5.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Medical X Ray Generator Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Medical X Ray Generator Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Medical X Ray Generator Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Medical X Ray Generator Market Revenue (Billion), by End User 2026 & 2034
Figure 5: North America Medical X Ray Generator Market Revenue Share (%), by End User 2026 & 2034
Figure 6: North America Medical X Ray Generator Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Medical X Ray Generator Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Medical X Ray Generator Market Revenue (Billion), by Technology 2026 & 2034
Figure 9: North America Medical X Ray Generator Market Revenue Share (%), by Technology 2026 & 2034
Figure 10: North America Medical X Ray Generator Market Revenue (Billion), by Component 2026 & 2034
Figure 11: North America Medical X Ray Generator Market Revenue Share (%), by Component 2026 & 2034
Figure 12: North America Medical X Ray Generator Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Medical X Ray Generator Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Medical X Ray Generator Market Revenue (Billion), by Type 2026 & 2034
Figure 15: Europe Medical X Ray Generator Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Medical X Ray Generator Market Revenue (Billion), by End User 2026 & 2034
List of Tables
Table 1: Medical X Ray Generator Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Medical X Ray Generator Market Revenue Billion Forecast, by End User 2020 & 2034
Table 3: Medical X Ray Generator Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Medical X Ray Generator Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 5: Medical X Ray Generator Market Revenue Billion Forecast, by Component 2020 & 2034
Table 6: Medical X Ray Generator Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Medical X Ray Generator Market Revenue Billion Forecast, by Type 2020 & 2034
Table 8: North America Medical X Ray Generator Market Revenue Billion Forecast, by End User 2020 & 2034
Table 9: North America Medical X Ray Generator Market Revenue Billion Forecast, by Application 2020 & 2034
Table 10: North America Medical X Ray Generator Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 11: North America Medical X Ray Generator Market Revenue Billion Forecast, by Component 2020 & 2034
Table 12: North America Medical X Ray Generator Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Medical X Ray Generator Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Medical X Ray Generator Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Medical X Ray Generator Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Medical X Ray Generator Market Revenue Billion Forecast, by Type 2020 & 2034
Frequently Asked Questions
1. How big is the Medical X Ray Generator Market?
The global market was valued at approximately 1.42 Billion in 2025 and is projected to reach 2.58 Billion by 2033, growing at a 7.9% CAGR over the forecast period.
2. Which region leads the Medical X Ray Generator Market?
North America leads with roughly 41% of global revenue, driven by advanced healthcare infrastructure and early digital radiography adoption. Asia Pacific is the fastest-growing region at about 9.6% CAGR.
3. What is the fastest-growing segment?
Portable generators are the fastest-growing type segment, driven by emergency, field and point-of-care imaging demand. Medical end-use remains the dominant revenue contributor across all regions.
4. Who are the leading vendors?
Spellman High Voltage Electronics, Siemens Healthineers, GE Healthcare, Teledyne ICM and Philips Healthcare are the major players in a highly concentrated competitive landscape.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conduct in-depth interviews with stakeholders across the value chain, including high-voltage component suppliers, specialized generator producers, contract manufacturers and global distributors. Decision-makers interviewed include VP-level Sourcing executives, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring coverage of procurement, engineering and go-to-market perspectives.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement
35%
Heads of R&D
30%
Technical Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
High-Voltage Component Suppliers
40%
Specialized Generator Producers
30%
Contract Manufacturers
15%
Global Distributors
15%
Secondary Benchmarking & Public Trade Validation
We validate findings against official multilateral trade and standards databases, including UN Comtrade, WTO, US ITC and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases and recognized technical standards bodies. This anchoring ensures every estimate reconciles with observable commercial and regulatory reality.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down and bottom-up models. Top-down allocation uses macroeconomic healthcare expenditure and imaging procedure volumes; bottom-up modeling uses manufacturer capacity, product pricing and end-use consumption. Divergences are reconciled through iterative triangulation rather than simple averaging.
 Medical X Ray Generator Market