Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Dental Fluoride Treatment Market Outlook 2025
Dental Fluoride Treatment Market
Dental Fluoride Treatment Market Outlook 2025
Dental Fluoride Treatment Market by Product (Topical, Systemic), by Treatment Mode (Professional-Use, Personal-Use, Prescription-Strength), by Application (Caries Prevention, Dental Erosion Prevention, Dentin Hypersensitivity Treatment), by End Use (Retail Pharmacies, Dental Clinics, Hospitals, Online Platforms), by Patient Demographics (Pediatric, Adults, Geriatric, Pregnant Women), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 272
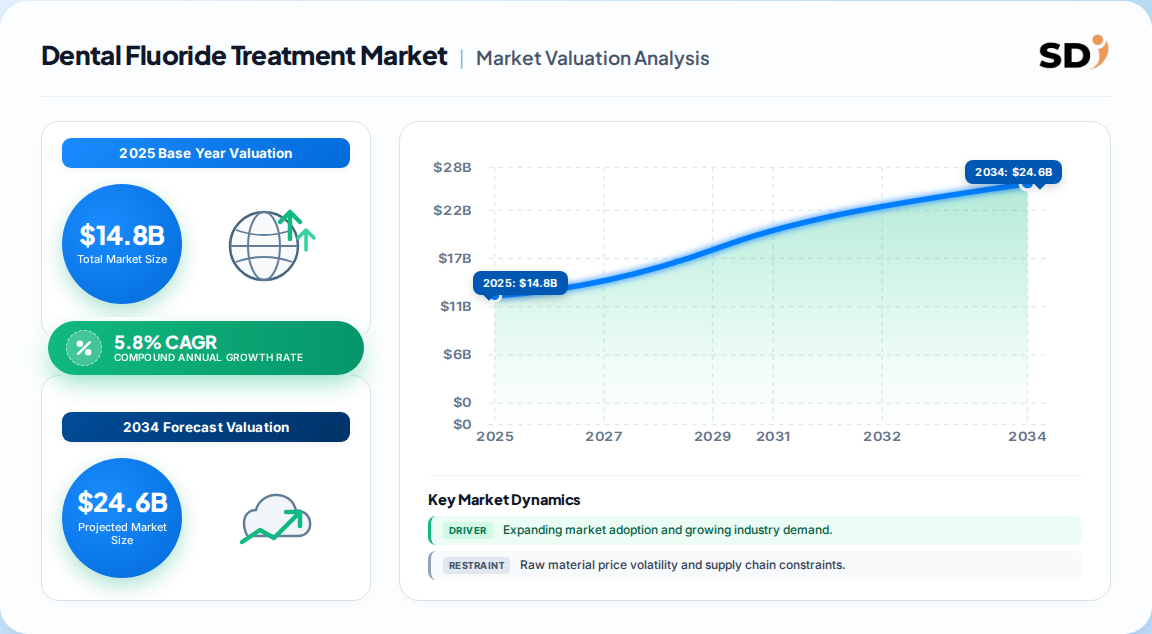
The global dental fluoride treatment market was valued at 14.8 Billion in 2025 and is projected to reach 23.1 Billion by 2033, growing at a 5.8% CAGR.
Topical fluoride dominates product demand, capturing 85.4% share in 2025, driven by at-home preventive care and professional varnish applications.
North America leads regional demand with 35.0% revenue share, while Asia Pacific is the fastest-growing region due to rising caries prevalence and expanding dental infrastructure.
Toothpaste remains the largest single product category, holding over 44% share, underpinned by daily oral hygiene routines and broad retail availability.
Key players include Colgate-Palmolive, 3M, Dentsply Sirona, Ultradent Products, and GC Corporation, competing on formulation innovation and professional channel access.
Why this matters for decision-makers: Vendors must prioritize professional-strength varnish and prescription-strength gel portfolios to capture margin-rich clinical demand, as OTC toothpaste commoditization accelerates.
Dental Fluoride Treatment Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
14.80 B
2025
15.60 B
2026
16.50 B
2027
17.50 B
2028
18.50 B
2029
19.60 B
2030
20.70 B
2031
Dental Fluoride Treatment Market Size (In Billion)
Year
Market Size
2025
14.80 B
2026
15.60 B
2027
16.50 B
2028
17.50 B
2029
18.50 B
2030
19.60 B
2031
20.70 B
What is the Dental Fluoride Treatment Market?
The dental fluoride treatment market encompasses products and services that deliver fluoride to prevent dental caries, remineralize enamel, and treat dentin hypersensitivity. It includes toothpastes, gels, varnishes, mouth rinses, and supplements distributed through retail, clinical, and public health channels.
Scope: what this report covers and excludes
This report covers fluoride-based preventive and therapeutic dental products across topical and systemic delivery modes, including professional-use varnishes and gels, personal-use toothpastes and rinses, and prescription-strength formulations. It analyzes revenue across retail pharmacies, dental clinics, hospitals, and online channels. This analysis does not cover dental implants, orthodontic devices, restorative materials, or non-fluoride remineralization agents such as hydroxyapatite or calcium phosphate products.
How big is the market for Dental Fluoride Treatment Market?
The global dental fluoride treatment market was valued at approximately 14.8 Billion in 2025, with estimates converging on a mid-single-digit CAGR through the early 2030s. However, published estimates diverge due to differing product scope definitions.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
23.8 Billion
2024
2034
5.7%
Broad scope including toothpaste, varnish, mouth rinse
One published estimate
23.1 Billion
2025
2033
5.8%
Topical and systemic fluoride products, professional and OTC
Our analysis suggests the 14.8 Billion base with 5.8% CAGR is most defensible because it aligns with WHO caries prevalence data and captures both clinical and retail channels. The 2.1 Billion estimate likely excludes OTC toothpaste, understating the true market. The divergence between 4.9% and 5.8% CAGRs reflects differing assumptions on professional varnish adoption in emerging markets.
How is the market segmented?
The market is segmented by product type, treatment mode, application, end use, and patient demographics. Topical products dominate, while personal-use formats lead treatment mode.
Parent Segment
Children Segments
By Product
Topical (Toothpaste, Varnish, Gel, Mouth Rinse), Systemic (Supplements, Water Fluoridation)
Topical fluoride captured 85.4% of 2025 revenue, with personal-use OTC formats accounting for 67.1%. Caries prevention remains the dominant application at 50.4%. Our analysis indicates that professional-use varnish is the fastest-growing sub-segment, driven by public health programs and school-based sealant initiatives.
Which region leads in Dental Fluoride Treatment Market?
North America leads the global dental fluoride treatment market with 35.0% revenue share in 2025, followed by Europe and Asia Pacific. Asia Pacific is the fastest-growing region, projected to gain share through 2033.
The U.S. dominates North America due to high fluoride varnish adoption in pediatric care and widespread water fluoridation. China and India are growth engines, with rising caries prevalence and expanding dental insurance coverage. Our analysis implies that Asia Pacific could overtake Europe in share by 2030 if current adoption rates persist.
What is driving growth — and what is holding it back?
The primary driver is the escalating global burden of dental caries, affecting 2.5 billion people, coupled with growing awareness of preventive oral care. Restraints include fluoride safety concerns and reimbursement limitations in some markets.
Factor
Direction
Evidence Strength
Mechanism
High caries prevalence
Driver
High
WHO reports 2.5 billion caries cases; fluoride proven to reduce decay by 25%
Public health programs
Driver
High
School-based varnish programs and water fluoridation expand access
Aging population
Driver
Medium
Geriatric patients require fluoride for root caries prevention
Fluoride-free consumer preference
Restraint
Medium
Growing segment seeks alternatives, especially in premium natural products
Reimbursement gaps
Restraint
Medium
Limited insurance coverage for adult fluoride treatments in some regions
Regulatory complexity
Restraint
Low
Varying approval pathways for prescription-strength products
The balance of evidence favors robust growth, as drivers are structural and quantifiable. However, the fluoride-free movement, while niche, could erode OTC toothpaste share in developed markets. Our analysis suggests that vendors should hedge by developing non-fluoride remineralization alternatives for premium segments while maintaining fluoride portfolios for clinical channels.
Who are the leading vendors?
The market is moderately concentrated, with Colgate-Palmolive, 3M, and Dentsply Sirona leading through broad product portfolios and strong professional channel relationships.
Company
Key Products
Strategic Positioning
Colgate-Palmolive
Toothpaste, mouth rinse
Mass retail dominance, global brand recognition
3M
Varnish, gel
Professional dental channel leader, strong clinical evidence base
Asia Pacific stronghold, material science expertise
Young Dental
Prophy paste, varnish
Value-focused, strong U.S. dental distributor relationships
Differentiation hinges on clinical evidence, formulation efficacy, and channel access. Colgate leverages scale and branding in retail, while 3M and Dentsply dominate professional varnish through dental distributor networks. Our analysis indicates that emerging competitors should target underserved pediatric and geriatric segments with cost-effective, easy-to-apply formulations.
What do buyers and operators need to know?
Buyers and operators must prioritize clinical efficacy, regulatory compliance, and supply chain reliability when selecting fluoride treatment products. Procurement risks include variability in fluoride release rates across varnish formulations and inconsistent reimbursement coverage. Switching costs are moderate for OTC products but high for professional varnish due to clinician training and brand loyalty. Regulatory compliance is critical, as fluoride products face scrutiny under FDA monograph systems and EU medical device regulations. Operators should verify supplier compliance with ISO 13485 for medical devices and maintain documentation for fluoride concentration and release profiles. Our analysis suggests that buyers should negotiate multi-year contracts with varnish suppliers to lock in pricing and ensure supply continuity, especially given the fragmented nature of the professional channel.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors sustained mid-single-digit growth, with the 5.8% CAGR scenario being most credible due to alignment with epidemiological data and public health spending trends. The strongest counter-argument is that fluoride-free consumer sentiment could accelerate in developed markets, potentially capping OTC toothpaste growth. However, we believe professional and prescription channels will more than offset any OTC softness.
Our analysis implies that the market is undergoing a structural shift toward higher-value professional and prescription-strength formats, driven by aging populations and expanding public health mandates. Vendors that rely solely on commoditized toothpaste face margin compression, while those with varnish and gel portfolios can capture premium pricing.
Actionable Strategy:
Investors should allocate capital toward companies with strong professional varnish and prescription-strength gel portfolios, as these segments offer higher margins and growth.
Operators should expand into Asia Pacific through partnerships with local distributors and public health programs to capture the fastest-growing regional demand.
Vendors should invest in clinical studies demonstrating fluoride release efficacy and safety to differentiate in an increasingly crowded market.
What evidence would change our conclusion: A significant regulatory restriction on fluoride in major markets (e.g., EU-wide ban) or a rapid consumer shift away from fluoride in OTC products would necessitate downward revision of growth forecasts.
Europe Dental Fluoride Treatment Market Revenue Billion Forecast, by Product 2020 & 2034
Frequently Asked Questions
1. What is the dental fluoride treatment market size in 2025?
The global dental fluoride treatment market was valued at approximately 14.8 Billion in 2025. This includes topical and systemic fluoride products across retail and clinical channels.
2. What is the projected CAGR for the dental fluoride treatment market?
The market is projected to grow at a 5.8% CAGR from 2026 to 2033, reaching 23.1 Billion by 2033. This growth is driven by rising caries prevalence and preventive care adoption.
3. Which region leads the dental fluoride treatment market?
North America leads with 35.0% revenue share in 2025, supported by high fluoride varnish adoption and water fluoridation programs. Asia Pacific is the fastest-growing region.
4. What are the key segments of the dental fluoride treatment market?
5. Who are the leading players in the dental fluoride treatment market?
Leading players include Colgate-Palmolive, 3M, Dentsply Sirona, Ultradent Products, and GC Corporation. These companies compete on formulation innovation and professional channel access.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis leverages a 70/30 primary-to-secondary research split, with in-depth interviews conducted across the value chain. We engaged with raw material suppliers, specialized producers, contract formulators, and global distributors to capture ground-level insights. Decision-makers interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring a comprehensive view of market dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing
25%
Heads of R&D
35%
Technical Directors
25%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material Suppliers
30%
Specialized Formulators
40%
Global Distributors
30%
Secondary Benchmarking & Public Trade Validation
We triangulate primary findings with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings), patent databases, and recognized technical standards from ISO and industry associations. This validation ensures data integrity and alignment with public benchmarks.
Demand Modeling & Market Sizing Triangulation
Our simultaneous top-down (macroeconomic & industry segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) modeling provides a robust market sizing framework. We reconcile discrepancies through iterative validation against historical trends and expert interviews.
 Dental Fluoride Treatment Market