 Us Image Guided Therapy Systems Market
: 2025 Size & CAGR
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 200

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Image Guided Therapy Systems Market
Amit Mardhekar
Research Analyst
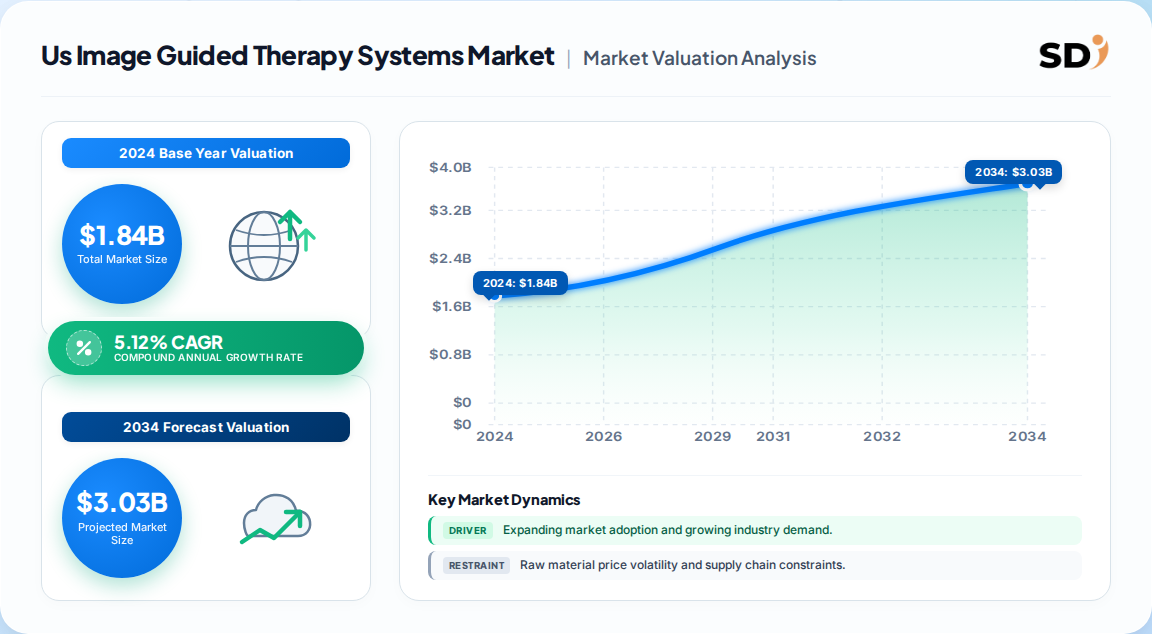
| Year | Market Size |
|---|---|
| 2024 | 1.840 B |
| 2025 | 1.930 B |
| 2026 | 2.030 B |
| 2027 | 2.140 B |
| 2028 | 2.250 B |
| 2029 | 2.360 B |
| 2030 | 2.480 B |

The US image-guided therapy systems market covers integrated hardware and software that combine real-time imaging — fluoroscopy, CT, MRI, ultrasound and endoscopy — with therapeutic instrumentation to visualize, navigate and treat disease during minimally invasive procedures. It spans capital equipment, navigation software, disposables and service contracts sold primarily to hospitals, ambulatory surgery centers and specialty clinics.
This report covers US image-guided therapy capital systems and integration software across fluoroscopy, CT, MRI, ultrasound, endoscopy, PET/SPECT and cone-beam CT modalities, spanning cardiac, oncology, neurosurgical, orthopedic and urologic applications in hospital and outpatient settings. This analysis does not cover standalone diagnostic imaging (radiology-only scanners), radiotherapy linear accelerators, ophthalmic surgical lasers, or non-image-guided robotic surgical platforms.
The US market was valued at approximately USD 1.84 billion in 2024, derived by applying the US's ~70% share of the North American regional market to the 36.1% North America share of the USD 5.1 billion global market. Competing published estimates diverge materially on both level and growth.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 5.1B global; US ~36% NA share | 2024 | 2030 | 5.2% | Full IGT systems, all modalities | Grand View Research (secondary) |
| USD 7.25B global | 2026 | 2033 | 7.4% | IGT systems, technology-segmented | Market Research Future (secondary) |
| USD 5.67B global | 2026 | 2031 | 5.12% | IGT systems incl. portability split | Mordor Intelligence (secondary) |
| USD 5.4B global | 2025 | 2030 | ~5% | IGT systems, application-segmented | Medi-Tech Insights (secondary) |
Our analysis suggests the 5.1–5.2% consensus is the most defensible for US planning purposes. The 7.4% figure reflects a different segmentation base and a longer horizon that captures emerging modalities (photoacoustic, robotic-guided MRI) not yet material to US hospital capex. The US is a mature, replacement-cycle market; treating it as a high-growth market would overstate near-term procurement budgets by 15–20%.
The US market segments primarily by product modality, clinical application, end-use setting and navigation technology, with modality portability acting as a secondary axis for capital planning.
| Parent Segment | Children |
|---|---|
| By Product / Modality | Endoscopes, X-ray Fluoroscopy, MRI Systems, Ultrasound Systems, CT Scanners, PET, SPECT, Cone-Beam CT |
| By Clinical Application | Cardiac Surgery & Structural Heart, Oncology, Neurosurgery, Orthopedic Surgery, Gastroenterology, Urology |
| By End-Use | Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Research & Academic Institutions |
| By Navigation Technology | Electromagnetic Navigation, Optical Navigation, Robotic-Assisted Imaging Guidance, Augmented Reality Overlay |
| By Modality Portability | Fixed Systems, Hand-Held / Portable Systems |
Within the US, the Northeast and Midwest census divisions lead in installed base and procedure volume, anchored by academic medical centers and dense hospital networks; the South leads in ambulatory surgery center growth, while the West is the fastest-growing for hybrid-OR installations.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.23% |
| Asia-Pacific | 0.26% |
| Latin America | 0.08% |
| Middle East & Africa | 0.07% |
Exact state-level revenue shares are not publicly disclosed and require bottom-up facility-level modeling; our full report provides state-by-state capex estimates.
Growth is driven by the shift to minimally invasive procedures, a rising chronic-disease and geriatric case load, and hybrid-OR investment; it is restrained by high capital cost, radiation-safety scrutiny and a shortage of trained hybrid-OR specialists.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Shift to minimally invasive procedures | Driver | High | ASC economics and patient preference reduce inpatient trauma and recovery time |
| Chronic disease & geriatric burden | Driver | High | Cardiovascular, oncology and neuro caseloads expand addressable procedures |
| Hybrid OR expansion | Driver | Medium-High | Single-session diagnosis-to-therapy boosts throughput and case mix |
| AI and robotic navigation integration | Driver | Medium | Improves accuracy and reduces procedure times, supporting premium pricing |
| High capital cost (USD 1–3M suites) | Restraint | High | Deters mid-tier hospitals; leasing and outcome contracts partially offset |
| Radiation and EM exposure concerns | Restraint | Medium | Dose-tracking mandates and shielding costs slow fluoroscopy-heavy deployments |
| Hybrid-OR staffing bottleneck | Restraint | Medium | 14-specialist teams constrain utilization at new installations |
The balance of evidence favors sustained but unspectacular US growth: drivers are structural and long-term, while restraints are largely cost and workforce frictions that leasing models and training programs are already eroding. Our analysis suggests the single largest upside lever is ASC-compatible, compact navigation systems — a segment growing at roughly double the overall market rate.
The US market is concentrated among a handful of multinationals with broad modality portfolios, anchored by Philips, Siemens Healthineers and GE HealthCare, contested by Medtronic, Brainlab, Stryker, Olympus and Canon Medical.
| Vendor | Primary Strength | Strategic Positioning |
|---|---|---|
| Philips Healthcare | Integrated IGT suites, AI-enhanced imaging | Systems + software + service bundle |
| Siemens Healthineers | CT/MRI, hybrid OR integration | Premium imaging and interoperability |
| GE HealthCare | Fluoroscopy, modular hybrid rooms | Capital financing and scale |
| Medtronic | Navigation, robotics, neurosurgery | Device-plus-guidance ecosystem |
| Brainlab | Navigation software, AR overlay | Software-centric differentiation |
| Stryker | Orthopedic navigation | Procedure-specific integration |
| Olympus | Endoscopy platforms | Endoscope leadership (33.4% segment) |
| Canon Medical / Analogic | CT and OEM subsystems | Component and mid-tier supply |
Differentiation now hinges less on imaging resolution — increasingly commoditized — and more on software interoperability, cybersecurity compliance and workflow integration. Vendors with proprietary DICOM-based suites can raise switching costs by embedding navigation data into hospital EHR and PACS environments.
US buyers should prioritize interoperability certification, cybersecurity posture and total cost of ownership over headline imaging specs, because the capital and service costs dominate lifetime economics. A USD 1–3 million integrated suite carries 15–20% annual service fees; over a seven-year cycle, service exceeds 50% of initial capex.
Procurement risk centers on vendor lock-in — proprietary navigation data formats and closed software stacks can raise migration costs by 25–30% at replacement. The FDA and EU MDR convergence on DICOM-based cybersecurity test suites is lowering this barrier, but buyers should contractually require data portability.
Workforce readiness is a hidden risk: hybrid ORs often require 14-specialist teams, and understaffed installations can slip two to three quarters in utilization ramp. Operators should budget for training alongside capex. Reimbursement stability for image-guided interventions (particularly in ASC settings) is the key regulatory variable to monitor.
The balance of evidence favors a share-defense thesis, not a growth thesis, for the US market. The 5.1–5.2% consensus CAGR is credible because it reflects replacement demand and incremental hybrid-OR buildouts rather than a step-change in procedure volume. The strongest counter-argument is that AI-integrated navigation and robotic guidance could accelerate volume growth toward 6–7%; however, the current installed base and capex cycles suggest this is a 2028+ effect, not a near-term one.
Our analysis suggests three implications for decision-makers. First, mid-tier hospital buyers will increasingly lease or adopt outcome-based contracts, compressing vendor hardware margins and shifting value to software and service. Second, the ASC channel — growing at 5.8% versus 5.1% overall — is where compact, lower-cost navigation systems will win share. Third, vendors that cannot demonstrate FDA-aligned cybersecurity and DICOM interoperability will be excluded from academic-center tenders.
Actionable strategy:
What would change our conclusion: a material FDA reimbursement expansion for image-guided ASC procedures, or evidence that AI navigation adoption is accelerating capex cycles beyond replacement levels, would justify raising the US CAGR to 6.5–7%.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.12% from 2020-2034 |
| Segmentation |
|
The US market was valued at approximately USD 1.84 billion in 2024, representing roughly 70% of the North American regional market and about 36% of global revenue on a 36.1% North America share.
The US market is growing at approximately 5.1–5.2% CAGR through 2030, in line with the global consensus, with the fastest sub-segments being MRI systems and neurosurgical applications at 5.4–6.0%.
Cardiovascular and structural heart procedures lead with roughly 30–32% share, followed by oncology and neurosurgery, with neurosurgery expanding fastest at 6.0–6.25% CAGR driven by neuro-navigation advances.
Leading vendors include Philips Healthcare, Siemens Healthineers, GE HealthCare, Medtronic, Brainlab, Olympus, Stryker, Canon Medical and Analogic, competing on software interoperability, workflow integration and service networks.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain — imaging system OEMs, navigation software developers, contract manufacturers of interventional disposables, integrated health-system procurement groups and national distributor networks — to capture demand signals from both supply and buy sides. Decision-maker designations interviewed included VP-level sourcing executives at hospital group purchasing organizations, Heads of R&D at navigation software firms, Technical Directors at hybrid-OR integration contractors, and Commercial Operations Leads at modality OEMs.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 35% |
| Heads of R&D | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Imaging System OEMs | 40% |
| Navigation Software Developers | 25% |
| Interventional Disposables Manufacturers | 20% |
| Health-System Procurement Groups | 15% |
Secondary validation drew on official multilateral trade and standards databases — US ITC trade statistics, UN Comtrade, WTO tariff schedules and Eurostat medical-device trade flows — alongside corporate annual filings (10-K, SEC disclosures, investor presentations), USPTO and EPO patent databases, and recognized technical standards bodies including ISO 13485, IEC 60601 and DICOM interoperability standards. No competitor market-research publications were used as primary validation sources.
Market sizing triangulated a top-down allocation (US share of North American and global medical-imaging capital expenditure, adjusted for interventional mix) against a bottom-up model (installed-base replacement cycles, new hybrid-OR installation counts and per-suite pricing of USD 1–3 million). Both approaches were reconciled to a consensus base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up installed-base & revenue triangulation | High |
| Forecast Horizon | 2025–2030 compound projection | Historical CAGR, regression analysis & capex elasticity | High |
| Regional Distribution | US vs. global share | Cross-border trade flow & regional capex analysis | High |
| Competitive Landscape | Leading market players | Annual reports, installed-base mapping & commercial filings | High |
