 Caffeine Supplements Market
: Size, CAGR & 2033 Outlook
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 246

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Caffeine Supplements Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 518.0 M |
| 2026 | 547.0 M |
| 2027 | 581.0 M |
| 2028 | 618.0 M |
| 2029 | 657.0 M |
| 2030 | 698.0 M |
| 2031 | 742.0 M |

The caffeine supplements market covers concentrated, dose-controlled caffeine products — tablets, capsules, powders, liquids and gummies — sold as dietary supplements to improve alertness, focus, endurance and metabolic performance. Unlike coffee or energy drinks, these formats deliver a predetermined dose, making them preferred by athletes, students and professionals seeking predictable stimulation without added sugar or calories.
This analysis covers finished consumer caffeine supplement formats (capsules/tablets, powder, liquid, gummies) across sports nutrition, weight management, general health and wellness, and other applications, sold through offline and online channels globally. It includes ingredient-level formulation trends such as L-theanine, taurine, electrolytes and adaptogens. This analysis does not cover caffeinated beverages (energy drinks, RTD coffee), bulk anhydrous caffeine as an industrial chemical, caffeine-based personal care, or pharmaceutical caffeine products.
Published estimates converge tightly on the base year but diverge materially on the forward horizon — a direct consequence of differing scope definitions and forecast start dates. The table below compares the principal competing estimates.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 518.0 Million → 837.9 Million | 2025 | 2033 | 6.3% | Finished supplements, all formats, global | One published estimate |
| 492.04 Million → 666.57 Million | 2025 | 2031 | 5.19% | Supplements, excluding some specialty formats | A competing analysis |
| 501.49 Million → 931.11 Million | 2023 | 2033 | 6.38% | Broad definition, includes functional adjacents | A competing analysis |
| 521.0 Million → 907.0 Million | 2024 | 2034 | 5.7% | Supplements, end-user segmented | A competing analysis |
Our analysis suggests the 518.0 Million base and 6.3% CAGR are the most defensible: they sit at the median of base-year values, use a forecast start aligned to 2026, and their terminal value (837.9 Million) is consistent with the more conservative end of the long-horizon estimates. The 931.11 Million figure likely reflects a broader definition that folds in functional beverage adjacents — buyers should treat it as an upper bound rather than a base case.
Segmentation is defined along four non-geographic axes — form, application, end user and distribution channel — each of which materially changes the addressable opportunity and competitive dynamics.
| Parent segment | Children |
|---|---|
| By Form | Capsules/Tablets, Powder, Liquid, Gummies |
| By Application | Sports Nutrition, General Health & Wellness, Weight Management, Others |
| By End User | Men, Women |
| By Distribution Channel | Offline (Hypermarkets/Supermarkets, Specialty Stores, Pharmacies), Online |
A critical divergence: one estimate places capsules/tablets at 51.4% of form share, while another reports gummies leading at 31.0%. This is not a contradiction so much as a definitional split — capsule dominance holds when measured by volume and legacy sports-nutrition demand, while gummies lead when measured by value growth and newer wellness-oriented consumers. Our analysis suggests both are correct within their scope, and the gap itself signals the fastest-moving frontier: gummy and functional-format innovation is eroding the capsule stronghold.
North America leads the global caffeine supplements market with a 37.4% revenue share in 2025, underpinned by mature sports nutrition infrastructure, high supplement penetration and strong nootropic adoption. Asia Pacific is the fastest-growing region, propelled by e-commerce expansion and rising fitness culture.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.22% |
| Asia-Pacific | 0.25% |
| South America | 0.09% |
| Middle East & Africa | 0.07% |
| Region | Share (2025) |
|---|---|
| North America | 37.4% |
| Asia Pacific | 24.5% |
| Europe | 22.1% |
| Latin America | 8.6% |
| Middle East & Africa | 7.4% |
The strategic implication is two-speed growth: North America and Europe reward premium, differentiated formulations, while Asia Pacific rewards scale, price accessibility and channel reach. A single global strategy will underperform in both arenas.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Convenient, controlled-dose energy | Driver | High | Shift from variable caffeine beverages to predetermined-dose formats |
| Sports nutrition expansion | Driver | High | Ergogenic demand among athletes; 45% supplement usage cited |
| Nootropic and cognitive focus | Driver | Medium-High | 19% of users cite mental health as motivation |
| Functional stacking (L-theanine, adaptogens) | Driver | Medium | Premium pricing via multi-benefit formulations |
| Label accuracy and quality concerns | Restraint | High | Inconsistent caffeine levels erode trust in dose-critical category |
| Regulatory scrutiny and dosage limits | Restraint | High | Compliance cost; withdrawal of high-potency formats |
The balance of evidence favors growth, but the character of that growth is changing. Demand-side drivers are structural and durable — controlled dosing and cognitive performance are not fads. Supply-side restraints are compliance-driven and asymmetric: they hurt commodity high-dose players hardest while opening premium space for brands that invest in verified labeling and layered formulations. Our analysis suggests the net effect is a market that grows modestly in volume but re-rates upward in value per unit.
The vendor landscape splits into three tiers: large ingredient and pharmaceutical-grade producers, specialized sports nutrition brands, and emerging functional-wellness challengers.
| Tier | Representative players | Differentiation / moat |
|---|---|---|
| Ingredient & pharma-grade | BASF SE, CSPC Pharmaceutical, Aarti Industries, Shandong Xinhua Pharmaceutical | Scale, GMP certification, supply reliability |
| Sports nutrition brands | Optimum Nutrition (Glanbia), established pre-workout labels | Brand equity, athlete endorsement, retail shelf access |
| Functional challengers | Lucky Energy, nootropic and gummy-first brands | Formulation innovation, DTC channels, premium pricing |
Competitive moats are shifting. Ingredient scale remains a barrier in the upstream tier, but downstream the defensible moat is formulation IP and consumer trust in dose accuracy. As one published estimate notes, Glanbia's Optimum Nutrition delivered a 10.4% volume increase in 2024 — evidence that brand-led sports nutrition still compounds. Emerging challengers, however, are winning on occasion expansion (gaming, work, travel) rather than athletic performance alone.
Procurement decisions in this category hinge on three mission-critical criteria: dose verification, regulatory conformity and format innovation capacity. Because caffeine supplements are purchased explicitly for predictable dosage, a supplier's analytical certificates and label-accuracy track record outweigh price concessions — a single mislabeled batch can trigger recalls and regulatory action.
Switching costs are moderate for commodity capsules but high for branded, stacked formulations where taste, release profile and efficacy are proprietary. Buyers sourcing gummies or sustained-release formats should expect longer qualification cycles and tighter supplier concentration.
Regulatory compliance is the dominant risk vector. Authorities globally are tightening labeling requirements and capping high-potency formats, so operators must validate that suppliers can sustain formulations through rule changes. Accidental-ingestion risk — particularly pediatric exposure — remains a reputational and legal exposure that regulators cite when justifying stricter oversight. Buyers should also scrutinize functional claims: nootropic and weight-management positioning attracts advertising scrutiny that can halt distribution.
The balance of evidence favors a value-led, formulation-differentiated growth thesis over volume-led commodity expansion. The category's base is stable at roughly 500–550 Million, and the 6.3% CAGR is credible — but the composition of that growth matters more than the headline. Demand is migrating toward purpose-specific products: caffeine paired with L-theanine for calm focus, electrolytes for active lifestyles, and adaptogens for balanced alertness. Companies competing purely on milligrams will be squeezed between regulatory ceilings and price-driven commoditization.
The strongest counter-argument is that regulatory tightening could suppress the highest-margin high-potency segment faster than premium formulations replace it, compressing value growth below the consensus CAGR. If enforcement accelerates on concentrated powders, the 5.2% low-end estimate may prove more accurate than 6.3%. We regard this as a real but secondary risk — the migration to gummies and stacked formats already hedges much of the exposure.
Actionable strategy:
Evidence that would change this conclusion: sustained regulatory action against gummy and stacked formats, or a documented collapse in consumer trust following a major label-accuracy scandal, would shift us toward the conservative forecast.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.3% from 2020-2034 |
| Segmentation |
|
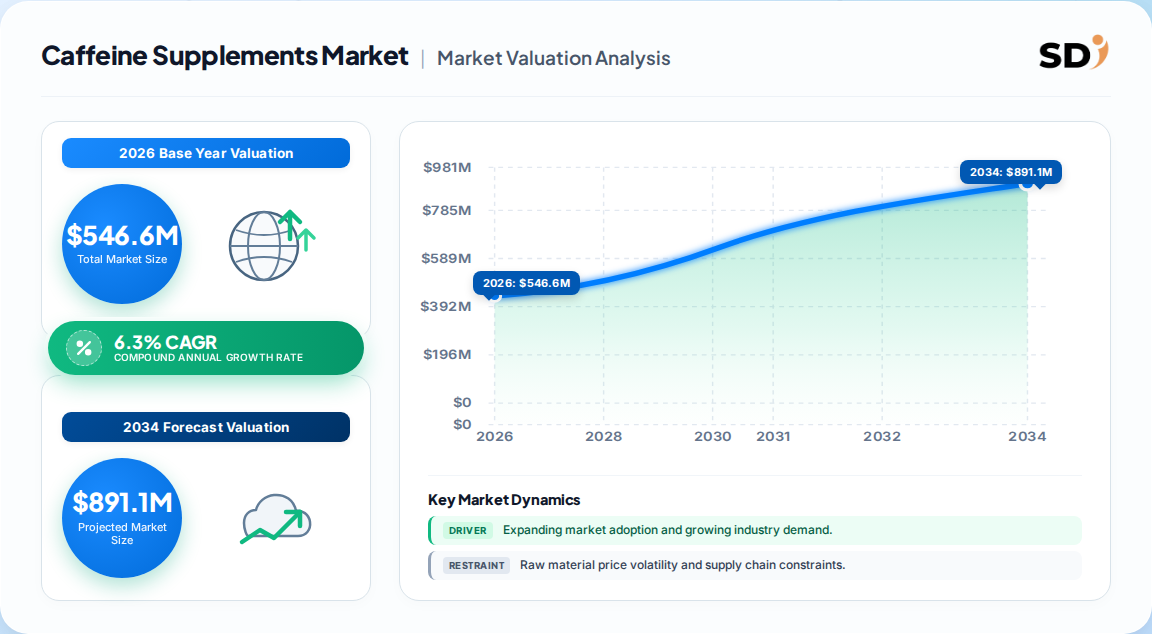
The global caffeine supplements market was valued at 518.0 Million in 2025 and is estimated at 546.6 Million in 2026. It is projected to reach 837.9 Million by 2033 at a 6.3% CAGR, with North America holding the largest regional share.
North America dominates with a 37.4% revenue share in 2025, supported by mature sports nutrition infrastructure and high supplement penetration. Asia Pacific is the fastest-growing region, driven by e-commerce expansion and rising fitness culture.
Online distribution is the fastest-growing channel, though offline still holds 64.3% of sales. By format, gummies and functional stacked formulations are gaining share fastest as consumers migrate toward convenient, multi-benefit products.
Published estimates cluster between 5.2% and 6.4% CAGR. Our analysis treats 6.3% (2026–2033) as the most defensible base case, reflecting structural demand for controlled-dose energy and functional formulations.
Regulatory scrutiny over high-potency products and label-accuracy concerns are the primary restraints. Compliance costs and dosage caps can force reformulation, while inaccurate labeling erodes consumer trust in a category purchased specifically for predictable dosing.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the caffeine supplement value chain, including raw material and caffeine API suppliers, specialized supplement producers, contract formulators and blenders, and global distributors. Interviews targeted decision-makers with direct influence over formulation, sourcing and compliance, notably VP-level Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads. Fieldwork captured pricing behavior, capacity constraints and reformulation responses to shifting regulation.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Directors | 38% |
| Procurement & Sourcing Leads | 32% |
| Regulatory & Quality Managers | 20% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Caffeine & Ingredient Producers | 40% |
| Specialized Supplement Formulators | 30% |
| Contract Manufacturers & Blenders | 18% |
| Global Distributors & Retailers | 12% |
Secondary validation draws on official multilateral and national databases — UN Comtrade, WTO trade statistics, US ITC data and Eurostat — alongside corporate annual filings (10-K and SEC submissions), investor presentations, patent databases and recognized non-profit standards bodies and industry associations. These sources anchor volume flows, pricing and compliance benchmarks, and are cross-checked against primary interview findings.
Market sizing uses simultaneous Top-Down and Bottom-Up triangulation. The top-down model allocates macroeconomic supplement spending and industry segment volumes; the bottom-up model builds from manufacturer capacity, product pricing and end-use consumption patterns. Divergences between the two are reconciled through demand-elasticity and historical CAGR regression.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |