 Personal Care Shower Bath Market
 Size, Trends & 2033 Forecast
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 206

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Personal Care Shower Bath Market
Amit Mardhekar
Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 104.3 B |
| 2026 | 110.3 B |
| 2027 | 116.8 B |
| 2028 | 123.6 B |
| 2029 | 130.8 B |
| 2030 | 138.4 B |
| 2031 | 146.4 B |

The personal care shower bath market covers consumer products used for daily body cleansing and hygiene, including shower gels, liquid soaps, body washes, solid bar soaps, bath products, and exfoliating body scrubs. It excludes facial skincare, hair care, shaving products, and creams and lotions sold separately.
This analysis covers global retail and trade flows for shower gels, liquid soap, body washes, solid soap, and body scrubs across offline and online channels, with a 2025 base year and forecasts to 2033. It tracks product type, distribution channel, and regional demand. This analysis does not cover facial skincare, hair care, shaving products, body lotions, sun protection, or professional spa equipment.
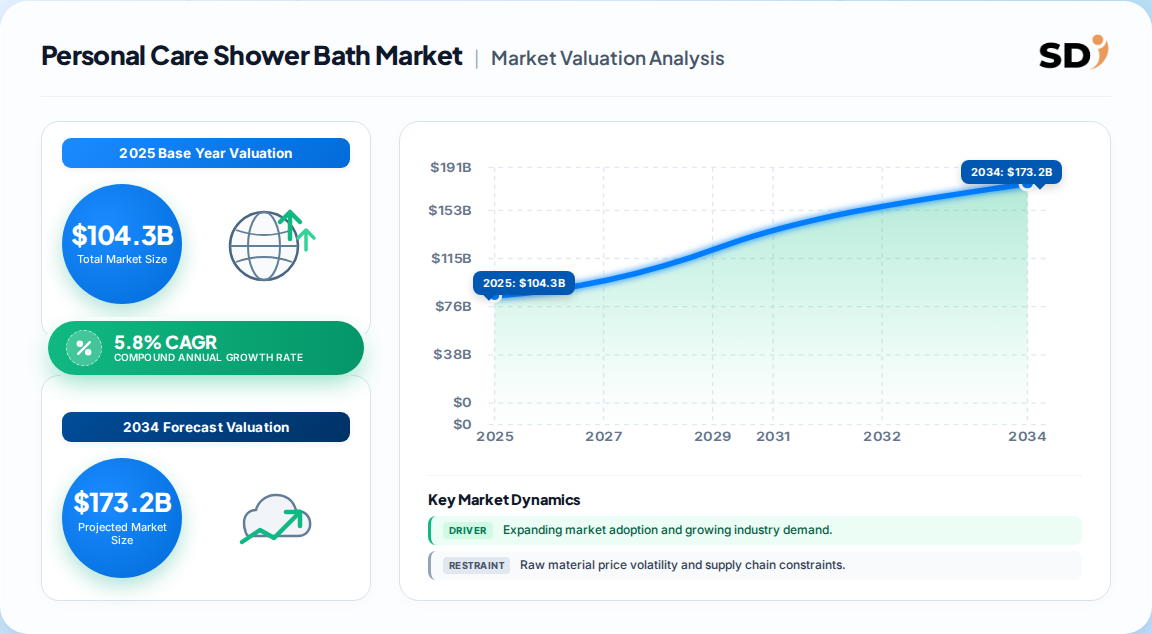
The personal care shower bath market is most credibly sized at 110.3 Billion in 2026, rising to 163.7 Billion by 2033 at a 5.8% CAGR, based on the broadest global scope and consistent category definition.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 104.3 Billion | 2025 | 2033 | 5.8% | Global; shower gels, liquid soap, body scrubs, solid soap | One published global estimate |
| 110.3 Billion | 2026 | 2033 | 5.8% | Global; same category scope, retail B2C | One published global estimate |
| 13.5 Billion | 2025 | 2031 | 1.49% | North America only; bar soap, body wash, more | A competing regional analysis |
The global figure is the most defensible because it aggregates all regions and product formats at retail value, while the North American estimate is a narrower geographic slice at a mature, low-growth rate. Our analysis suggests the gap between the 5.8% global CAGR and the 1.49% North American CAGR implies the growth center of gravity has shifted decisively toward Asia Pacific and emerging markets.
The category segments primarily by product type, with shower gels and liquid soap the largest format and body scrubs the fastest-growing, alongside a clear split between offline and online distribution.
| Parent segment | Children |
|---|---|
| By Type | Shower Gels & Liquid Soap, Body Scrubs, Solid Soap |
| By Distribution Channel | Offline (Supermarkets/Hypermarkets, Pharmacies, Specialty Beauty Retailers, Grocery Stores), Online (Marketplaces, DTC, Omnichannel) |
Shower gels and liquid soap held about 40% of 2025 revenue, supported by demand for convenient, hygienic, skin-friendly formats. Body scrubs are projected to grow at a significant CAGR as at-home skincare routines expand. Offline captured roughly 75% of revenue, but online is forecast to grow fastest on DTC and marketplace expansion.
Asia Pacific leads the personal care shower bath market with roughly 30% of 2025 revenue, while Europe is the fastest-growing region through 2033, reflecting premiumization and clean-label adoption.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.3% |
| Europe | 0.24% |
| North America | 0.22% |
| Latin America | 0.12% |
| Middle East & Africa | 0.12% |
Asia Pacific's lead is driven by rising disposable incomes, urbanization, and hygiene awareness across China and India. Europe's faster CAGR reflects stringent clean-label preferences and premium product penetration. North America remains large but mature, with body wash outpacing bar soap and online retail growing at a mid-single-digit rate.
Growth is driven by hygiene awareness, premiumization, clean-label demand, and e-commerce expansion, while high premium pricing and regulatory compliance costs restrain broader adoption among price-sensitive consumers.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising hygiene and self-care awareness | Driver | High | Frequent bathing routines sustain baseline demand |
| Natural, sulfate-free, dermatologist-tested demand | Driver | High | Consumers trade up to skin-friendly formulations |
| E-commerce and DTC expansion | Driver | High | Improves access and discovery across demographics |
| Multifunctional and premium fragrance innovation | Driver | Medium | Supports differentiation and premium pricing |
| High prices of premium/natural formats | Restraint | Medium | Limits adoption among price-sensitive buyers |
| Regulatory scrutiny of synthetics and packaging | Restraint | Medium | Raises formulation and compliance costs |
The balance favors growth: drivers are structural and demand-led, while restraints are cost- and price-related and partially offset by format innovation. Our analysis suggests premium pricing is a bigger risk in mature Western markets than in Asia Pacific, where value-tier demand still dominates volume.
The market is moderately concentrated, led by Unilever, Procter & Gamble, Henkel, Kenvue and Colgate-Palmolive, whose scale, brand portfolios, and multi-channel distribution create durable competitive moats.
| Company | Portfolio focus | Strategic position |
|---|---|---|
| Unilever | Body wash, bar soap, shower gel | Global scale and mass-premium reach |
| Procter & Gamble | Body wash, bar soap | Strong North American retail presence |
| Henkel | Shower and bath, skin care | European strength and sustainability focus |
| Kenvue | Consumer health-adjacent personal care | Dermatology-led positioning |
| Colgate-Palmolive | Bar soap and liquid cleansers | Emerging-market distribution depth |
| Bath & Body Works | Premium shower gels, soaps, fragrance | Experiential retail and gifting |
Differentiation increasingly rests on formulation credibility — sulfate-free, pH-balanced, microbiome-friendly claims — rather than price alone. Vertically integrated ingredient supply and in-house packaging give leaders a cost edge, while premium specialists compete on fragrance and experiential retail.
Buyers should prioritize formulation transparency, dermatological validation, and packaging sustainability, as these are now primary selection criteria rather than differentiators. Procurement risk concentrates in natural ingredient price volatility and regulatory divergence across markets.
Switching costs are moderate for retailers but high for brands, given shelf-space contracts and consumer loyalty to established formats. Compliance with labeling, ingredient safety, and packaging rules varies by region, raising the cost of multi-market launches. Operators should secure supply contracts for sulfate-free surfactants early and build dual-channel distribution to hedge offline concentration. Our analysis suggests the 75% offline share is a structural risk if digital adoption accelerates faster than expected.
The balance of evidence favors a premiumization-led growth strategy. The 5.8% global CAGR is credible and underpinned by structural hygiene and skincare demand, but the spread between global and North American growth shows returns increasingly depend on emerging-market exposure. The strongest counter-argument is that premium pricing could stall in inflationary conditions, compressing volumes in value-sensitive segments.
We judge this risk manageable because clean-label and dermatologist-tested formats are moving from niche to mainstream, and multifunctional innovation supports price realization. Europe's fastest-growth status reinforces that regulation and consumer sophistication, not just income growth, drive premium adoption. Vendors that lag on formulation credibility will face margin compression as private label closes the quality gap.
Actionable strategy:
What would change our conclusion: a sustained deceleration in Asia Pacific disposable income growth or a sharp regulatory ban on key synthetic ingredients would lower the growth trajectory and shift the optimal strategy toward value-tier defense.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.8% from 2020-2034 |
| Segmentation |
|
The global personal care shower bath market was valued at 104.3 Billion in 2025 and is estimated at 110.3 Billion in 2026. It is projected to reach 163.7 Billion by 2033, growing at a 5.8% CAGR over the forecast period.
Asia Pacific leads with roughly 30% of 2025 revenue, driven by China and India. Europe is the fastest-growing region through 2033, reflecting premiumization and clean-label adoption across mature Western markets.
Shower gels and liquid soap dominate, holding about 40% of 2025 revenue. Consumers increasingly prefer convenient, hygienic, skin-friendly formats over traditional bar soap, supporting premium liquid cleansing products.
Leading vendors include Unilever, Procter & Gamble, Henkel, Kenvue and Colgate-Palmolive. These players leverage scale, brand portfolios, vertically integrated supply chains and multi-channel distribution to maintain competitive advantage.
Premiumization, sulfate-free and dermatologist-tested formulations, sustainable packaging and e-commerce expansion are the defining trends. Consumers increasingly seek multifunctional products that combine cleansing with skin-nourishing and exfoliating benefits.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split, with in-depth interviews across the value chain: raw material and surfactant suppliers, specialized personal care producers, contract formulators, and global distributors. We engage decision-makers including VP-level Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads to validate demand, pricing, and formulation trends.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing | 35% |
| Heads of R&D | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Surfactant Suppliers | 40% |
| Specialized Personal Care Producers | 35% |
| Contract Formulators | 15% |
| Global Distributors | 10% |
We triangulate against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards and industry associations. These sources anchor category definitions, trade flows, and competitive positioning.
We run simultaneous Top-Down (macroeconomic and segment allocation) and Bottom-Up (manufacturer capacity, product pricing, end-use consumption) models, reconciling the two to produce a defensible base-year valuation and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
