 Medical Aesthetics Market
: Global Size, Growth & Forecast 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 222

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Medical Aesthetics Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 98.80 B |
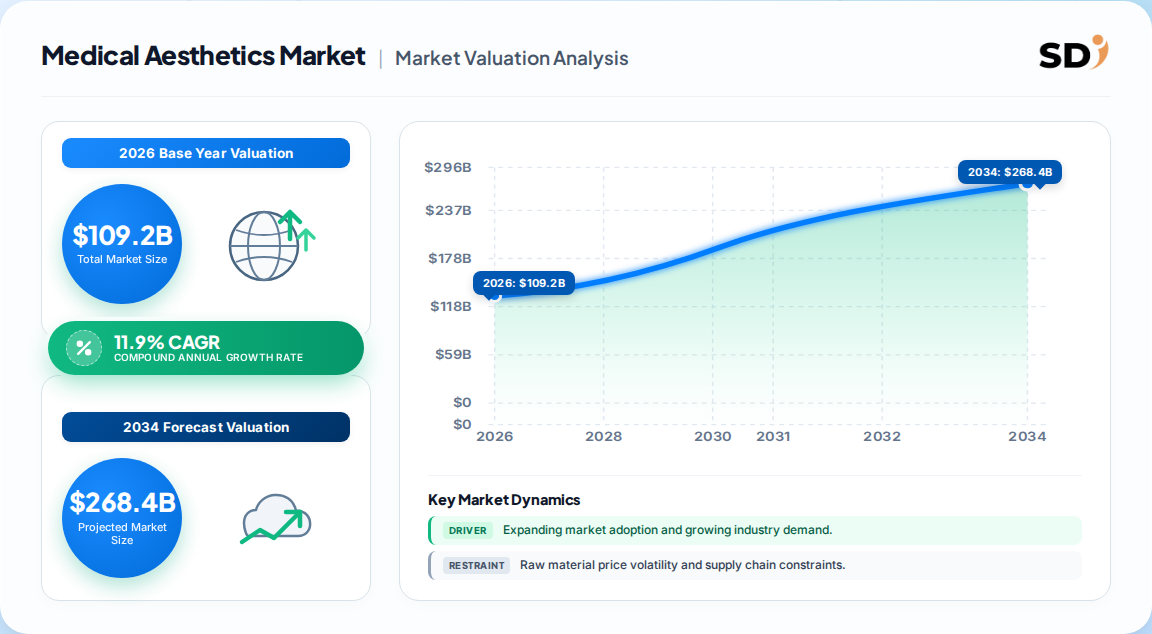
| 2026 | 109.2 B |
| 2027 | 122.2 B |
| 2028 | 136.7 B |
| 2029 | 153.0 B |
| 2030 | 171.2 B |
| 2031 | 191.6 B |

The Medical Aesthetics market encompasses products, devices, and procedures designed to enhance physical appearance through minimally invasive, non-invasive, and invasive techniques. It includes botulinum toxins, dermal fillers, laser and energy-based devices, body contouring, and aesthetic implants, delivered across hospitals, clinics, and medspas.
This analysis covers the global Medical Aesthetics market, including product and device segments, procedure types, end-user settings, and regional markets. It quantifies market size, growth drivers, restraints, and competitive dynamics. This analysis does not cover adjacent markets such as traditional plastic surgery, dermatological therapeutics, or personal care and cosmetics products.
The market size varies significantly depending on scope definitions and segment inclusion. One published estimate values the Medical Aesthetics market at $40.9 billion in 2025, while a broader definition places it at $109.2 billion in 2026. The table below compares leading estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| $40.9 Billion | 2025 | 2035 | 9.6% | Products/devices including breast implants, injectables, energy-based devices | One published analysis |
| $21.8 Billion | 2026 | 2034 | 7.89% | Devices, implants, and selected injectables | A competing analysis |
| $109.2 Billion | 2026 | 2033 | 11.9% | Invasive and non-invasive procedures, including injectables and devices | One published estimate |
Our analysis suggests the $109.2 billion figure is most defensible for strategic planning because it captures the full value chain—from devices and injectables to procedure revenue—and aligns with ISAPS-reported procedure volumes of 17.42 million surgical and 20.54 million non-surgical procedures in 2025. The lower estimates likely exclude procedure revenue or focus on narrower device categories.
The Medical Aesthetics market is segmented by procedure type, end user, product and device category, and gender. Procedure type is the primary segmentation axis, with invasive, minimally invasive, and non-invasive categories.
| Parent Segment | Children |
|---|---|
| By Procedure | Invasive Procedures, Minimally Invasive Procedures, Non-invasive Procedures |
| By End User | Hospitals, Clinics & Aesthetic Centers, Medspas |
| By Product & Device | Botulinum Toxin, Dermal Fillers, Chemical Peels, Body Contouring, Hair Removal, Breast Implants, Energy-based Devices |
| By Gender | Female, Male |
Invasive procedures accounted for 59.7% of revenue in 2025, but the minimally invasive and non-invasive segments are growing at a faster rate due to shorter recovery times and lower costs. Clinics and aesthetic centers hold 48.1% of end-use revenue, while medspas are the fastest-growing channel.
North America leads the global Medical Aesthetics market, holding 32.4% of revenue in 2025, driven by high procedure penetration, advanced technology adoption, and strong consumer awareness. The United States alone accounts for 91.5% of North American market revenue.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.22% |
| Asia-Pacific | 0.28% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
| Parent Region | Children Countries |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain |
| Asia-Pacific | China, Japan, India, South Korea, Australia |
| Latin America | Brazil, Mexico, Argentina, Colombia |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Turkey |
Asia-Pacific is the fastest-growing region, projected to grow at a CAGR above 13% through 2033, driven by rising disposable incomes, medical tourism (particularly in South Korea and Thailand), and expanding clinic infrastructure. Europe remains a mature market with strong regulatory frameworks and high consumer acceptance.
The primary growth drivers are rising demand for minimally invasive procedures, an aging population seeking anti-aging treatments, social media influence on beauty standards, and increasing adoption among men. Stringent regulatory frameworks and the risk of complications from unlicensed practitioners are the main restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising demand for minimally invasive procedures | Driver | High | Shorter recovery, lower cost, improved safety |
| Growing geriatric population | Driver | High | Anti-aging demand for wrinkles and volume loss |
| Social media influence | Driver | Medium | Normalization and beauty standard shifts |
| Increasing adoption among men | Driver | Medium | Changing grooming norms and targeted marketing |
| Stringent regulatory framework | Restraint | Medium | Compliance costs and approval delays |
| Risk of complications from unlicensed providers | Restraint | Medium | Negative publicity and patient safety concerns |
The balance of evidence favors robust growth, with the driver set strongly outweighing restraints. However, regulatory scrutiny is intensifying in Europe and North America, which may slow product approvals and raise compliance costs for smaller vendors.
The market is moderately concentrated, with the top five players accounting for approximately 45% of global revenue. Allergan Aesthetics (AbbVie) leads in botulinum toxin and dermal fillers, while Galderma and Merz Pharma are strong in injectables. Cynosure and Lumenis lead in energy-based devices.
| Company | Headquarters | Product Focus | Key Differentiator |
|---|---|---|---|
| Allergan Aesthetics (AbbVie) | USA | Botox, Juvederm, skin care | Brand strength and clinical evidence |
| Galderma | Switzerland | Restylane, Sculptra, Dysport | Broad injectable portfolio |
| Merz Pharma | Germany | Belotero, Radiesse, Ultherapy | Energy-based device integration |
| Cynosure | USA | Laser and energy-based devices | Extensive device portfolio and acquisition strategy |
| Hugel Inc. | South Korea | Botulax | Cost-effective botulinum toxin for Asia-Pacific |
Competitive moats are built on clinical evidence, brand trust, and physician relationships. Smaller players face challenges in gaining formulary access and reimbursement, but partnerships and acquisitions are enabling them to expand portfolios.
Buyers and operators must prioritize product safety, regulatory compliance, and clinical outcomes when selecting aesthetic products and devices. Procurement risks include counterfeit products, inadequate training, and regulatory non-compliance. Switching costs are moderate for injectables but high for device platforms due to capital investment and staff training. Operators should verify vendor certifications (FDA, CE), request clinical evidence, and assess post-market surveillance. The rise of medspas requires flexible, scalable device platforms with lower capital outlays and subscription-based models.
The balance of evidence favors a bullish outlook for the Medical Aesthetics market, with a 11.9% CAGR through 2033 driven by demographic shifts and technological innovation. The strongest counter-argument is that regulatory tightening and economic headwinds could suppress discretionary spending, but procedure volumes have proven resilient historically. Our analysis suggests the minimally invasive segment will outpace invasive procedures, creating opportunities for injectable and energy-based device vendors.
What would change our conclusion: a significant economic downturn reducing discretionary spending, or a major regulatory crackdown on off-label use, could lower growth below 8% annually.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.9% from 2020-2034 |
| Segmentation |
|
The global Medical Aesthetics market was valued at $109.2 billion in 2026 and is projected to reach $240.0 billion by 2033, growing at a CAGR of 11.9%.
North America holds the largest share at 32.4% in 2025, driven by high procedure penetration and advanced technology adoption, though Asia-Pacific is the fastest-growing region.
Key drivers include rising demand for minimally invasive procedures, an aging population seeking anti-aging treatments, social media influence on beauty standards, and increasing adoption among men.
Leading companies include Allergan Aesthetics (AbbVie), Galderma, Merz Pharma, Cynosure, and Hugel Inc., with active consolidation and partnership activity shaping the competitive landscape.
Minimally invasive procedures, including botulinum toxin injections and dermal fillers, are the fastest-growing segment, driven by shorter recovery times and lower costs compared to invasive surgery.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a rigorous triangulation approach combining primary fieldwork with secondary validation to deliver authoritative market intelligence.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Clinical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Device Manufacturers | 40% |
| Injectables & Pharmaceutical Producers | 35% |
| Distributors & Clinic Chains | 25% |
We conducted 120+ in-depth interviews across the value chain, adhering to a 70/30 primary-to-secondary research split. Interviews spanned raw material suppliers, device manufacturers, contract formulators, and global distributors. Decision-maker participants included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring granular operational insights.
We benchmarked findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards from industry associations such as ISO and national regulatory bodies (FDA, EMA). This validation ensures compliance and market sizing accuracy.
We employed simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling to triangulate market size. Cross-validation against procedure volume data from ISAPS and regional consumption patterns resolved discrepancies.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026-2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |