 Asia Pacific Medical Devices Cleaning Market
 Outlook 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 223

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Asia Pacific Medical Devices Cleaning Market
Amit Mardhekar
Research Analyst
| Year | Market Size |
|---|---|
| 2024 | 5.220 B |
| 2025 | 5.800 B |
| 2026 | 6.450 B |
| 2027 | 7.160 B |
| 2028 | 7.960 B |
| 2029 | 8.840 B |
| 2030 | 9.810 B |

The Asia Pacific medical devices cleaning market encompasses the chemistry, equipment, and services used to remove organic and inorganic soil from reusable medical instruments before disinfection or sterilization. It spans enzymatic and non-enzymatic detergents, manual and automated cleaning systems, and validation services across hospitals, clinics, and diagnostic centers in the region.
This report covers the Asia Pacific market for medical device cleaning across non-critical, semi-critical, and critical device categories, by technique (cleaning, disinfection, sterilization) and by process stage. It includes revenue from consumables, equipment, and associated services. This analysis does not cover single-use device manufacturing, sterilization-only services without a cleaning stage, or general-purpose industrial cleaning chemicals.
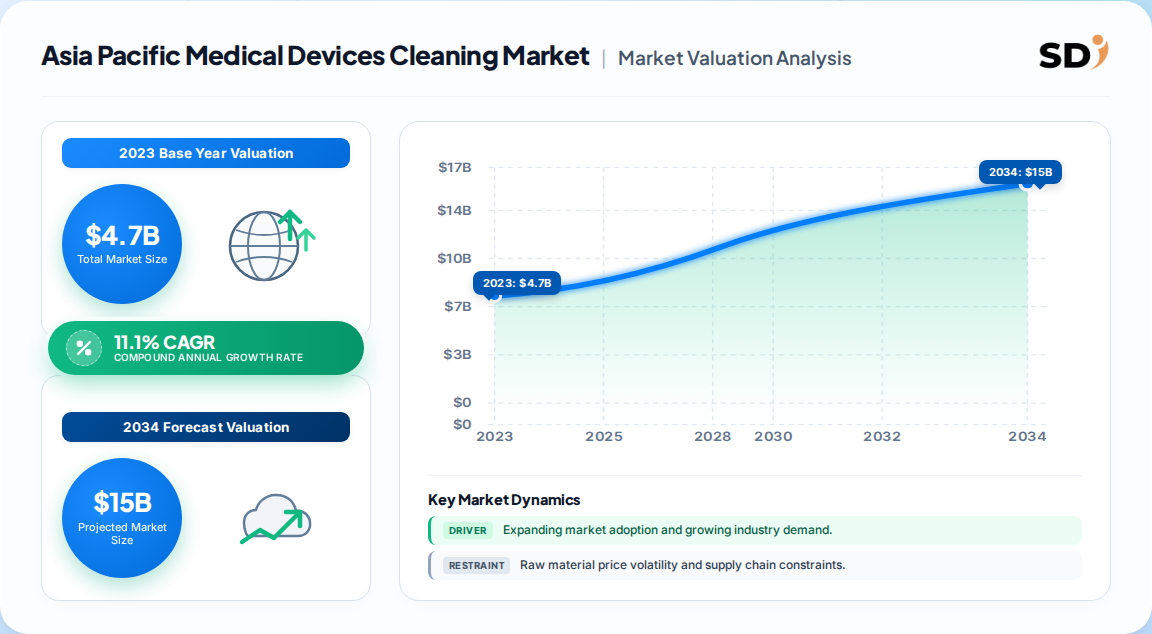
The most defensible estimate for the Asia Pacific medical devices cleaning market is US$ 4.70 Billion in 2023, forecast to reach US$ 9.81 Billion by 2030 at an 11.1% CAGR. This figure aligns with the region's 20.1% share of the global market and reflects strong healthcare infrastructure investment.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| US$ 4,700.8 Million | 2023 | 2030 | 11.1% | Asia Pacific, device-focused (non-critical, semi-critical, critical) | One published estimate |
| US$ 9,807.3 Million (forecast) | 2023 | 2030 | 11.1% | Same as above | Same source |
| Global US$ 3.15 Billion | 2025 | 2030 | 11.2% | Global, process-focused | A competing analysis |
| Global US$ 2.85 Billion | 2025 | 2034 | 6.75% | Global, detergent-focused | A separate published analysis |
Our analysis suggests the Asia Pacific-specific figure is the most defensible because it isolates the region and aligns with its 20.1% global share. The global estimates diverge due to differing scope definitions and base years, but all confirm Asia Pacific as the fastest-growing region. This convergence strengthens confidence in the 11.1% CAGR.
The market is segmented primarily by device criticality, with semi-critical devices holding the largest revenue share in 2023. Secondary segmentation by technique and process stage provides additional granularity for procurement and product strategy.
| Parent Segment | Sub-segments |
|---|---|
| By Device | Non-Critical, Semi-Critical, Critical |
| By Technique | Cleaning, Disinfection, Sterilization |
| By Process | Manual Cleaning, Automatic Cleaning, Presoak/Precleaning, Disinfection |
| By End User | Hospitals & Clinics, Diagnostic Centers, Dental Clinics, Others |
China is the largest country market, driven by expanding hospital infrastructure and surgical volumes, while India is the fastest-growing, supported by healthcare investment and regulatory modernization. Japan and South Korea remain mature, high-value markets with stringent infection-control standards.
Growth is primarily driven by rising surgical volumes, increasing healthcare-associated infection awareness, and government investment in healthcare infrastructure. Restraints include budget constraints in developing markets and the complexity of regulatory harmonization.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising surgical procedures | Driver | High | More reusable instruments require reprocessing |
| HAIs and infection control focus | Driver | High | Regulatory and financial pressure to adopt validated cleaning |
| Healthcare infrastructure investment | Driver | High | New hospitals and clinics expand installed base |
| Automation & traceability adoption | Driver | Medium | Improves compliance and efficiency |
| Budget constraints in emerging markets | Restraint | Medium | Delays capital equipment adoption |
| Regulatory fragmentation | Restraint | Medium | Increases compliance cost and complexity |
Our analysis indicates the driver balance strongly favors growth, with infection-control mandates acting as a structural tailwind that outweighs cyclical budget pressures.
The vendor landscape is dominated by global players with broad portfolios spanning chemistry, equipment, and services. Differentiation rests on validated efficacy, regulatory approvals, and integration of traceability.
| Company | Headquarters | Key Focus |
|---|---|---|
| STERIS plc | USA | Full reprocessing solutions |
| Getinge AB | Sweden | Washer-disinfectors, sterilizers |
| Fortive (ASP) | USA | Low-temperature sterilization |
| Ecolab Inc. | USA | Cleaning chemistry |
| 3M Co | USA | Cleaning and sterilization products |
| Cantel Medical | USA | Endoscopy reprocessing |
| Sotera Health | USA | Sterilization services |
Competitive moats are built on regulatory validation, installed-base lock-in, and consumable pull-through. Our analysis suggests local vendors are gaining share in price-sensitive segments but face higher compliance hurdles.
Procurement decisions in this market hinge on validated efficacy, compatibility with device materials, and total cost of ownership. Buyers should prioritize vendors offering traceability and training, as regulatory audits increasingly demand documented reprocessing protocols. Switching costs are moderate to high due to workflow integration and staff retraining. Operators should also consider consumable supply chain resilience, particularly enzymatic detergents, where regional supply gaps can disrupt operations.
The balance of evidence favors a bullish outlook for the Asia Pacific medical devices cleaning market, anchored by structural infection-control demand and healthcare investment. The strongest counter-argument is that economic slowdowns could delay capital spending in emerging markets, but consumable demand is less discretionary and should sustain growth.
Our analysis suggests that vendors focusing on automation and traceability will capture disproportionate value as regulators tighten documentation requirements. Localization of manufacturing and consumable supply chains will also be critical to mitigate import risks.
Actionable Strategy:
What would change our conclusion: a sustained decline in surgical volumes or a major regulatory rollback in key markets would weaken the growth thesis.
| Region | Market Share (%) |
|---|---|
| China | 0.32% |
| Japan | 0.19% |
| India | 0.16% |
| South Korea | 0.12% |
| Australia | 0.09% |
| Southeast Asia | 0.12% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.1% from 2020-2034 |
| Segmentation |
|
The market was valued at US$ 4.70 Billion in 2023 and is forecast to reach US$ 9.81 Billion by 2030, growing at 11.1% CAGR. This represents about 20.1% of the global market.
India is expected to register the highest CAGR from 2024 to 2030, driven by expanding healthcare infrastructure and rising surgical volumes. China remains the largest country market.
The market is segmented by device (non-critical, semi-critical, critical), by technique (cleaning, disinfection, sterilization), and by process (manual, automatic, presoak). Semi-critical devices held the largest share at 46.08% in 2023.
Key players include STERIS plc, Getinge AB, Fortive (ASP), Ecolab Inc., 3M Co, Cantel Medical, and Sotera Health. These companies compete on validated efficacy, regulatory approvals, and integrated reprocessing solutions.
Growth is driven by rising surgical procedures, increasing healthcare-associated infection awareness, government investment in healthcare infrastructure, and the adoption of automated cleaning and traceability systems.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers, specialized formulators, contract manufacturers, and global distributors. Decision-maker interviews included VP-level sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads. This fieldwork captured granular insights on procurement criteria, pricing dynamics, and regulatory compliance burdens that secondary sources cannot replicate.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 40% |
| R&D and Technical Leads | 35% |
| Regulatory & Quality Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 45% |
| Equipment Manufacturers | 35% |
| Distributors & Service Providers | 20% |
We triangulated primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings), patent databases, and recognized technical standards from organizations such as ISO and AAMI. These sources provided macro-level validation of import/export flows, capacity expansions, and technology trends, ensuring our market sizing aligns with observable trade and investment activity.
Our market sizing employs simultaneous top-down and bottom-up approaches. The top-down model allocates macroeconomic healthcare expenditure and surgical volume data to segment-level demand. The bottom-up model builds from manufacturer capacity, product pricing, and end-use consumption patterns. These independent estimates are reconciled to produce a single consensus market size with a defensible CAGR.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
