 North America Mobile Fixed Medical Imaging Services Market
North America Mobile & Fixed Medical Imaging Services Market 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 252

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 North America Mobile Fixed Medical Imaging Services Market
Amit Mardhekar
Research Analyst

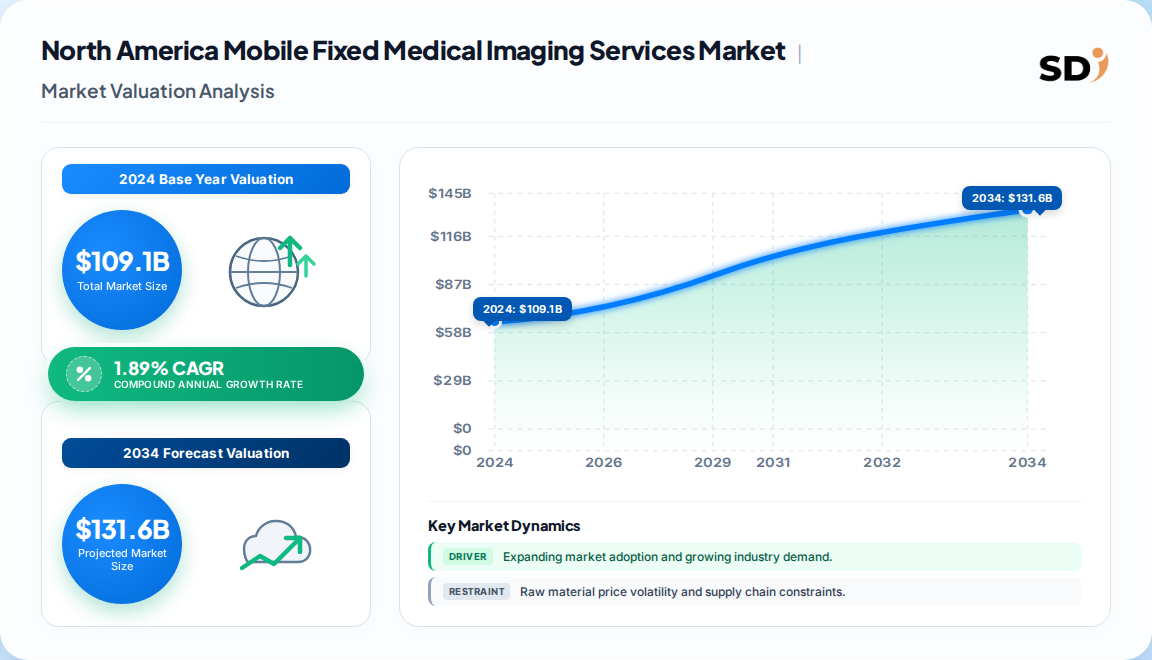
| Year | Market Size |
|---|---|
| 2024 | 109.1 B |
| 2025 | 111.2 B |
| 2026 | 113.3 B |
| 2027 | 115.4 B |
| 2028 | 117.6 B |
| 2029 | 119.8 B |
| 2030 | 122.1 B |

The North America mobile and fixed medical imaging services market encompasses diagnostic imaging delivered through permanent hospital and clinic radiology departments (fixed) and through vehicle-based or portable units deployed to patients' bedsides, homes, and underserved sites (mobile), spanning X-ray, ultrasound, MRI, CT, mammography, and PET/CT modalities.
This report covers fixed radiology services and mobile/interim imaging services across the U.S., Canada, and Mexico, segmented by technology, application, and end use. This analysis does not cover imaging equipment manufacturing (OEM device sales), contrast media or radiopharmaceuticals, teleradiology software licensing as a standalone market, or non-imaging diagnostic services such as laboratory testing.
The most defensible base figure is USD 109.1 billion for 2024, though this combined figure should be read as a services-revenue envelope rather than a device market — a distinction many buyers miss.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 109.1 Billion | 2024 | 2025–2030 | 1.89% | Combined mobile + fixed imaging services revenue, North America | One published estimate |
| USD 17.31 Billion (2026) | 2026 | 2026–2031 | 4.07% | Mobile imaging services only, global | A competing analysis |
| USD 18.1 Billion (2024) | 2024 | 2025–2034 | 5.2% | Mobile imaging services only, global | A competing analysis |
| USD 2.12 Billion (2025) | 2025 | 2026–2035 | 5.8% | Narrowly defined mobile imaging services, global | A competing analysis |
Interpretation: The three-fold spread among mobile-only estimates (USD 2.1B to 18.1B) reflects definitional boundaries — whether ambulance-based, in-hospital portable, and equipment-rental revenue are counted. Our analysis suggests the ~USD 17–18B global mobile figure is the most plausible because it aligns with North America's ~40% share and the combined USD 109.1B envelope (mobile would then represent roughly 6–7% of combined services revenue, consistent with fixed radiology dominance). The 1.89% blended CAGR is credible for the combined market but understates mobile's true trajectory; buyers should treat it as a floor, not a ceiling, for mobile planning.
Segmentation in this market follows three axes: technology (mobile vs. fixed), clinical application, and end-use setting — with mobile modalities carrying materially different growth profiles than fixed ones.
| Parent segment | Children |
|---|---|
| By Technology | Mobile & Interim Imaging Services (X-ray, Ultrasound, MRI, CT, PET/CT, Mammography, Nuclear Imaging), Fixed Radiology Services |
| By Application | Orthopedics, Oncology, Cardiology, Neurology, Gastroenterology, Urology, Others |
| By End Use | Hospitals & Private Clinics, Diagnostic Imaging Centers, Ambulatory Surgical Centers, Home Healthcare Providers, Long-Term Care Facilities |
Analyst note: Orthopedics (~35.6% of mobile applications) and oncology (PET/CT growing ~5.6% CAGR) are the two application pockets where mobile capability genuinely changes clinical pathways, not just logistics. Buyers should weight these segments disproportionately in diligence.
The United States leads decisively, accounting for roughly three-quarters of North American services revenue, driven by the largest chronic-disease burden, the deepest hospital-at-home reimbursement infrastructure, and the highest imaging procedure volumes in the region.
Regional share table (estimated):
| Country | Share of North America revenue |
|---|---|
| United States | ~78% |
| Canada | ~15% |
| Mexico | ~7% |
Canada's interim-imaging use case is structurally distinct: provincial wait-time guarantees create a public-sector buyer for mobile MRI and CT that has no direct U.S. analogue. Our analysis suggests Canada is the most under-modeled sub-market in North America for mobile providers.
Growth is driven by chronic-disease burden, an aging population, reimbursement expansion for hospital-at-home, and portable-imaging technology — while capital costs, technologist shortages, and radiation-compliance hurdles cap the pace.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Chronic disease burden (cancer, CVD, COPD) | Driver | High | Rising scan volumes; ~2.04M new U.S. cancer cases projected 2025 |
| Aging population (65+ rising 47% by 2050 in U.S.) | Driver | High | Frequent monitoring; mobility barriers favor mobile delivery |
| Hospital-at-home reimbursement codes | Driver | Medium-High | 2025 Medicare PFS parity for remote supervision |
| Portable/AI imaging technology | Driver | Medium | AI cuts interpretation time ~30%; handheld ultrasound ~80% cost savings |
| High capital cost of mobile scanners | Restraint | High | Mobile PET/CT USD 1.5–3M; mobile MRI >USD 2M |
| Certified technologist shortage | Restraint | Medium-High | Limits fleet utilization; acute in North America |
| Radiation-exposure compliance | Restraint | Medium | FDA source-to-skin distance ≥30 cm; shielding/transport costs |
The balance: Demand-side forces are structural and multi-year; supply-side constraints are cyclical and addressable through rental models and AI-assisted workflow. Our analysis suggests the net effect favors mobile volume growth of 4–6% annually even as blended market growth stays near 2%. The binding constraint is not demand — it is trained personnel and capital access for smaller operators.
The market is moderately concentrated, with hospital-centric fixed radiology incumbents and specialized mobile-fleet operators competing on different moats — fleet density and payer contracts versus installed-base relationships.
| Company type | Representative players | Strategic moat |
|---|---|---|
| Mobile fleet operators | Specialized mobile imaging providers | Fleet density, route economics, payer contracts |
| Hospital/health-system radiology | Integrated delivery networks | Installed base, referral control, capital access |
| Device-enabled service providers | OEM-affiliated service arms (e.g., GE HealthCare, Philips ecosystems) | AI software, handheld platforms (e.g., Lumify), service attach |
| Diagnostic imaging center chains | Outpatient imaging networks | Volume aggregation, outpatient shift capture |
Differentiation: Fixed incumbents own referral pathways; mobile specialists own last-mile logistics. The most defensible position is hybrid — owning both the reading relationship and the fleet. Device-level AI (e.g., pneumothorax detection at 96% sensitivity) is becoming table stakes rather than a differentiator, which compresses software-only margins.
Procurement decisions in this market hinge on four mission-critical criteria: reimbursement coverage certainty, fleet utilization economics, technologist staffing depth, and radiation-safety compliance documentation. Buyers should demand payer-contract evidence, not just equipment specs.
Switching costs are asymmetric. Moving from a fixed-only to a mobile-augmented model is a multi-year operational build (dispatch, shielding, QA cadence), but once embedded in hospital-at-home programs, contracts tend to renew — creating incumbency advantages for early movers. Conversely, mobile-only vendors face commoditization risk on X-ray and ultrasound as handheld platforms proliferate.
Regulatory compliance is non-negotiable: FDA performance standards for mobile/portable X-ray, state-level radiation-control registration (varying by state), and cybersecurity mandates for connected endpoints all affect deployment timelines. Operators should budget 6–9 months for multi-state compliance onboarding. The gap hook: while this overview covers structural drivers and vendor positioning, precise fleet-level ROI modeling and state-by-state reimbursement mapping require the full report's segment forecasts.
The balance of evidence favors a mobile-first growth thesis inside a fixed-dominated market. The 1.89% blended CAGR is real but misleading; it describes a mature fixed-asset replacement economy wrapped around a 4–6% mobile services engine. Investors who underwrite the blended number will systematically undervalue the mobile segment.
The strongest counter-argument: mobile economics are fragile — capital intensity (USD 2M+ per MRI unit), technologist scarcity, and transport/maintenance drag can erode margins faster than volume grows. If hospital-at-home reimbursement contracts (2025 Medicare PFS parity) fail to broaden beyond pilot geographies, mobile growth reverts toward the low single digits and the barbell collapses. This is a legitimate risk, and it is why contract durability — not unit growth — should be the primary diligence filter.
Actionable strategy:
What would change our conclusion: A material reversal or non-renewal of hospital-at-home reimbursement codes, or a sustained >10% annual rise in certified mobile technologist wages, would push mobile growth below 3% and favor fixed incumbents. Conversely, FDA clearance of shielded-room-free MRI at scale would unlock step-change mobile MRI economics.
| Region | Market Share (%) |
|---|---|
| United States | 0.78% |
| Canada | 0.15% |
| Mexico | 0.07% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 1.89% from 2020-2034 |
| Segmentation |
|
The combined market was estimated at USD 109.1 billion in 2024, growing at roughly 1.89% annually through 2030. Fixed radiology dominates revenue, while mobile and interim imaging services grow faster at 4–6% depending on modality and setting.
PET/CT is the fastest-growing mobile modality at roughly 5.6% CAGR, driven by oncology and cardiac procedure migration to mobile platforms. Home-healthcare providers are the fastest-growing end-use channel at approximately 5.55% CAGR.
The United States leads with roughly 78% of North American services revenue, followed by Canada (~15%) and Mexico (~7%). U.S. dominance reflects reimbursement depth, chronic-disease burden, and rural access gaps.
High capital costs (mobile MRI exceeds USD 2 million), a shortage of certified mobile technologists, and radiation-compliance hurdles are the primary restraints. These are supply-side constraints rather than demand limitations.
The 2025 Medicare Physician Fee Schedule grants parity for remote supervision of diagnostic procedures, removing financial deterrents. This accelerates mobile imaging diffusion into suburban and rural counties and improves revenue visibility for mobile fleet operators.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the imaging services value chain, including mobile fleet operators, hospital radiology department administrators, diagnostic imaging center executives, OEM-affiliated service providers, and home-healthcare providers. Decision-maker designations interviewed include VP of Radiology Operations, Directors of Diagnostic Imaging, Heads of Mobile Imaging Fleets, and Commercial Operations Leads, ensuring coverage of both procurement and clinical-operations perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Radiology Operations Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Clinical & Quality Heads | 20% |
| Commercial & Strategy Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Mobile Fleet Operators | 40% |
| Hospital & Health Systems | 30% |
| Diagnostic Imaging Centers | 20% |
| OEM-Affiliated Service Providers | 10% |
We triangulate against official multilateral and regulatory databases — UN Comtrade, WTO trade statistics, US ITC data, and Eurostat — alongside corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases, and recognized standards bodies including the FDA (mobile/portable X-ray performance standards) and the International Electrotechnical Commission (IEC 60601 series). Non-profit technical associations such as the American College of Radiology and the Radiological Society of North America inform clinical-utilization benchmarks.
We run simultaneous top-down (macroeconomic healthcare expenditure and imaging segment allocation) and bottom-up (fleet capacity, procedure pricing, and end-use consumption modeling) triangulation. Divergences between the two approaches are reconciled against reimbursement code volume data and published procedure counts.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |