 Thermal Imaging Market
 Size, Share & Forecast to 2033
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 242

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Thermal Imaging Market
Amit Mardhekar
Research Analyst

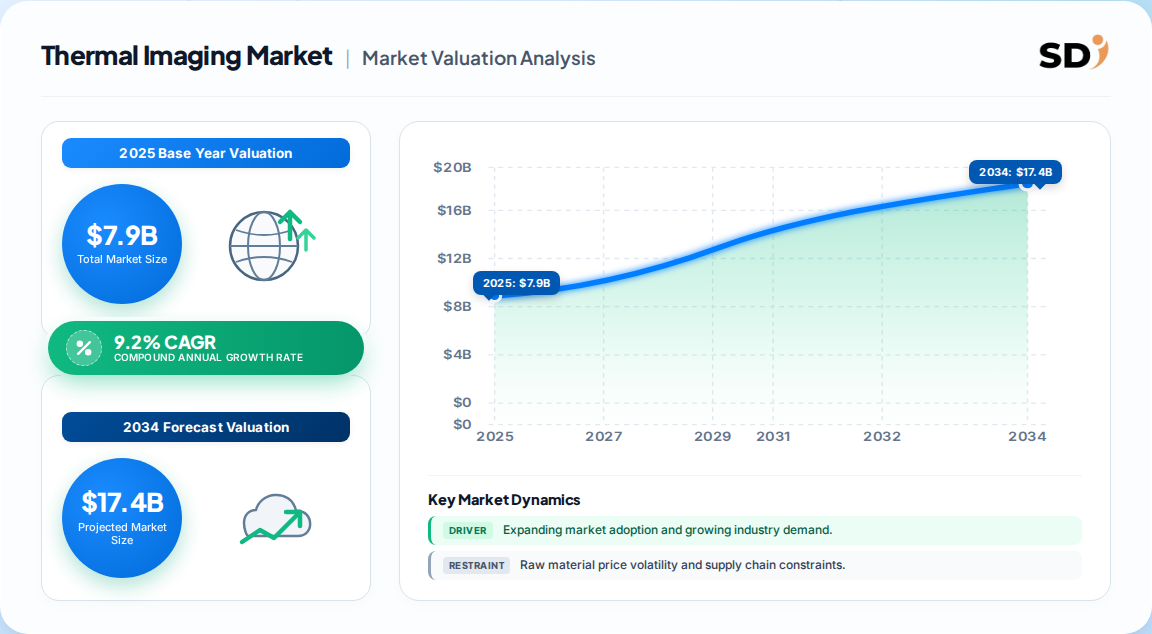
| Year | Market Size |
|---|---|
| 2025 | 7.900 B |
| 2026 | 8.700 B |
| 2027 | 9.500 B |
| 2028 | 10.40 B |
| 2029 | 11.30 B |
| 2030 | 12.30 B |
| 2031 | 13.50 B |

The thermal imaging market covers devices and software that convert emitted infrared radiation into visible thermal maps, spanning cooled photon detectors and uncooled microbolometers across handheld, fixed, airborne, and platform-integrated configurations. It is measured here by vendor revenue for cameras, cores, optics, and associated analytics sold into defense, industrial, commercial, and public-safety end uses.
This analysis covers the global thermal imaging equipment and software market across military and defense, industrial inspection, commercial surveillance, residential, healthcare, and automotive sensing applications. It includes cooled and uncooled detector architectures and hardware, software, and service components. This analysis does not cover standalone visible-light cameras, LiDAR, night-vision image-intensifier tubes sold as independent products, or the broader semiconductor equipment market.
Published estimates diverge sharply because analysts define the category boundary differently — some count platform-integrated sensor value, others only stand-alone camera sales. The table below isolates the benchmark most defensible for procurement planning.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 7.9B → 16.6B | 2025 | 2033 | 9.2% | Camera hardware plus core/optics revenue; defense-weighted | One published estimate (secondary) |
| USD 14.9B → 41.3B | 2025 | 2035 | 10.8% | Broader platform-architecture and integration value included | A competing analysis (secondary) |
| USD 5.8B → 11.21B | 2025 | 2035 | 6.81% | Narrower end-use classification, cooled-skewed | A third analysis (secondary) |
Our analysis suggests the 9.2% trajectory is the most defensible planning base. It sits between the narrowest and broadest definitions, and its 2025 value implies a hardware-revenue boundary consistent with disclosed vendor top lines. The 14.9B figure likely embeds platform integration value that double-counts prime-contractor content; the 5.8B figure understates commercial surveillance, which is the fastest-compounding volume pool.
The market splits on technology architecture, application, component, and end use — each cut carries a different margin and qualification burden, so segmentation matters operationally, not just descriptively.
| Parent | Children |
|---|---|
| By Technology | Cooled thermal imaging; Uncooled thermal imaging; Long-wave infrared imaging |
| By Application | Military & defense; Industrial; Healthcare; Building inspection; Surveillance |
| By Component | Hardware; Software; Services |
| By End Use | Commercial; Residential; Government; Healthcare |
Military & defense captured over 46% of 2025 revenue, while healthcare and commercial are the fastest-growing applications. This divergence implies procurement cycles, not technology novelty, will pace supplier revenue timing.
North America leads the global thermal imaging market with 33% of 2025 revenue, driven by U.S. Army sensor modernization, DHS fire-service procurement, and a dense industrial inspection base. Asia Pacific is the fastest-growing region on domestic defense programs and low-cost production scale.
| Region | Market Share (%) |
|---|---|
| North America | 0.33% |
| Europe | 0.23% |
| Asia-Pacific | 0.28% |
| Middle East & Africa | 0.08% |
| Latin America | 0.08% |
| Region | 2025 Share |
|---|---|
| North America | 33% |
| Asia Pacific | 28% |
| Europe | 23% |
| Middle East & Africa | 8% |
| Latin America | 8% |
Europe's share is held back by fragmented defense procurement, while China's domestic detector ecosystem compresses import pricing across Asia Pacific. Our analysis implies North American leadership persists through the 2033 horizon, but the growth contribution mix tilts decisively toward Asia Pacific after 2028.
Defense-platform standardization and uncooled sensor cost deflation are the dominant drivers, while cooled-system cost and qualification length are the binding restraints. Net balance favors growth, but unevenly across segments.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Defense modernization, multi-platform sensor standardization | Positive | High | Common architectures extend revenue tails across vehicle and soldier programs |
| Counter-drone and persistent maritime surveillance | Positive | High | Layered detection mandates thermal as a non-substitutable channel |
| Uncooled microbolometer cost decline | Positive | High | Removes cryogenic subsystem; enables handheld, connected, automotive volume |
| Automotive night perception and ASIL-rated fusion | Positive | Medium | Design-in cycles create durable but slow-ramping revenue |
| Cooled-system cost and SWaP-c constraints | Negative | High | Limits adoption outside defense and premium industrial |
| Lengthy defense and automotive qualification cycles | Negative | Medium | Delays revenue conversion despite strong design pipelines |
FLIR Systems, Fluke Corporation, BAE Systems, Leonardo DRS, and L3Harris collectively held roughly 56% of 2025 revenue, with FLIR alone at over 17.5%. The field is moderately concentrated, and no single vendor controls detector supply.
| Vendor | Primary Position | Moat |
|---|---|---|
| FLIR Systems (Teledyne) | Broadest commercial and defense portfolio | Vertical detector integration; installed base; brand |
| Fluke Corporation | Industrial inspection and test instruments | Channel density; calibration ecosystem |
| BAE Systems Imaging Solutions | Military-grade detectors and sensors | Qualified supply; defense relationships |
| Leonardo DRS | Soldier systems and vehicle sights | Program-of-record incumbency |
| L3Harris Technologies | Electro-optical and IR payloads | Platform integration; security-of-supply credentials |
Differentiation increasingly rests on qualification credentials and software, not raw detector resolution. Vendors lacking ASIL or military qualification face commoditization in uncooled handhelds where Chinese detector makers are compressing pricing.
Selection should be driven by operating condition, not headline resolution. Buyers evaluating fire-service or industrial inspection devices should benchmark smoke penetration, thermal sensitivity, and replacement budget; DHS survey pricing for fire-service cameras ranged USD 2,949 to USD 8,601, reflecting a mature category where usability outscores maximum detection range.
Defense and platform integrators face a different calculus. Qualification cycles are long, so switching suppliers mid-program carries severe schedule risk; security-of-supply credentials and export-control posture become binding. Integration cost, not unit price, dominates total cost of ownership.
Regulatory compliance matters on both flanks: export controls govern defense-grade cooled systems, while functional-safety standards such as ISO 26262 govern automotive thermal design-ins. Operators should contract for calibration cadence and software update rights, since analytics now carry a meaningful share of lifecycle value.
The balance of evidence favors a dual-economics market rather than a single growth curve. Defense programs establish a high-value floor for cooled and qualified uncooled detectors, while automotive, inspection, and public safety expand the installed base for low-power architectures. Suppliers optimized only for defense will miss the volume pool; suppliers optimized only for commercial handhelds will be exposed to detector price deflation.
The strongest counter-argument is that automotive thermal adoption could stall on OEM program timing and cost-per-vehicle pressure, collapsing the most-hyped growth pillar. If ASIL-rated thermal design-ins slip past 2029, the 9.2% CAGR would likely drift toward the 7% band, with defense carrying a disproportionate share of growth.
What would change our conclusion: sustained evidence that automotive thermal programs reach volume production before 2029, or that uncooled pricing stabilizes rather than deflates. This overview frames the strategic picture; precise segment-level and country-level forecasting requires the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.2% from 2020-2034 |
| Segmentation |
|
The market is expanding at 9.2% CAGR from 2026 to 2033, reaching USD 16.6 billion by 2033 from a 2025 base of USD 7.9 billion.
Military and defense held over 46% of 2025 revenue, supported by vehicle sights, soldier systems, and surveillance platforms.
Asia Pacific is the fastest-growing region, driven by defense modernization and competitive domestic detector production.
FLIR Systems holds over 17.5% share; the top five vendors together account for roughly 56% of revenue.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Fieldwork comprised in-depth interviews with stakeholders across the thermal imaging value chain: detector and microbolometer suppliers, optics and core assembly specialists, OEM camera producers, platform integrators, and authorized distributors. Interviewees were drawn from decision-maker designations including VP-level Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring demand-side validation of both pricing and qualification realities.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory Affairs Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Detector & Core Suppliers | 40% |
| OEM Camera Producers | 30% |
| Platform Integrators | 20% |
| Distributors & Traders | 10% |
Findings were cross-checked against official multilateral trade databases (UN Comtrade, Eurostat, US ITC), corporate annual filings and investor presentations (10-K, SEC disclosures), patent databases, and recognized technical standards bodies and industry associations covering electro-optical and infrared systems. Public defense procurement disclosures and government market surveys provided independent pricing benchmarks.
Market sizing triangulates a Top-Down allocation from macroeconomic and industry-segment spending with a Bottom-Up model built from manufacturer capacity, product pricing, and end-use consumption. Both models are reconciled at the base year before compounding forward using historical CAGR, regression analysis, and demand elasticity for defense and commercial pools separately.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |