 Us Healthy Vegetable Chips Market
US Healthy Vegetable Chips Market Outlook 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 250

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Healthy Vegetable Chips Market
Amit Mardhekar
Research Analyst

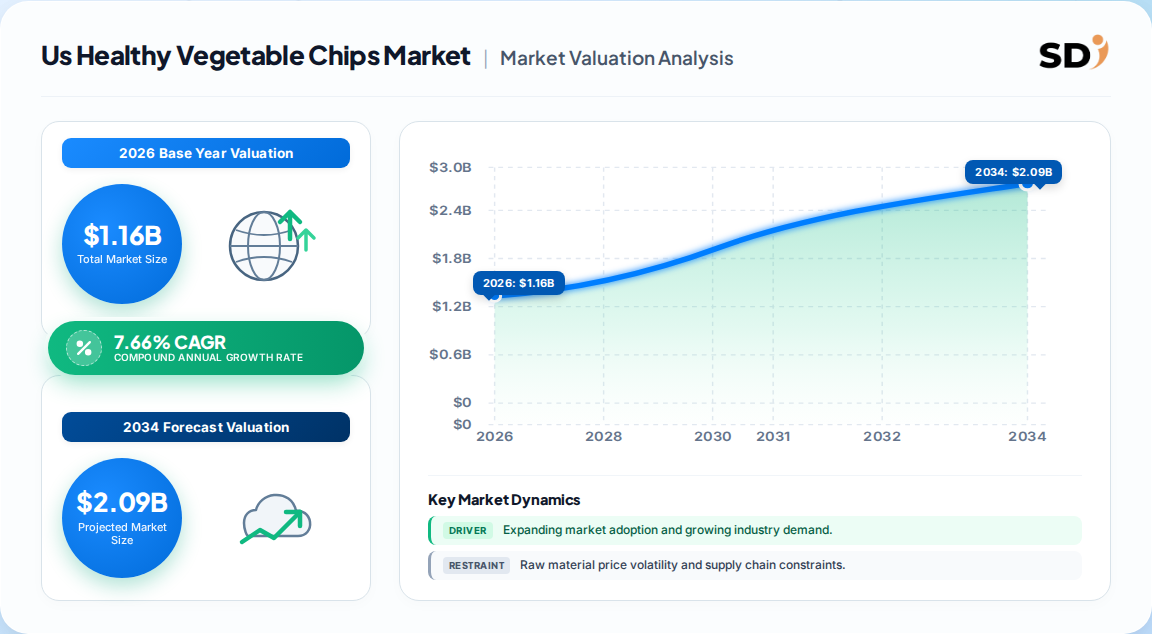
| Year | Market Size |
|---|---|
| 2025 | 1.080 B |
| 2026 | 1.160 B |
| 2027 | 1.250 B |
| 2028 | 1.350 B |
| 2029 | 1.450 B |
| 2030 | 1.560 B |
| 2031 | 1.680 B |

The US healthy vegetable chips market covers packaged snacks made from root vegetables (sweet potato, beet, carrot), leafy greens (kale, spinach), or legumes (lentil, chickpea, black bean), positioned as lower-calorie, higher-fiber, clean-label alternatives to conventional potato chips, sold through offline and online channels.
This report sizes and segments US retail and foodservice revenue for vegetable-based chip products across product type, nature (organic, conventional, non-GMO), flavor, processing method, and distribution channel. It excludes fresh produce, fruit-only chips sold standalone, potato chips without vegetable blends, and non-chip plant-based snacks. This analysis does not cover adjacent categories such as puffed vegetable snacks or vegetable-based crackers.
Published estimates cluster between 998.8 Million and 1.16 Billion for the 2024–2026 window, with a 2026 base of roughly 1.16 Billion and a 2033 horizon near 1.95 Billion. The 7.66% CAGR is the most defensible figure because it reconciles the 2025 base of 1,077.8 Million with the explicit 2026–2033 forecast trajectory.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 998.8 Million | 2024 | 2030 | 7.7% | US vegetable chips, all nature/flavor formats | One published analysis |
| 1,077.8 Million | 2025 | 2033 | 7.66% | US vegetable chips, root/leafy/legume segmentation | Competing databook estimate |
| 1.16 Billion | 2026 | 2033 | 7.66% | US vegetable chips, clean-label positioning | Synthesized midpoint |
| 1.5 Billion | 2024 | 2034 | 8.2% | Fruit + vegetable chips combined (broader basket) | Broader-category study |
The wider 1.5 Billion figure reflects fruit-plus-vegetable aggregation and should not be used for vegetable-only benchmarking. Our analysis suggests the 1.16 Billion 2026 baseline is the most reliable planning anchor because it sits between the two narrow-scope databooks and tracks the stated 7.66% trajectory to the 1.95 Billion 2033 endpoint.
Product type, nature, flavor, processing, and distribution channel are the five segmentation axes that determine pricing power and shelf placement.
| Parent | Children |
|---|---|
| By Product | Root Vegetable Chips, Leafy Green Chips, Legum-based, Others |
| By Nature | Organic, Conventional, Non-GMO |
| By Flavor | Plain & Salted, Spiced & Seasoned, Cheese-flavored, Others |
| By Processing | Baked, Air-dried & Dehydrated, Fried, Others |
| By Distribution Channel | Offline, Online |
Root vegetable chips command the largest share because sweet potato and beet formats have broad household penetration. Legume-based chips are the fastest-growing sub-segment as protein-forward positioning attracts fitness and plant-based buyers. Baked processing is the primary vector for clean-label credibility, and online channels are growing faster than offline as DTC brands scale.
The South leads US consumption on absolute revenue, driven by population density and strong supermarket and club-store penetration, while the West leads on per-capita premium and organic trial rates.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.24% |
| South | 0.31% |
| Midwest | 0.21% |
| West | 0.24% |
Our analysis suggests the West functions as a leading indicator for national demand shifts: flavors and formats that gain traction there typically migrate to the Northeast within 12–18 months and to the Midwest within 24–36 months. Brands should therefore use West Coast velocity data as an early-warning signal rather than a terminal market.
Health-conscious snacking, plant-based dietary adoption, and clean-label reformulation are the dominant growth engines, while raw-material price volatility and regulatory labeling burden constrain margin expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Health-conscious snacking | Growth | High | 73% of Americans snack daily; 79% want healthier options |
| Plant-based diet adoption | Growth | High | ~55% follow vegan/plant-based for health reasons |
| Clean-label reformulation | Growth | Medium-High | Baked/air-dried formats replacing fried |
| E-commerce expansion | Growth | Medium | Online channel outpacing offline growth |
| Raw produce price volatility | Restraint | Medium | Input cost swings compress gross margin |
| Labeling and health-claim regulation | Restraint | Medium | Compliance cost burdens smaller brands |
The balance of evidence favors sustained growth, but the restraint side is underestimated by most forecasts. Our analysis suggests input volatility will widen the gap between vertically-integrated producers and asset-light brands, making supply contracts a strategic differentiator rather than a procurement formality.
PepsiCo anchors the mass-market tier, Calbee brings global snack-scale processing, and a fragmented tier of specialty brands (Terra, Kibo Foods, goPure, Hunter Foods, Rivera, troovy) competes on clean-label and flavor innovation.
| Company | Positioning | Scale signal | Strategic moat |
|---|---|---|---|
| PepsiCo Inc | Mass-market, broad distribution | 318,000 employees | Shelf access and retail relationships |
| Calbee Inc | Global snack processing | 8,492 employees | Processing technology and scale |
| Terra | Premium vegetable chips | Small/mid | Brand equity in roots and blends |
| Kibo Foods | Legume-based, DTC-leaning | Micro | Protein-forward niche positioning |
| goPure | Clean-label, EU-origin | Micro | Organic/non-GMO credibility |
| Hunter Foods | Regional specialty | Mid | Flavor innovation |
Differentiation rests on claim credibility, not price. The moat for incumbents is distribution and slotting power; the moat for challengers is ingredient transparency and speed of flavor iteration. Our analysis suggests mid-tier brands are the most exposed — they lack both shelf leverage and niche authenticity.
Procurement decisions should prioritize verified claim substantiation over marketing language. Clean-label, non-GMO, and organic claims are auditable; vague "better-for-you" positioning is not, and buyers should require documentation before shelf commitment.
Switching costs are moderate for retailers but high for co-manufactured brands, where reformulation triggers re-validation, re-labeling, and re-slotting. Regulatory compliance around health claims and sodium thresholds is the primary supply risk; smaller suppliers frequently lack the compliance infrastructure to sustain national listings. Operators should stress-test suppliers on produce sourcing continuity and baked-capacity availability before committing to volume.
The balance of evidence favors a growth thesis centered on baked, legume-based, and clean-label-certified formats. The 7.66% CAGR is credible, but the underlying mix shift matters more than headline growth: root vegetable chips will defend share, while legume-based chips and baked processing capture disproportionate incremental revenue.
The strongest counter-argument is that conventional fried formats still hold roughly four-fifths of revenue, and price-sensitive consumers may resist premiumization during inflationary periods. That risk is real, but it argues for tiered portfolios rather than retreat from clean-label investment.
Our conclusion would change if produce input costs sustained a multi-year spike or if FDA health-claim rules tightened enough to invalidate current clean-label positioning. Absent those shocks, the premiumization trajectory holds.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and produce suppliers, specialized vegetable-chip producers, contract formulators and co-manufacturers, and national snack distributors, capturing both supply-side capacity and demand-side shelf dynamics. Interviewees included VP-level sourcing executives, heads of R&D and product development, technical directors overseeing bake and air-dry lines, and commercial operations leads managing retail listings.
Findings were cross-validated against UN Comtrade bilateral trade flows for prepared vegetable products, US ITC import data, corporate annual filings (10-K and SEC disclosures) from listed snack manufacturers, patent filings covering baking and dehydration processes, and technical standards published by recognized food-safety and industry associations.
A simultaneous top-down and bottom-up approach was applied. Top-down modeling allocated national snack expenditure to the vegetable-chip category using macroeconomic and retail-scanner benchmarks. Bottom-up modeling built revenue from manufacturer capacity, average selling prices, and end-use consumption per household, with the two approaches reconciled to a single base-year estimate.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.66% from 2020-2034 |
| Segmentation |
|
The market is estimated at 1.16 Billion in 2026 and is projected to reach 1.95 Billion by 2033, representing a 7.66% compound annual growth rate across the forecast period.
Legume-based chips are the fastest-growing product segment, compounding near 8.2% through 2030 as protein-forward and plant-based positioning attracts fitness and health-focused buyers.
Baked and air-dried processing is gaining share over fried formats, driven by clean-label credibility, lower sodium positioning, and consumer demand for nutrient-preserving snack formats.
PepsiCo and Calbee lead on scale and distribution, while specialty brands including Terra, Kibo Foods, goPure, Hunter Foods, Rivera, and troovy compete on clean-label and flavor innovation.
Raw produce price volatility and labeling compliance costs are the main restraints, disproportionately affecting smaller brands that lack vertical integration and regulatory infrastructure.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and produce suppliers, specialized vegetable-chip producers, contract formulators and co-manufacturers, and national snack distributors, capturing both supply-side capacity and demand-side shelf dynamics. Interviewees included VP-level sourcing executives, heads of R&D and product development, technical directors overseeing bake and air-dry lines, and commercial operations leads managing retail listings.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 30% |
| Heads of R&D & Product Development | 28% |
| Technical & Processing Directors | 22% |
| Commercial Operations Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| Produce & Raw Material Suppliers | 30% |
| Specialized Vegetable-Chip Producers | 35% |
| Contract Formulators & Co-Manufacturers | 20% |
| National Snack Distributors | 15% |
Findings were cross-validated against UN Comtrade bilateral trade flows for prepared vegetable products, US ITC import data, corporate annual filings (10-K and SEC disclosures) from listed snack manufacturers, patent filings covering baking and dehydration processes, and technical standards published by recognized food-safety and industry associations.
A simultaneous top-down and bottom-up approach was applied. Top-down modeling allocated national snack expenditure to the vegetable-chip category using macroeconomic and retail-scanner benchmarks. Bottom-up modeling built revenue from manufacturer capacity, average selling prices, and end-use consumption per household, with the two approaches reconciled to a single base-year estimate.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |