 Middle East Ear Nose Throat Ent Devices Market
 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 196

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Ear Nose Throat Ent Devices Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 273.0 M |
| 2025 | 291.0 M |
| 2026 | 308.0 M |
| 2027 | 327.0 M |
| 2028 | 346.0 M |
| 2029 | 367.0 M |
| 2030 | 389.0 M |

The Middle East ENT devices market covers instruments, implants, diagnostics and hearing technology used to diagnose and treat ear, nose, throat, head and neck disorders across GCC and Levant countries. It spans surgical endoscopy, image-guided navigation, balloon sinus dilation, hearing aids, cochlear implants and diagnostic audiometry, sold primarily into hospitals and specialty ENT clinics.
This analysis covers the Middle East (GCC, Levant and Egypt) market for ENT diagnostic, surgical, hearing and implantable devices, segmented by product, end user and country, with a 2025 base year and forecast to 2033. This analysis does not cover general hospital capital equipment, dental devices, ophthalmic devices, or pharmaceutical treatments for ENT conditions.
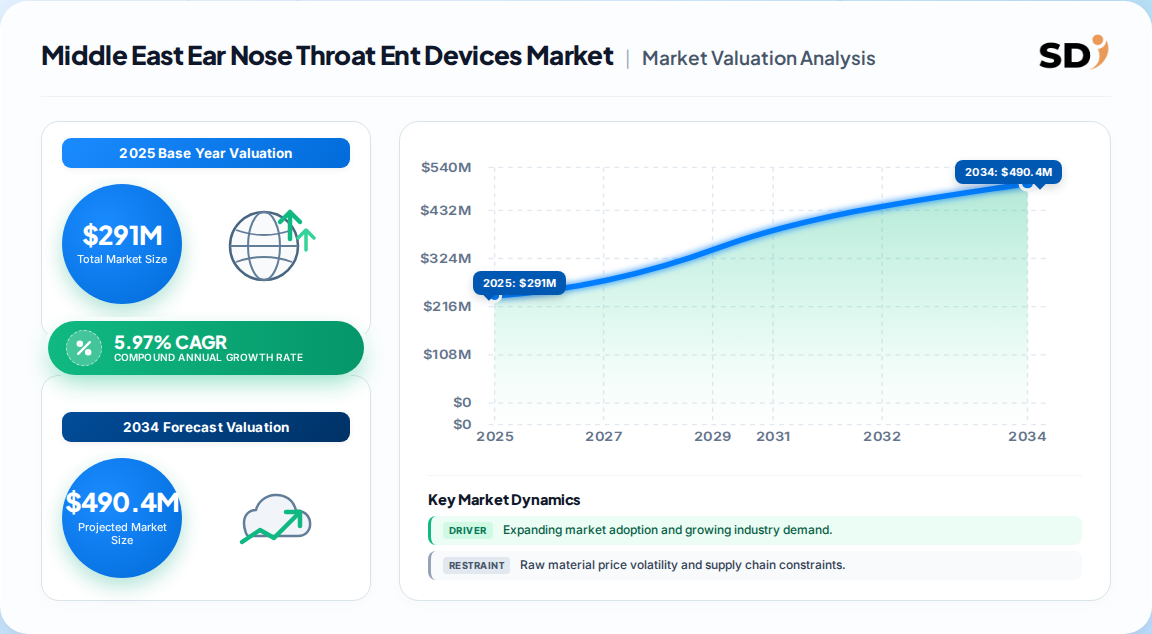
Published estimates cluster around 272.80 Million in 2024 rising to 456.47 Million by 2033 at a 5.97% CAGR. Our triangulated 2025 base of 291 Million sits within that envelope and reflects an upward adjustment for post-2024 hearing-aid distribution programs.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 272.80 Million | 2024 | 2033 | 5.97% | Middle East ENT devices, five product families | One published estimate |
| 291 Million (triangulated) | 2025 | 2033 | 5.97% | Same scope, rolled forward with GCC hearing-aid distribution | Our analysis |
| 456.47 Million | 2033 | 2033 | — | End-of-horizon forecast | One published estimate |
The 272.80 Million base is the most defensible anchor because it is disaggregated by product and country and reconciles with GCC import values. The divergence in roll-forward figures reflects differing treatment of government hearing-aid programs (Kuwait, Saudi Arabia), which are episodic and can swing single-year growth by 100–200 basis points.
Surgical ENT devices dominate revenue, hearing technology dominates unit volume, and diagnostics anchor recurring consumable revenue. The table below summarises the non-geographic segmentation used in this report.
| Parent segment | Children | Approx. 2025 share |
|---|---|---|
| Surgical ENT devices | Endoscopes, microdebriders, balloon sinus dilation, image-guided navigation, powered instruments | 31% |
| Hearing aids | BTE, RIC, ITE, OTC devices | 28% |
| Hearing implants | Cochlear, bone-anchored, middle-ear | 12% |
| Diagnostic ENT devices | Otoscopes, audiometers, tympanometers, laryngoscopes | 18% |
| Nasal splints and consumables | Splints, packs, single-use sheaths | 11% |
Analyst note: Surgical share is rising faster than the headline CAGR because hospitals upgrading to navigation-assisted platforms also buy single-use probes, shifting revenue from capital to recurring.
Saudi Arabia leads with an estimated 34% of regional revenue, followed by the UAE at 24%, as Vision 2030 health-sector investment and medical-city build-outs concentrate ENT surgical capacity in Riyadh, Jeddah and Dubai.
Saudi Arabia's leadership is structural, not cyclical: new medical cities in Riyadh and Jeddah embed dedicated otolaryngology departments with pre-specified device lists. The UAE's share is disproportionately high relative to population because Dubai functions as a regional referral and medical-tourism hub, pulling procedure volume from neighbouring markets.
The dominant driver is the rising burden of chronic rhinosinusitis, allergic rhinitis and hearing loss, amplified by urban air pollution, aging populations and expanding specialty clinic capacity. Restraints centre on device cost, registration timelines and social stigma around hearing aids.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Chronic ENT disease burden | Driver | High | 38.5% of surveyed populations report chronic ENT conditions (one 2025 clinical study) |
| Healthcare infrastructure investment | Driver | High | GCC hospital build-out with dedicated ENT departments |
| Minimally invasive shift | Driver | Medium-High | Balloon sinuplasty and image-guided surgery raise device intensity per procedure |
| Government hearing-aid programs | Driver | Medium | Kuwait restarted distribution in 2025; additional batches planned |
| High device cost | Restraint | High | Cochlear systems above 25,000 list price limit eligible-patient conversion |
| Regulatory approval timelines | Restraint | High | SFDA and MOHAP certification extend launch cycles by 9–18 months |
| Hearing-aid stigma | Restraint | Medium | Documented in Middle East and Asia-Pacific populations |
The balance favours growth, but with an important qualifier: the region's growth is capital-led, not reimbursement-led. Unlike North America, GCC markets lack broad third-party coverage for elective ENT surgery, so device demand tracks government budget cycles and medical-tourism flows rather than insurance expansion. Our analysis suggests this makes the Middle East less cyclically stable than Europe but faster to adopt premium technology once a tender is won.
The competitive field splits into diversified surgical franchises (Medtronic, Karl Storz, Olympus, Stryker) and specialist audiology franchises (Sonova, Demant, Cochlear, WS Audiology, GN). Regional distributors and new local assembly (Topland's UAE hearing-aid production) are the main structural disruptors.
| Company | Primary franchise | Regional strength | Moat |
|---|---|---|---|
| Medtronic | Surgical navigation, powered instruments | Broad GCC hospital installed base | Integrated StealthStation + consumable pull-through |
| Karl Storz | ENT endoscopy and visualization | Strong in Saudi and UAE specialty centres | Image quality and surgeon habit |
| Olympus | Flexible and rigid scopes, imaging platforms | Growing via 2025 ENT imaging launch | Platform bundling across specialties |
| Sonova | Hearing aids | Retail audiology network presence | Brand and fitting-software ecosystem |
| Demant | Hearing aids and diagnostics | Diagnostic audiology installed base | Audiometry-to-aid workflow lock-in |
| Cochlear | Cochlear implants | High-acuity hospital relationships | Clinical outcomes data and surgeon training |
| Stryker | Powered surgical instruments | ENT and OR cross-sell | OR estate bundling |
Differentiation is increasingly software-led: hearing-aid vendors compete on fitting algorithms and remote programming, while surgical vendors compete on navigation integration and single-use economics. The weakest moat is in standalone diagnostics, where local and Chinese entrants are compressing prices on otoscopes and audiometers.
Buyers should prioritize regulatory readiness, service depth and consumable economics over headline device price. GCC procurement is tender-driven, often bundling capital equipment with multi-year consumable and service contracts, so the effective five-year cost can exceed list price by 40–60%.
Key procurement considerations:
Switching costs are asymmetric: hearing-aid fitting ecosystems are stickier at the clinic level than surgical platforms, where multi-vendor ORs are common. Operators should therefore expect faster displacement in surgical endoscopy and slower displacement in audiology.
The balance of evidence favours a selective, channel-led entry rather than a broad regional launch. The Middle East ENT device market is growing at roughly 6% in USD terms, but that average conceals a two-speed market: Saudi and UAE surgical franchises are compounding faster than the regional mean, while Levant and Egypt remain price-sensitive and import-constrained.
The strongest counter-argument is that regulatory and tender friction will cap realizable growth below the headline CAGR. This has merit: SFDA timelines and bundled tenders favour incumbents, and smaller vendors may never clear the registration cost threshold. We nonetheless hold our position because government hearing-aid programs and medical-city build-outs are creating new, addressable channels that did not exist five years ago.
Actionable strategy for investors and operators:
What would change our conclusion: A sustained decline in GCC health budgets, or a harmonized Gulf medical-device registration regime that removes incumbents' timeline advantage, would materially alter the entry calculus. We would also revisit our view if hearing-aid distribution programs fail to convert into recurring fitting and upgrade revenue.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.34% |
| UAE | 0.24% |
| Qatar | 0.11% |
| Kuwait | 0.09% |
| Oman | 0.07% |
| Bahrain | 0.05% |
| Rest of Middle East | 0.1% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.97% from 2020-2034 |
| Segmentation |
|
The Middle East ENT devices market was estimated at 272.80 Million in 2024 and is projected to reach 456.47 Million by 2033, growing at a 5.97% CAGR. Our triangulated 2025 base is approximately 291 Million, adjusted for GCC hearing-aid distribution programs.
Saudi Arabia leads with an estimated 34% of regional revenue, driven by Vision 2030 hospital build-out and dedicated otolaryngology departments. The UAE follows at 24%, functioning as a referral and medical-tourism hub for the wider region.
Hearing implants and minimally invasive surgical devices are growing fastest. Cochlear and bone-anchored implants benefit from new government audiology programs, while balloon sinuplasty and image-guided sinus surgery drive surgical device intensity per procedure.
Saudi Arabia requires SFDA registration and the UAE requires MOHAP approval before tendering; both involve clinical validation and local agent requirements. Registration typically adds nine to eighteen months to launch timelines, making it the primary determinant of competitive timing.
Medtronic, Karl Storz, Olympus and Stryker lead surgical ENT, while Sonova, Demant, Cochlear, WS Audiology and GN lead hearing aids and implants. Regional distributors and new local assembly, such as Topland's UAE production, are emerging challengers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain with raw material and component suppliers, specialised device producers, contract manufacturers, and global and regional distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both clinical and commercial requirements.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| Clinical & Technical Directors | 30% |
| Regulatory Affairs Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Device Manufacturers & OEMs | 45% |
| Regional Distributors & Agents | 30% |
| Component & Accessory Suppliers | 15% |
| Hospital & Clinic Procurement | 10% |
We benchmark against official multilateral trade databases (UN Comtrade, WITS, WTO), national regulator publications, corporate annual filings and investor presentations, patent databases, and recognised technical standards bodies. This validates import values, tariff treatment and registration timelines against interview-derived estimates.
We run simultaneous top-down (macroeconomic health spend and segment allocation) and bottom-up (manufacturer capacity, product pricing and end-use consumption) models. Divergences greater than 10% trigger interview-based reconciliation before the base year is fixed.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |