Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Accelerometers Medical Sensors Market: 2025 Strategic Outlook
Accelerometers Medical Sensors Market
Accelerometers Medical Sensors Market: 2025 Strategic Outlook
Accelerometers Medical Sensors Market by Product (MEMS Accelerometers, Piezoelectric Accelerometers, Wearable, Non-Wearable), by Application (Fall Detection & Prevention, Activity Monitoring & Rehabilitation, Neurological Disorder Tracking, Implantable Devices & Smart Prosthetics, Vital Sign Integration), by End User (Hospitals & Specialty Clinics, Homecare Settings, Rehabilitation Centers, Wearable Device Manufacturers, Academic & Research Institutions), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 197
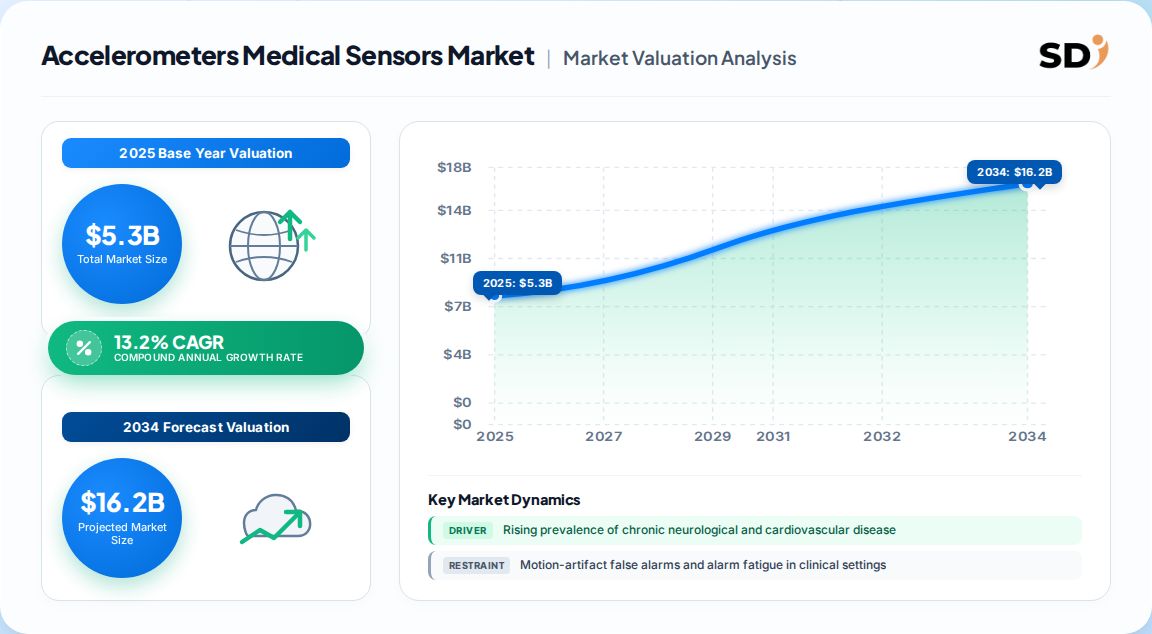
5.3 Billion — global accelerometer medical sensor market value in 2025, per one published estimate (base year 2025).
13.2% CAGR projected through 2033, with a competing analysis modeling 12.2% through 2032 — a meaningful divergence explored below.
Wearables dominate with more than 69% product share in 2025, followed by non-wearable clinical-grade sensor platforms.
North America leads at roughly 34% revenue share; Asia Pacific is the fastest-growing region at double-digit CAGR.
MEMS accelerometers command approximately 72% of product revenue, with piezoelectric units confined to high-precision clinical niches.
Key players include Analog Devices, STMicroelectronics, NXP, TDK InvenSense, Bosch Sensortec, Koninklijke Philips, ResMed, Fitbit and Garmin.
Why this matters for decision-makers: Vendors that fail to pair ultra-low-power MEMS hardware with AI-validated motion analytics will be squeezed into commodity pricing by 2030.
Accelerometers Medical Sensors Market Size (In Billion)
15.0B
10.0B
5.0B
0
5.300 B
2025
6.000 B
2026
6.800 B
2027
7.700 B
2028
8.700 B
2029
9.800 B
2030
11.10 B
2031
Accelerometers Medical Sensors Market Size (In Billion)
Year
Market Size
2025
5.300 B
2026
6.000 B
2027
6.800 B
2028
7.700 B
2029
8.700 B
2030
9.800 B
2031
11.10 B
What is the Accelerometers Medical Sensors Market?
The accelerometers medical sensors market covers regulated sensing components that measure acceleration, orientation and vibration inside medical devices — wearables, prosthetics, implants, rehabilitation platforms and multi-modal patient monitors — and the analytics layer that converts raw motion into clinically actionable output.
Scope: what this report covers and excludes
Scope spans wearable and non-wearable medical-grade accelerometers, MEMS and piezoelectric technologies, applications from fall detection to neurological tracking, and five end-user environments. This analysis does not cover general consumer fitness trackers without medical claims, automotive MEMS, aerospace inertial sensors, or industrial vibration monitoring.
How big is the market for Accelerometers Medical Sensors Market?
Estimates diverge materially: one published analysis puts 2025 at 5.3 Billion with a 13.2% CAGR to 14.4 Billion by 2033, while a competing study models 4.42 Billion in 2025 rising to 9.9 Billion by 2032 at 12.2% — and a third places 2024 at 3.4 Billion growing at 8.2% to 5.4 Billion by 2030.
MEMS + piezoelectric split; five application clusters; five end-user groups
A third published analysis
Our analysis suggests the 12–13% band is the most defensible: it aligns with the MEMS sensor shipment trajectory underpinning wearable volumes and with the post-2022 reimbursement expansion for remote monitoring. The 8.2% figure likely reflects a narrower application taxonomy and conservative homecare assumptions.
How is the market segmented?
Segmentation is organized around four non-geographic axes — product technology, clinical application, end-user environment and motion-data maturity — each carrying distinct margin and regulatory profiles.
MEMS holds roughly 72% of product revenue, while activity monitoring leads applications at about 28%. Neurological tracking is the fastest-growing cluster, driven by Parkinson's and epilepsy validation.
Which region leads in Accelerometers Medical Sensors Market?
North America leads with approximately 34% revenue share in 2025, anchored by CMS reimbursement for remote monitoring and early FDA clearance of accelerometer-based digital endpoints.
Accelerometers Medical Sensors Market Regional Market Share
Loading chart...
Accelerometers Medical Sensors Market Regional Market Share
Region
Market Share (%)
North America
0.34%
Europe
0.26%
Asia Pacific
0.22%
Latin America
0.09%
Middle East & Africa
0.09%
Global
North America (USA, Canada, Mexico)
Europe (Germany, UK, France, Italy)
Asia Pacific (China, Japan, India, South Korea)
Latin America (Brazil, Mexico, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
Europe follows at roughly 26%, supported by Germany's DiGA reimbursement pathway and NHS-backed post-surgical mobility trials. Asia Pacific at about 22% grows fastest, as Shenzhen, Seoul and Tokyo sensor hubs scale MEMS manufacturing. Latin America and MEA together hold the remaining share, with Brazil and the UAE as the most active adoption pockets.
What is driving growth — and what is holding it back?
Growth is powered by three reinforcing forces: chronic disease prevalence, reimbursement-backed remote monitoring, and sensor miniaturization paired with AI interpretation. Restraints are narrower but real — motion-artifact false alarms, regulatory gray zones and data-interpretation gaps inside care teams.
Factor
Direction
Evidence strength
Mechanism
Chronic disease & aging populations
Driver
High
Expands monitored patient pool for gait, tremor and fall-risk sensing
Remote monitoring reimbursement
Driver
High
Converts wearables from consumer to prescribable clinical tools
AI motion analytics & miniaturization
Driver
Medium-High
Improves diagnostic yield and enables implantable form factors
The balance clearly favors drivers. Our analysis suggests reimbursement clarity is the single largest swing variable — jurisdictions that codify motion-based endpoints will pull adoption forward by two to three years.
Who are the leading vendors?
Competitive leadership splits between precision sensor manufacturers and medical-device integrators: Analog Devices and STMicroelectronics control high-performance MEMS supply, while Philips, ResMed and wearable OEMs own the clinical channel.
Company
Positioning
Strategic edge
Analog Devices
Ultra-low-noise MEMS
FDA-cleared wearable and implantable design wins
STMicroelectronics
Multi-axis MEMS
Integration flexibility across biosignal platforms
NXP
Sensor fusion
Automotive-grade reliability transferred to medical
TDK InvenSense
High-volume MEMS
Edge AI processing on-chip
Bosch Sensortec
Miniaturized triaxial
Scalability and ruggedness for wearables
Koninklijke Philips
Clinical monitoring
Hospital channel and reimbursement relationships
ResMed / Somnomedics
Sleep & respiratory
Accelerometry embedded in sleep diagnostics
Fitbit / Garmin
Consumer-to-medical
Volume scale and CE-certified mobility features
Differentiation is shifting from sensor accuracy to clinical validation and analytics integration. Vendors lacking regulatory-cleared algorithms face pricing pressure from Asian MEMS producers.
What do buyers and operators need to know? (Decision Support)
Procurement decisions should weight four criteria above unit price: regulatory clearance status (FDA 510(k) or CE MDR), power consumption for multi-year implant or patch life, interoperability with EHR and remote-monitoring platforms, and the maturity of the vendor's motion-analytics layer. Switching costs are high once a sensor is designed into a cleared device, so qualification timelines of 12–24 months should be budgeted. Operators should also stress-test false-alarm rates and data-governance posture, because alarm fatigue and privacy breaches are the two failure modes most likely to erode clinician trust and reimbursement standing.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the higher-growth 12–13% CAGR band over the conservative 8.2% view. Reimbursement expansion and AI-validated motion endpoints are compounding faster than earlier models assumed, and the wearable segment's 69% share creates a demand flywheel that accelerates MEMS volume and cost reduction simultaneously.
The strongest counter-argument is that consumer-grade smartphones already embed accelerometers, potentially commoditizing simple activity tracking before medical-grade vendors capture value. That risk is real at the low end, but it does not extend to regulated endpoints — fall detection accuracy, seizure discrimination and implantable motion sensing remain defensible clinical moats.
Actionable strategy:
Sensor vendors should co-develop cleared analytics with medtech OEMs rather than sell components into a commoditizing MEMS market.
Investors should overweight neurological tracking and homecare platforms, the two fastest-compounding application and end-user clusters.
Operators should prioritize Asia Pacific manufacturing partnerships to defend margin against regional price competition.
Evidence that would change this conclusion: a sustained FDA or EU MDR tightening on wearable motion claims, or MEMS average selling prices falling faster than 8% annually, would compress the forecast toward the conservative band.
Accelerometers Medical Sensors Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Accelerometers Medical Sensors Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 13.2% from 2020-2034
Segmentation
By Product
MEMS Accelerometers
Piezoelectric Accelerometers
Wearable
Non-Wearable
By Application
Fall Detection & Prevention
Activity Monitoring & Rehabilitation
Neurological Disorder Tracking
Implantable Devices & Smart Prosthetics
Vital Sign Integration
By End User
Hospitals & Specialty Clinics
Homecare Settings
Rehabilitation Centers
Wearable Device Manufacturers
Academic & Research Institutions
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. MEMS Accelerometers
5.1.2. Piezoelectric Accelerometers
5.1.3. Wearable
5.1.4. Non-Wearable
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Fall Detection & Prevention
5.2.2. Activity Monitoring & Rehabilitation
5.2.3. Neurological Disorder Tracking
5.2.4. Implantable Devices & Smart Prosthetics
5.2.5. Vital Sign Integration
5.3. Market Analysis, Insights and Forecast - by End User
5.3.1. Hospitals & Specialty Clinics
5.3.2. Homecare Settings
5.3.3. Rehabilitation Centers
5.3.4. Wearable Device Manufacturers
5.3.5. Academic & Research Institutions
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. Latin America
5.4.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. MEMS Accelerometers
6.1.2. Piezoelectric Accelerometers
6.1.3. Wearable
6.1.4. Non-Wearable
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Fall Detection & Prevention
6.2.2. Activity Monitoring & Rehabilitation
6.2.3. Neurological Disorder Tracking
6.2.4. Implantable Devices & Smart Prosthetics
6.2.5. Vital Sign Integration
6.3. Market Analysis, Insights and Forecast - by End User
6.3.1. Hospitals & Specialty Clinics
6.3.2. Homecare Settings
6.3.3. Rehabilitation Centers
6.3.4. Wearable Device Manufacturers
6.3.5. Academic & Research Institutions
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. MEMS Accelerometers
7.1.2. Piezoelectric Accelerometers
7.1.3. Wearable
7.1.4. Non-Wearable
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Fall Detection & Prevention
7.2.2. Activity Monitoring & Rehabilitation
7.2.3. Neurological Disorder Tracking
7.2.4. Implantable Devices & Smart Prosthetics
7.2.5. Vital Sign Integration
7.3. Market Analysis, Insights and Forecast - by End User
7.3.1. Hospitals & Specialty Clinics
7.3.2. Homecare Settings
7.3.3. Rehabilitation Centers
7.3.4. Wearable Device Manufacturers
7.3.5. Academic & Research Institutions
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. MEMS Accelerometers
8.1.2. Piezoelectric Accelerometers
8.1.3. Wearable
8.1.4. Non-Wearable
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Fall Detection & Prevention
8.2.2. Activity Monitoring & Rehabilitation
8.2.3. Neurological Disorder Tracking
8.2.4. Implantable Devices & Smart Prosthetics
8.2.5. Vital Sign Integration
8.3. Market Analysis, Insights and Forecast - by End User
8.3.1. Hospitals & Specialty Clinics
8.3.2. Homecare Settings
8.3.3. Rehabilitation Centers
8.3.4. Wearable Device Manufacturers
8.3.5. Academic & Research Institutions
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. MEMS Accelerometers
9.1.2. Piezoelectric Accelerometers
9.1.3. Wearable
9.1.4. Non-Wearable
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Fall Detection & Prevention
9.2.2. Activity Monitoring & Rehabilitation
9.2.3. Neurological Disorder Tracking
9.2.4. Implantable Devices & Smart Prosthetics
9.2.5. Vital Sign Integration
9.3. Market Analysis, Insights and Forecast - by End User
9.3.1. Hospitals & Specialty Clinics
9.3.2. Homecare Settings
9.3.3. Rehabilitation Centers
9.3.4. Wearable Device Manufacturers
9.3.5. Academic & Research Institutions
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. MEMS Accelerometers
10.1.2. Piezoelectric Accelerometers
10.1.3. Wearable
10.1.4. Non-Wearable
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Fall Detection & Prevention
10.2.2. Activity Monitoring & Rehabilitation
10.2.3. Neurological Disorder Tracking
10.2.4. Implantable Devices & Smart Prosthetics
10.2.5. Vital Sign Integration
10.3. Market Analysis, Insights and Forecast - by End User
10.3.1. Hospitals & Specialty Clinics
10.3.2. Homecare Settings
10.3.3. Rehabilitation Centers
10.3.4. Wearable Device Manufacturers
10.3.5. Academic & Research Institutions
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Analog Devices Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. STMicroelectronics
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. NXP
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. TDK InvenSense
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Bosch Sensortec
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Koninklijke Philips N.V.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. ResMed
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Somnomedics
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Fitbit Inc
11.1.9.1. Company Overview
11.1.9.2. Products
12. Research Methodology
List of Figures
Figure 1: Accelerometers Medical Sensors Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Accelerometers Medical Sensors Market Revenue (Billion), by Product 2026 & 2034
Figure 3: North America Accelerometers Medical Sensors Market Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Accelerometers Medical Sensors Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Accelerometers Medical Sensors Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Accelerometers Medical Sensors Market Revenue (Billion), by End User 2026 & 2034
Figure 7: North America Accelerometers Medical Sensors Market Revenue Share (%), by End User 2026 & 2034
Figure 8: North America Accelerometers Medical Sensors Market Revenue (Billion), by Country 2026 & 2034
Figure 9: North America Accelerometers Medical Sensors Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Accelerometers Medical Sensors Market Revenue (Billion), by Product 2026 & 2034
Figure 11: Europe Accelerometers Medical Sensors Market Revenue Share (%), by Product 2026 & 2034
Figure 12: Europe Accelerometers Medical Sensors Market Revenue (Billion), by Application 2026 & 2034
Figure 13: Europe Accelerometers Medical Sensors Market Revenue Share (%), by Application 2026 & 2034
Figure 14: Europe Accelerometers Medical Sensors Market Revenue (Billion), by End User 2026 & 2034
Figure 15: Europe Accelerometers Medical Sensors Market Revenue Share (%), by End User 2026 & 2034
Europe Accelerometers Medical Sensors Market Revenue (Billion), by Country 2026 & 2034
List of Tables
Table 1: Accelerometers Medical Sensors Market Revenue Billion Forecast, by Product 2020 & 2034
Table 2: Accelerometers Medical Sensors Market Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Accelerometers Medical Sensors Market Revenue Billion Forecast, by End User 2020 & 2034
Table 4: Accelerometers Medical Sensors Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North America Accelerometers Medical Sensors Market Revenue Billion Forecast, by Product 2020 & 2034
Table 6: North America Accelerometers Medical Sensors Market Revenue Billion Forecast, by Application 2020 & 2034
Table 7: North America Accelerometers Medical Sensors Market Revenue Billion Forecast, by End User 2020 & 2034
Table 8: North America Accelerometers Medical Sensors Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: USA Accelerometers Medical Sensors Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Canada Accelerometers Medical Sensors Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Accelerometers Medical Sensors Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Europe Accelerometers Medical Sensors Market Revenue Billion Forecast, by Product 2020 & 2034
Table 13: Europe Accelerometers Medical Sensors Market Revenue Billion Forecast, by Application 2020 & 2034
Table 14: Europe Accelerometers Medical Sensors Market Revenue Billion Forecast, by End User 2020 & 2034
Table 15: Europe Accelerometers Medical Sensors Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1. How big is the accelerometers medical sensors market?
One published estimate values the global market at 5.3 Billion in 2025, projecting 14.4 Billion by 2033 at a 13.2% CAGR. A competing analysis places 2025 at 4.42 Billion with a 12.2% CAGR through 2032.
2. What is the fastest-growing segment in accelerometers medical sensors?
Neurological disorder tracking is the fastest-growing application, driven by Parkinson's tremor monitoring, epilepsy seizure detection and gait analysis. Wearables hold the largest product share at over 69% in 2025.
3. Which region dominates the accelerometers medical sensors market?
North America leads with roughly 34% revenue share in 2025, supported by CMS remote-monitoring reimbursement and early FDA clearances. Asia Pacific is the fastest-growing region on digital health investment and MEMS manufacturing strength.
4. What technologies underpin accelerometer medical sensors?
MEMS accelerometers represent about 72% of product revenue due to small form factor and low power draw. Piezoelectric variants hold roughly 28%, concentrated in high-precision clinical diagnostics and neurological monitoring equipment.
5. What are the main barriers to accelerometer adoption in healthcare?
Motion-artifact false alarms, regulatory gray zones between consumer and medical-grade wearables, and care-team difficulty interpreting continuous motion data all slow institutional adoption despite mature hardware.
6. Who are the leading companies in accelerometer medical sensors?
Analog Devices, STMicroelectronics, NXP, TDK InvenSense and Bosch Sensortec lead sensor supply, while Koninklijke Philips, ResMed, Fitbit and Garmin dominate clinical and wearable channels.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program follows a 70/30 primary-to-secondary split, with 70% of input drawn from direct fieldwork. We conducted in-depth interviews across the value chain: MEMS foundry and sensor fabricators, medical-grade module assemblers, wearable OEM integrators, contract manufacturers and global medical-device distributors. Decision-makers interviewed included VP-level Sourcing leads, Heads of R&D and Sensor Engineering, Technical Directors of clinical programs, and Commercial Operations Leads at wearable and monitoring platform vendors.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Sensor Engineering Heads
35%
Sourcing & Procurement Leads
30%
Clinical Program Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
MEMS Foundries & Sensor Fabricators
40%
Medical-Grade Module Assemblers
30%
Wearable OEM Integrators
20%
Distributors & Clinical Channel Partners
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate filings (SEC 10-K, annual investor presentations), patent databases tracking MEMS and motion-analytics IP, and recognized technical standards bodies including ISO, IEEE and IEC committees governing medical electrical equipment. Regulatory clearance registries (FDA 510(k), EU MDR) are used to validate device-level adoption claims.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macro healthcare spend, medical device segment allocation, wearable shipment forecasts) and Bottom-Up (manufacturer capacity, ASP trajectories, end-use consumption modeling) triangulation, reconciling divergence at the segment level rather than the aggregate level.
 Accelerometers Medical Sensors Market