 Uae Genetic Testing Market
UAE Genetic Testing Market: Size, CAGR & Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 257

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Uae Genetic Testing Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2022 | 29.00 M |
| 2023 | 36.00 M |
| 2024 | 43.00 M |
| 2025 | 52.00 M |
| 2026 | 64.00 M |
| 2027 | 77.00 M |
| 2028 | 94.00 M |

The UAE genetic testing market covers clinical and consumer laboratory services that analyse DNA, RNA or chromosomes to diagnose, predict or guide treatment of inherited and acquired disease. It spans NGS, PCR, array and cytogenetic techniques delivered through hospitals, diagnostic labs and direct-to-consumer channels across the Emirates.
This report covers revenue generated from genetic testing services and associated consumables in the United Arab Emirates across all seven Emirates, spanning molecular diagnostics, reproductive and predictive testing, and consumer genomics through 2033. This analysis does not cover pharmaceutical manufacturing, biobanking revenues, clinical trial services, or veterinary genetic testing, and excludes broader life-science instrumentation sales not associated with genetic assays.
Published estimates for this market diverge sharply because analysts use different definitions — clinical testing only versus all genomic services and consumer kits. The table below reconciles the available benchmarks.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
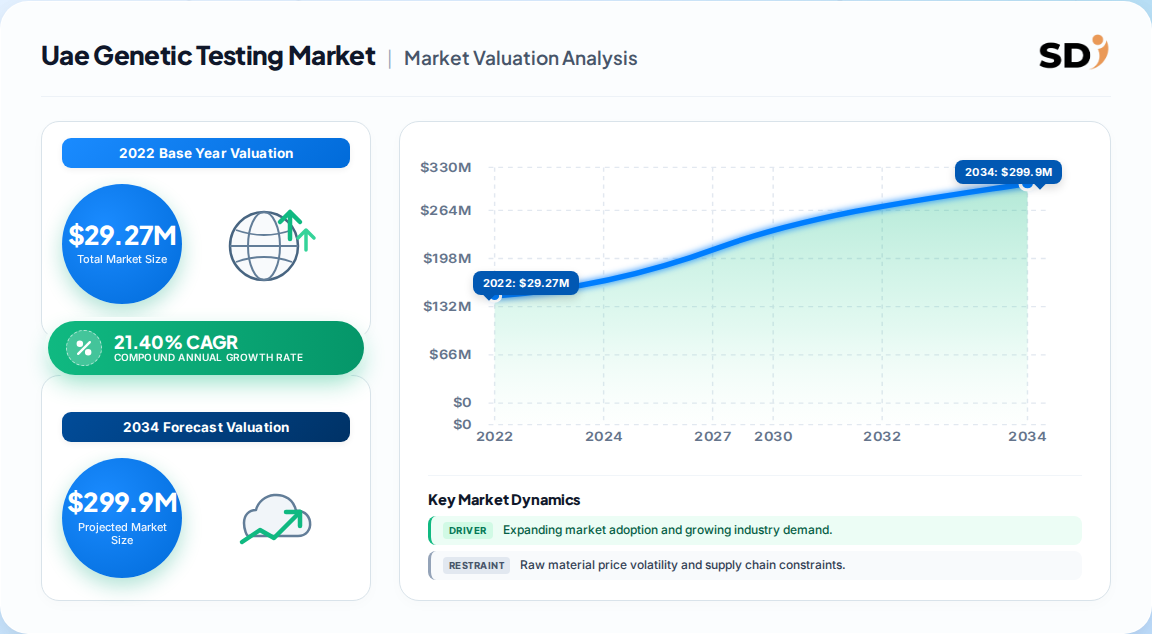
| USD 29.27 Million | 2022 | 2030 | 21.40% | Clinical genetic testing services, narrower assay scope | One published estimate |
| USD 657.52 Million | 2024 | 2033 | 9.76% | Broad genomic services incl. consumer, equipment-linked and wellness testing | A competing analysis |
| UAE ≈ 3.33% of global genetic testing | 2024 | 2033 | 9.76% | Regional share of a broader global genomic services definition | A competing analysis |
Our analysis suggests the clinical-scope figure (USD 29.27 Million) is the more defensible baseline for anyone procuring clinical genetic services, because it aligns with hospital and diagnostic-lab revenue recognised in the UAE. The larger estimate appears to bundle consumer genomics, wellness kits and equipment-linked spend, which inflates the base and dampens the implied growth rate. Buyers should treat the 21.40% CAGR as the planning anchor for clinical assay volumes and the 9.76% figure as a ceiling for the broader genomic ecosystem.
Segment definitions matter more here than in most diagnostics markets, because the same test can be classified by technique, application or channel. The non-geographic structure is summarised below.
| Parent segment | Children |
|---|---|
| By Technology | Next-generation sequencing, PCR, Array technology, Cytogenetics, Others |
| By Application | Ancestry & ethnicity, Oncology, Genetic disorder diagnosis, Predictive & presymptomatic, Prenatal & newborn, Pharmacogenomics, Cardiovascular, Neurological, Health & wellness |
| By Channel | Offline (hospital labs, private labs, pharmacies), Online / direct-to-consumer |
| By End-use | Hospitals, Diagnostic laboratories, Research & academic institutes, Others |
| By Test Type | Diagnostic, Carrier screening, Prenatal & newborn, Predictive & presymptomatic, Pharmacogenomic |
NGS dominates technology revenue at 46.30%, while ancestry sits surprisingly high at 50.72% of application revenue — a signal that consumer-facing demand is shaping volume even in a clinical-looking market. Hospitals absorb 61.37% of spend, and offline channels retain 55.29%, though online is the fastest-growing channel.
Dubai leads the UAE genetic testing market, followed by Abu Dhabi, with the two together accounting for the large majority of laboratory throughput and government-backed genomics activity. Sharjah and the Northern Emirates trail but are growing as private lab networks extend coverage.
| Emirate | Share of UAE genetic testing revenue |
|---|---|
| Dubai | 44% |
| Abu Dhabi | 29% |
| Sharjah | 9.5% |
| Northern Emirates (Ajman, RAK, Fujairah, UAQ) | 17.5% |
The concentration in Dubai and Abu Dhabi reflects where licensed molecular labs, hospital genomics departments and government programmes are physically sited. This implies a procurement reality: national tenders and insurer contracts are effectively won or lost in two Emirates before rural coverage is even considered.
The UAE genetic testing market is driven by a high inherited-disorder burden, government genomics investment and falling sequencing costs; it is restrained by counsellor shortages, reimbursement gaps and data-residency rules.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| High prevalence of congenital and genetic disorders | Driver | High | 241 documented genetic abnormalities nationally; congenital malformation is a leading cause of mortality |
| Government genomics and R&D programmes | Driver | High | National programmes compile genetic data for ethnic-specific precision medicine |
| Falling NGS cost and automation | Driver | Medium-high | Lower per-genome cost expands population-scale testing |
| Rising cancer burden and pharmacogenomics | Driver | Medium-high | Cancer incidence of 4,807 and mortality of 1,896 (WHO 2020) support testing volumes |
| Consumer wellness and ancestry demand | Driver | Medium | Direct-to-consumer kits reduce cost barriers and build awareness |
| Genetic counsellor shortage | Restraint | Medium | Interpretation and consent bottlenecks limit clinical throughput |
| Patchy reimbursement in emerging segments | Restraint | Medium | Out-of-pocket exposure caps uptake beyond hospital settings |
| Cross-border data-residency rules | Restraint | Medium | Local storage requirements raise compliance cost for global labs |
The balance favours growth, but not evenly: hospital-based clinical testing faces fewer friction points than consumer channels, where counsellor capacity and reimbursement decide whether demand converts to revenue. This divergence implies that vendors over-indexed to direct-to-consumer will see slower revenue realisation than those anchored in hospital and insurer contracts.
The UAE market is served by global sequencing and diagnostics majors alongside regional laboratories and hospital genomics units; no single vendor holds a dominant in-country share.
| Company | Type | Primary strength in UAE context |
|---|---|---|
| Illumina | Global platform provider | NGS instruments and cloud-based interpretation infrastructure |
| QIAGEN | Global diagnostics | PCR and sample-preparation workflows widely used in local labs |
| Myriad Genetics | Global specialty diagnostics | Hereditary cancer panel expertise and clinical evidence base |
| Dante Labs | International genomics services | Employer and wellness testing programmes, including Abu Dhabi engagements |
| Group 42 (G42) / M42 | Regional health-tech and lab network | Integration with national health authorities and lab reporting infrastructure |
| Local private diagnostic laboratories | Domestic service providers | Turnaround time, clinician relationships and local licensing |
Differentiation rests on three moats: platform lock-in through instrument and reagent ecosystems, regulatory and licensing depth with UAE health authorities, and clinical interpretation capacity. Our analysis suggests the interpretation layer — not the sequencer — is where regional labs can most credibly defend share.
Procurement decisions in this market hinge less on assay price than on three structural factors: accreditation and licensing, interpretation capacity, and data-governance compliance. Buyers should verify that a provider holds current UAE health-authority licensing for each test category, because a single lapsed approval can halt an entire panel offering.
Switching costs are elevated by workflow integration. Once a hospital embeds a sequencing platform's reporting pipeline into its laboratory information system, migrating to a rival entails revalidation, staff retraining and clinician re-education. This makes multi-year contracts with exit clauses more valuable than marginal per-test discounts.
Regulatory compliance carries a specific risk: cross-border transfer of genomic data faces residency and consent requirements, so providers relying on overseas interpretation centres may face delays or restructuring. Buyers should require documented data-residency arrangements at tender stage, and should stress-test provider capacity for genetic counselling, since interpretation bottlenecks — not sequencing — most often delay clinical reporting.
The balance of evidence favours the clinical-scope view of this market: a modest base growing at a genuinely high rate, with NGS and hospital channels as the durable revenue core. The strongest counter-argument is that consumer and wellness genomics could scale faster than clinical testing, lifting the broader definition toward the higher headline figure — but counsellor shortages and thin reimbursement make that a slower path than headline growth rates imply.
For operators, the implication is that share gains will come from depth in two Emirates rather than breadth across seven, and from owning the interpretation and counselling layer rather than the hardware. For investors, the market rewards providers with government relationships and licensed laboratory infrastructure; pure-play consumer kit models carry disproportionate regulatory and conversion risk.
Actionable strategy:
What would change this conclusion: sustained evidence of reimbursement coverage for multigene panels and consumer testing in the UAE, or a step-change in counsellor supply, would justify shifting weight toward the broader, faster-scaling market definition.
| Region | Market Share (%) |
|---|---|
| Abu Dhabi | 0.29% |
| Dubai | 0.44% |
| Sharjah | 0.1% |
| Northern Emirates | 0.18% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 21.40% from 2020-2034 |
| Segmentation |
|
The most cited clinical-scope estimate values the UAE genetic testing market at USD 29.27 Million in 2022, growing at 21.40% CAGR to 2030. Broader definitions that include consumer and wellness genomics cite figures above USD 650 Million, so scope must be checked before comparing.
Growth estimates range from 9.76% to 21.40% CAGR depending on definition. The higher rate applies to narrowly scoped clinical testing services, while the lower rate reflects a broader genomic services base that already includes consumer and equipment-linked revenue.
Next-generation sequencing leads by technology with 46.30% of 2022 revenue, ancestry and ethnicity leads by application at 50.72%, and hospitals lead by end-use at 61.37%. Offline channels still account for 55.29% of revenue despite fast online growth.
Illumina, QIAGEN and Myriad Genetics are the most prominent global suppliers, alongside international genomics services firms and regional laboratory networks such as G42 and M42. Local private diagnostic laboratories remain significant for turnaround time and clinician relationships.
Estimates differ because analysts define the market differently. Narrow clinical testing service revenue produces a small base with high growth, while broad definitions bundling consumer kits, wellness testing and equipment-linked spend produce a much larger base with lower growth.
The main restraints are a shortage of certified genetic counsellors, patchy reimbursement outside hospital settings, and cross-border genomic data-residency rules that raise compliance costs. These bottlenecks delay conversion of testing demand into recognised revenue.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the UAE genomics value chain with laboratory directors, sequencing platform distributors, hospital genomics department heads and private diagnostic lab operators. Decision-maker designations interviewed include laboratory operations directors, heads of molecular diagnostics, clinical genomics leads and commercial operations managers, ensuring demand-side and supply-side perspectives are captured simultaneously.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Laboratory & Molecular Diagnostics Directors | 40% |
| Clinical Genomics & R&D Leads | 30% |
| Procurement & Commercial Operations | 20% |
| Regulatory & Quality Affairs Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Hospital & Clinical Laboratory Operators | 40% |
| Sequencing Platform & Reagent Suppliers | 30% |
| Private Diagnostic & Consumer Testing Providers | 20% |
| Distributors & Health-Tech Integrators | 10% |
Secondary validation draws on official multilateral and standards sources, including WHO cancer incidence and mortality statistics, OECD testing guidance, national health-authority licensing registries and corporate annual filings from listed diagnostics and sequencing companies. Patent filings and peer-reviewed clinical literature were reviewed to validate technology adoption trajectories. No third-party market-research publications are cited as primary evidence.
Market sizing triangulates a top-down allocation from regional diagnostics spend against a bottom-up model built from laboratory test volumes, average assay pricing and installed sequencing capacity. Divergent published estimates were reconciled by mapping each to its underlying definition before selecting a planning baseline.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up lab volume and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Emirate-level share breakdown | Lab licensing density and population-weighted consumption | Medium-High |
| Competitive Landscape | Leading market players | Annual reports, platform installations & commercial filings | High |