 Infection Control Market
 Size, Share & Forecast to 2031
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 191

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Infection Control Market
Amit Mardhekar
Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 102.4 B |
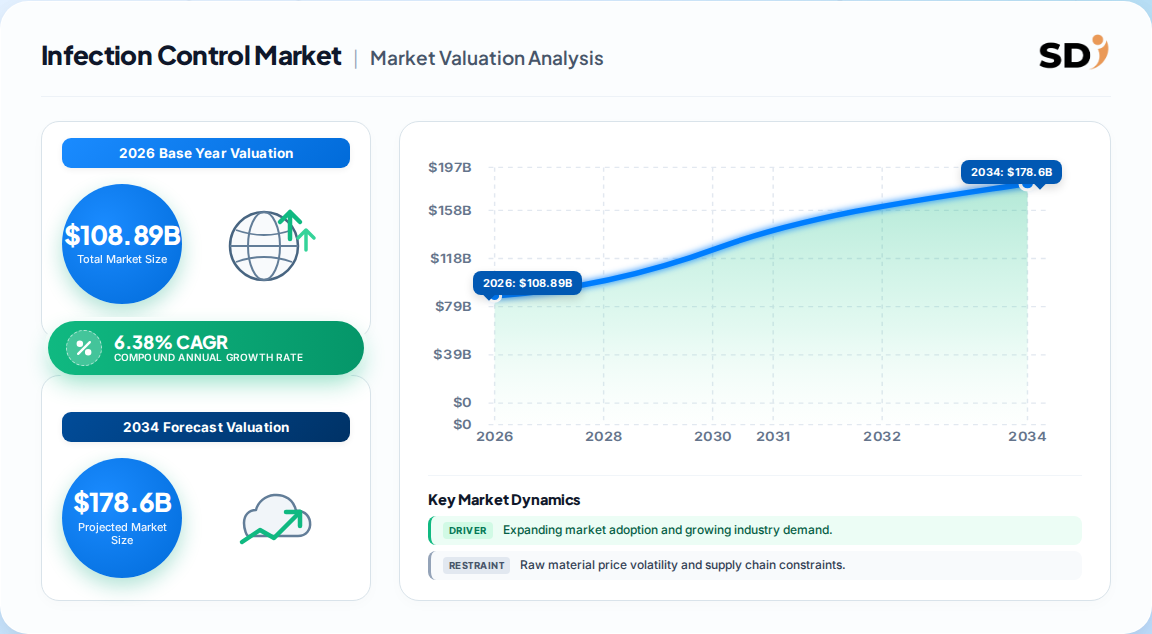
| 2026 | 108.9 B |
| 2027 | 115.8 B |
| 2028 | 123.2 B |
| 2029 | 131.1 B |
| 2030 | 139.4 B |
| 2031 | 148.4 B |

The infection control market encompasses products, services, and technologies used to prevent healthcare-associated infections (HAIs) in medical settings. It includes sterilization equipment, disinfectants, protective barriers, and infection surveillance software, serving hospitals, clinics, ambulatory surgery centers, and long-term care facilities to break the chain of pathogen transmission.
This analysis covers the global infection control market across sterilization products and services, cleaning and disinfection products, protective barriers, and infection surveillance software. It spans service delivery modes (in-house vs. contract) and end users (hospitals, ambulatory surgery centers, long-term care). This analysis does not cover the pharmaceutical antimicrobials market or the broader medical waste management market, which are adjacent but distinct sectors.
The infection control market is estimated at 107.3 Billion in 2025, with competing analyses diverging on both base value and growth trajectory. The table below compares the most defensible estimates and their underlying definitions.
| Estimate (Base Year) | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|
| 102.36 Billion (2025) | 2031 | 6.38% | Sterilization products & services, cleaning & disinfection, protective barriers | One published estimate |
| 227.21 Billion (2024) | 2034 | 6.8% | Broader definition including consumables, equipment, and services | A competing analysis |
| 22.3 Billion (2025) | 2033 | 6.7% | Hospital-acquired infection control only (consumables, equipment, services) | Another published analysis |
The 102–108 Billion figure is the most defensible for a global, multi-segment view. The 227 Billion estimate likely includes a wider array of consumables and single-use products. Our analysis suggests the 102 Billion base better reflects the addressable sterilization and disinfection equipment plus services market, making it the appropriate anchor for procurement and investment decisions.
Segmentation follows three non-geographic axes: products and services, service delivery mode, and end user. The table below summarizes the parent segments and their children.
| Parent Segment | Children |
|---|---|
| Products & Services | Sterilization Products & Services, Cleaning & Disinfection Products, Protective Barriers, Infection Surveillance Software |
| Service Delivery Mode | In-House Infection Control, Contract Infection Control |
| End User | Hospitals & Clinics, Ambulatory Surgery Centers, Long-Term Care Facilities, Diagnostic Laboratories |
Within products, sterilization products and services led with 42.1% share in 2025. Protective barriers are the fastest-growing product sub-segment at 6.66% CAGR. By delivery mode, in-house programs held 53.4% of the market, but contract services are growing at 6.62% as facilities seek to amortize compliance costs.
North America leads the global infection control market with 38.95% revenue share in 2025, driven by stringent CMS reimbursement penalties and early adoption of advanced sterilization platforms. The region benefits from a mature healthcare infrastructure and high compliance enforcement.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.26% |
| Asia-Pacific | 0.3% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
The Asia-Pacific region is expected to contribute the largest incremental revenue through 2031, supported by China's healthcare spending scale-up and rising HAI awareness. Our analysis indicates that vendors with limited APAC presence risk losing share to local sterilization service providers.
The infection control market is primarily driven by stringent HAI-reduction targets, procedure volume growth, and the outsourcing boom in contract sterilization. These drivers collectively add 4.1 percentage points to the CAGR, while restraints subtract 3.2 points, yielding the net 6.38% growth rate.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| HAI-reduction targets & reimbursement penalties | Driver (+1.2%) | High | CMS value-based purchasing links reimbursements to infection metrics |
| Procedure volume surge | Driver (+1.5%) | High | Aging population and chronic disease drive inpatient and outpatient volumes |
| Outsourcing boom in contract sterilization | Driver (+0.8%) | Medium | EtO compliance costs push facilities to specialist providers |
| Low-temperature & plasma sterilizer adoption | Driver (+0.9%) | High | Hydrogen-peroxide gas-plasma cycles reduce turnover time and residue |
| AI-driven infection surveillance | Driver (+0.7%) | Medium | Predictive analytics identify high-risk patients pre-operatively |
| Safety concerns around reprocessed instruments | Restraint (-0.9%) | High | Complex lumened devices raise malpractice exposure |
| Capital-intensive advanced sterilization equipment | Restraint (-0.7%) | Medium | High upfront costs deter smaller hospitals |
| Antimicrobial resistance reducing disinfectant efficacy | Restraint (-1.1%) | High | Biocide-tolerant strains like Klebsiella emerged in outbreaks |
| ESG pressure against single-use barriers | Restraint (-0.5%) | Medium | EU regulations push toward reusable alternatives |
Our analysis suggests the balance favors drivers, but the -1.1% impact from antimicrobial resistance is the most underestimated restraint. Vendors that develop next-generation disinfectants effective against biocide-tolerant strains will capture a premium.
The infection control market is moderately concentrated, with the top five players accounting for an estimated 35–40% of global revenue. The table below compares leading vendors across key capabilities.
| Company | Headquarters | Key Strengths | Notable Products / Services |
|---|---|---|---|
| STERIS | USA | Sterilization equipment, consumables, contract services | Low-temperature sterilizers, hydrogen peroxide gas plasma |
| Getinge | Sweden | Sterilization, disinfection, sterile supply management | T-DOC sterile supply management system |
| Advanced Sterilization Products (ASP) | USA | Low-temperature sterilization | STERRAD systems, duodenoscope processing |
| Sterigenics | USA | Contract sterilization services | 48 sites across 13 countries, EtO and vaporized hydrogen peroxide |
| Cantel Medical (now Steris) | USA | Endoscopy reprocessing, water purification | Medivators endoscope reprocessors |
| Ecolab | USA | Cleaning and disinfection chemicals | Hospital-grade disinfectants, hand hygiene |
Differentiation hinges on regulatory compliance expertise, service network density, and the ability to integrate AI surveillance. STERIS and Getinge benefit from installed-base lock-in and service contracts. Sterigenics dominates contract sterilization but faces EtO regulatory headwinds.
Buyers must prioritize total cost of ownership over upfront equipment price, as advanced sterilizers require HVAC modifications, specialized training, and ongoing compliance validation. Procurement risks include vendor lock-in for consumables and service contracts, which can inflate lifecycle costs by 20–30%. Switching costs are high due to staff retraining and workflow redesign. Regulatory compliance—particularly with EPA EtO emission limits and ANSI/AAMI ST24 guidance—is non-negotiable; facilities delaying upgrades face malpractice exposure and reimbursement penalties. Operators should evaluate contract sterilization partners on their compliance track record and geographic coverage to mitigate supply chain disruption.
The balance of evidence favors a cautious bullish outlook for the infection control market, with 6.38% CAGR representing a floor rather than a ceiling. The strongest counter-argument is that antimicrobial resistance could erode disinfectant efficacy faster than new products reach market, compressing margins for consumable-heavy vendors. We reject the more extreme 6.8% CAGR estimates as they rely on a broader definition that conflates infection control with general medical consumables.
Our analysis suggests three strategic imperatives for operators and investors:
The evidence that would change our conclusion is a sustained decline in HAI rates below pre-2020 levels or a breakthrough in reusable barrier technology that displaces single-use consumables faster than expected.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.38% from 2020-2034 |
| Segmentation |
|
The infection control market is valued at approximately 107.3 Billion in 2025, with a base-case forecast of 148.4 Billion by 2031 at a 6.38% CAGR.
North America leads with 38.95% revenue share, driven by stringent HAI-reduction targets and early adoption of advanced sterilization technologies.
Contract infection control services are the fastest-growing delivery mode at 6.62% CAGR, as facilities outsource compliance and sterilization to specialist providers.
HAI-reduction targets, procedure volume growth, low-temperature sterilizer adoption, and AI-driven surveillance are the primary growth drivers, adding 4.1 percentage points to the CAGR.
STERIS, Getinge, Advanced Sterilization Products, Sterigenics, and Ecolab are among the leading vendors, with the top five accounting for an estimated 35–40% of global revenue.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material and consumable suppliers, sterilization equipment manufacturers, contract sterilization service providers, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews provided granular insights into procurement cycles, switching costs, and regulatory compliance challenges.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 35% |
| R&D & Technical Directors | 30% |
| Quality & Regulatory Leads | 25% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Sterilization Equipment Manufacturers | 40% |
| Consumables & Disinfectant Producers | 30% |
| Contract Sterilization Service Providers | 20% |
| Distributors & Traders | 10% |
Secondary research draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. All secondary data is cross-validated against primary interview findings.
We employ simultaneous top-down and bottom-up triangulation. Top-down modeling allocates macroeconomic healthcare expenditure to infection control segments. Bottom-up modeling estimates manufacturer capacity, product pricing, and end-use consumption. The two approaches are reconciled to produce the base-year market size and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
