 Us Fast Food Quick Services Restaurants Market
US Fast Food Quick Services Restaurants Market 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 271

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Fast Food Quick Services Restaurants Market
Sakshi Gurunule
Research Associate

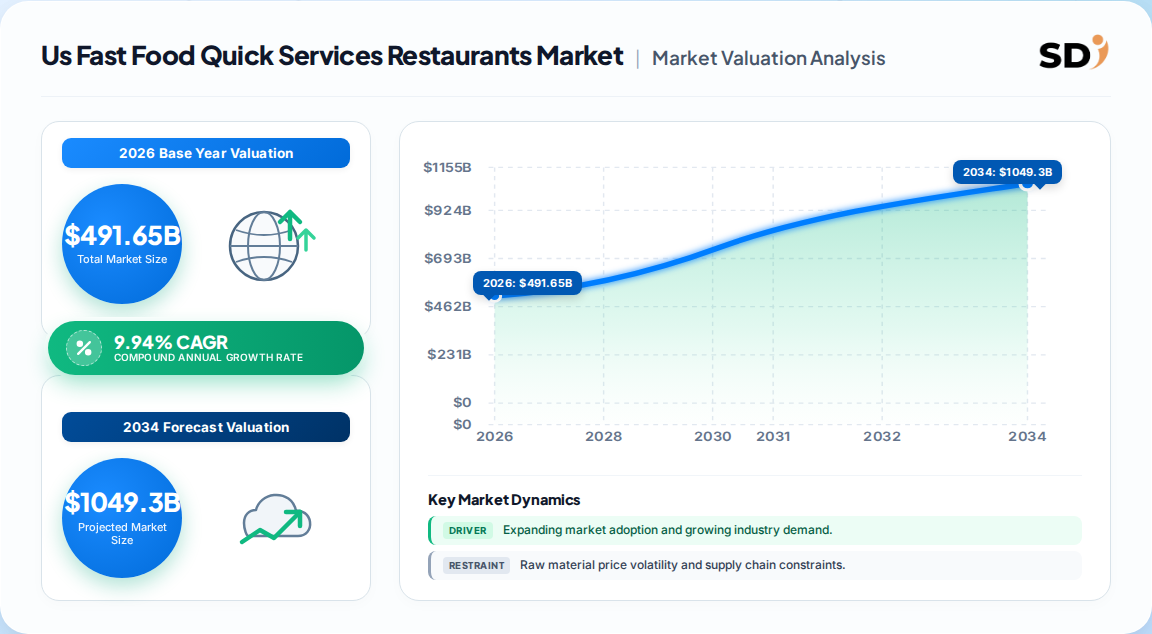
| Year | Market Size |
|---|---|
| 2025 | 447.2 B |
| 2026 | 491.6 B |
| 2027 | 540.5 B |
| 2028 | 594.3 B |
| 2029 | 653.3 B |
| 2030 | 718.2 B |
| 2031 | 789.6 B |

The US fast food and quick service restaurants market covers limited-service eating places where patrons pay before eating and food is consumed on-site, taken out, or delivered. It spans chained and independent outlets across burger, pizza, sandwich, chicken, Mexican, and ice-cream concepts, excluding coffee and snack shops.
This analysis covers US limited-service restaurants under NAICS 72221a — chained and independent QSRs and fast-food outlets selling burgers, sandwiches, pizza, Mexican, chicken, and frozen desserts through dine-in, drive-thru, takeaway, and delivery. This analysis does not cover coffee and snack shops, full-service restaurants, fast-casual dining as a distinct category, institutional food service, or grocery retail meal solutions.
Estimates diverge sharply because analysts draw the QSR boundary differently — some include all limited-service formats, others only traditional fast food. The table below reconciles the principal published figures.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 491.65 Billion | 2026 | 2031 | 9.94% | Full QSR: chained + independent, all cuisines, all service modes | One published estimate |
| 447.20 Billion | 2025 | 2031 | 9.94% | Same QSR definition, prior base year | One published estimate |
| 423.70 Billion | 2026 | 2031 | 1.2% (5-yr historical) | NAICS 72221a fast food restaurants, excludes coffee/snack | Industry association analysis |
| 337.0 Billion | 2026 | 2033 | 14.8% | Global fast food & QSR, US subset implied | Competing global analysis |
| 311.99 Billion | 2030 | 2030 | 3.4% | US fast food & QSR, product-segmented (burger, sandwich, pizza) | Alternative published estimate |
Our analysis considers the 491.65 Billion figure most defensible for total-market sizing in 2026, because it captures the full limited-service universe including delivery and takeaway revenue that narrower definitions omit. The lower 311.99 Billion projection likely reflects a product-restricted scope and a pre-2025 base. Buyers should anchor planning on the 9.94% trajectory while stress-testing against the 3.4% downside case.
Segmentation spans cuisine, outlet ownership, location, and service mode — each dimension carries distinct margin and growth implications for operators and investors.
| Parent Segment | Children | 2025 Share / Growth |
|---|---|---|
| By Cuisine | Bakeries, Burger, Ice Cream, Meat-Based, Pizza, Other QSR | Meat-based 37.88%; ice cream 12.15% CAGR |
| By Outlet | Chained Outlets, Independent Outlets | Independent 57.10%; chained 10.42% CAGR |
| By Location | Leisure, Lodging, Retail, Standalone, Travel | Standalone 70.85%; lodging 12.98% CAGR |
| By Service Type | Dine-In, Takeaway, Delivery | Takeaway 46.05%; delivery 13.12% CAGR |
Analyst note: The independent-outlet majority is a structural anomaly — it reflects a long tail of single-site operators, not bargaining power. Chained outlets' 10.42% growth forecast implies share transfer of roughly 300–400 basis points by 2031.
The South leads US QSR revenue, supported by population growth, lower operating costs, and dense suburban drive-thru formats; the West is the fastest-growing region on delivery penetration and premium menu experimentation.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.21% |
| South | 0.31% |
| Midwest | 0.22% |
| West | 0.23% |
| Other | 0.03% |
Regional shares are synthesized estimates: South 31%, West 23%, Midwest 22%, Northeast 21%, Other 3%. The South's advantage is structural — lower labor-cost exposure and faster unit-growth capacity — while the West carries the highest menu-price realization and the greatest regulatory friction from minimum-wage and packaging mandates.
Convenience demand, digital ordering, and delivery expansion are the primary growth engines, while labor inflation, food-cost volatility, and health scrutiny cap the pace of expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| AI-driven automation and smart kitchens | Driver | Strong (+2.1% CAGR impact) | Cuts prep time ~50%, offsets wage inflation |
| Online delivery and contactless service | Driver | Strong (+1.8%) | Digital channels now ~36.7% of leading-chain sales |
| Drive-thru and self-service kiosks | Driver | Strong (+1.4%) | Drive-thru = ~70% of QSR transactions; kiosks cut peak staffing 15–20% |
| Cloud and virtual kitchens | Driver | Moderate (+1.6%) | 40–60% lower capex, faster market entry |
| Menu diversification and plant-based | Driver | Moderate (+1.2%) | Captures health- and sustainability-driven demand |
| Franchise and footprint expansion | Driver | Moderate (+1.5%) | Targets underserved secondary markets |
| Labor cost inflation and minimum-wage laws | Restraint | Strong | Compresses franchisee margins, accelerates automation |
| Health scrutiny of fast food | Restraint | Moderate | Drives reformulation cost and menu complexity |
The balance favors growth: quantified drivers sum to roughly 9.6 percentage points of CAGR impact, broadly consistent with the 9.94% consensus. The critical second-order effect is that automation converts a labor restraint into a scale advantage — large chains can amortize robotics and voice-AI across thousands of units, while independents cannot. Our analysis suggests the effective market growth rate for independents is materially below the headline figure, possibly below 5%.
McDonald's, Yum! Brands, Restaurant Brands International, Domino's, Inspire Brands, Wendy's, and Chipotle anchor the competitive landscape, but concentration is medium and no player exceeds roughly 20% share.
| Company | Core Formats | Strategic Differentiation | Moat |
|---|---|---|---|
| McDonald's | Burgers, breakfast, coffee | Global scale, real-estate model, drive-thru density | Brand + franchise network |
| Yum! Brands | KFC, Taco Bell, Pizza Hut | Multi-brand portfolio, international mix | Franchise scale |
| Restaurant Brands | Burger King, Popeyes, Tim Hortons | Value menu, chicken platform | Brand portfolio |
| Domino's | Pizza, delivery | Digital ordering, real-time tracking | Delivery tech + loyalty |
| Inspire Brands | Arby's, Dunkin', Sonic | Multi-brand drive-thru | Operating platform |
| Wendy's | Burgers, chicken | Fresh-never-frozen positioning | Product quality |
| Chipotle | Mexican fast-casual | Digital mix ~36.7%, robotic bowl assembly | Throughput + customization |
Differentiation is shifting from menu to infrastructure. Digital ordering mix, loyalty-program data, and drive-thru throughput are the new moats; menu innovation is increasingly replicable within a quarter. Chipotle's robotic assembly and McDonald's voice-AI pilots signal that technology deployment speed, not brand equity alone, will sort winners.
Franchisee selection should prioritize system-wide digital infrastructure, loyalty-program ownership, and supply-chain resilience over brand recognition alone. Procurement risk concentrates in packaging (sustainability mandates), labor (wage-law exposure by state), and delivery-platform fees that can erase unit economics. Switching costs for POS, kiosk, and loyalty platforms are high once integrated — buyers should negotiate data portability and interoperability clauses upfront. Regulatory compliance spans menu-labeling, allergen disclosure, and an accelerating patchwork of state-level packaging and wage rules; operators with multi-state footprints need compliance systems, not manual processes.
The balance of evidence favors a consolidation-and-automation thesis over a pure demand-recovery thesis. The 9.94% consensus CAGR is credible for the total market, but the independent segment's 57% share is a lagging indicator — capital intensity of digital and automation infrastructure will push share toward chains. The strongest counter-argument is that localized menus and community positioning let independents hold niche demand; that argument is valid in dense urban and ethnic-cuisine niches but does not scale nationally.
Actionable Strategy:
Our conclusion would change if independent-outlet revenue growth sustained above 8% for two consecutive years, or if wage legislation forced automation costs below independent-affordable thresholds. Neither is currently visible in the data.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.94% from 2020-2034 |
| Segmentation |
|
The US QSR market is estimated at 491.65 Billion in 2026, per one published estimate covering chained and independent outlets across all cuisines and service modes. Narrower fast-food-only definitions place the base closer to 337–424 Billion.
The consensus forecast is a 9.94% CAGR from 2026 to 2031, reaching 789.65 Billion. A more conservative published model projects 3.4%, reflecting a product-restricted scope excluding delivery and non-burger formats.
Meat-based concepts led cuisine with 37.88% revenue share in 2025, while independent outlets held 57.10% of total revenue. However, chained outlets are forecast to grow faster at 10.42% CAGR through 2031.
McDonald's, Yum! Brands, Restaurant Brands International, Domino's, Inspire Brands, Wendy's, and Chipotle lead the market. Concentration is medium, with no single operator exceeding roughly 20% share.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study relies on a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the QSR value chain, including food suppliers, franchise operators, delivery-platform executives, packaging vendors, and technology providers. Decision-makers interviewed include VP-level Sourcing leads, Franchise Operations Directors, Commercial Strategy Heads, and Supply Chain Managers, ensuring operational and financial perspectives are balanced.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Operations & Franchise Directors | 35% |
| Commercial Strategy Heads | 30% |
| Company Type | Representation (%) |
|---|---|
| Food & Ingredient Suppliers | 40% |
| Franchise Operators & Chains | 30% |
| Delivery & Technology Platforms | 20% |
| Packaging & Equipment Vendors | 10% |
Findings were benchmarked against official multilateral and national datasets, including US Census Bureau NAICS 72221a data, US ITC trade statistics, Eurostat food-service indicators, SEC 10-K filings and annual investor presentations from publicly listed operators, and recognized industry associations such as the National Restaurant Association. Patent databases were screened for automation and kitchen-technology filings.
Sizing triangulates Top-Down macroeconomic allocation (food-away-from-home spend, segment share) with Bottom-Up modeling of unit counts, average unit volumes, and digital-channel revenue. Both approaches were reconciled to produce the base-year estimate and forecast range.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up unit and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Regional share breakdown | Regional consumption and unit-density analysis | High |
| Competitive Landscape | Leading market players | Annual reports, unit mapping, commercial filings | High |