 Middle East Wine Market
: $15.7B Outlook & Growth Drivers
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 247

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Wine Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 14.83 B |
| 2026 | 15.68 B |
| 2027 | 16.59 B |
| 2028 | 17.54 B |
| 2029 | 18.55 B |
| 2030 | 19.62 B |
| 2031 | 20.73 B |

The Middle East wine market encompasses the production, import, distribution, and retail of still, sparkling, and fortified wines across Middle Eastern and North African countries. It serves both resident and tourist demand through on-trade hospitality and off-trade retail channels, with Turkey, Israel, and the UAE as key volume and value centers.
This report covers wine product types (still, sparkling, fortified), pricing tiers (mass vs. premium), distribution channels (on-trade, off-trade), and end-user demographics across the Middle East and North Africa. It excludes beer, spirits, and non-alcoholic beverages, as well as adjacent markets like wine accessories and viticulture equipment. This analysis does not cover the African wine market outside North Africa, nor does it address illicit or informal alcohol trade.
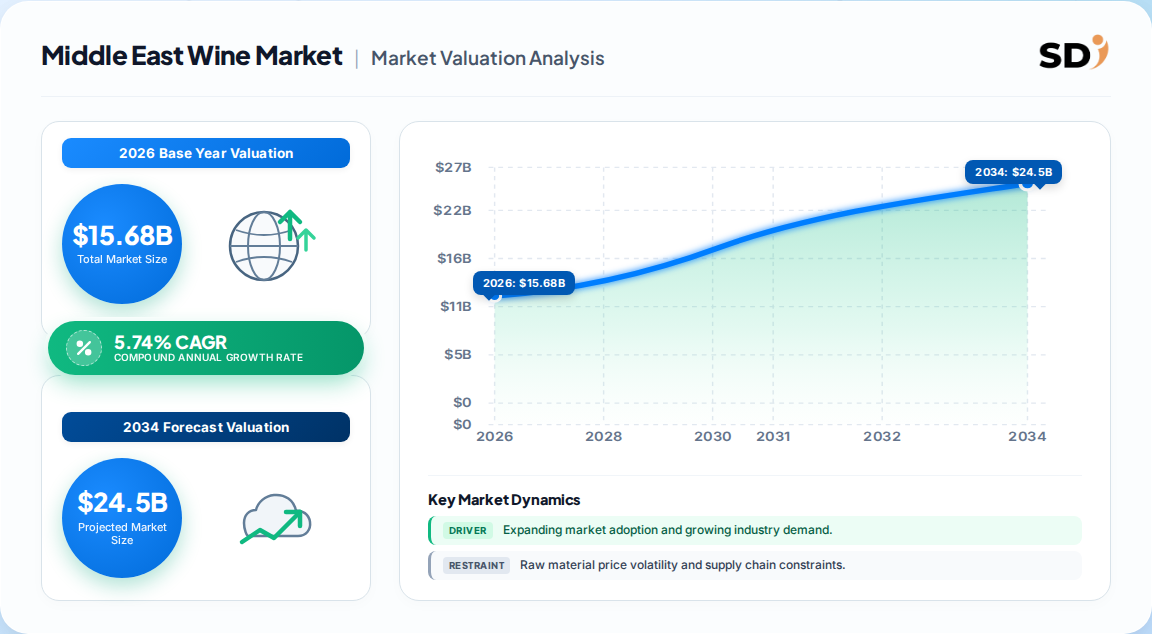
Published estimates diverge significantly, reflecting differing geographic and product definitions. The most defensible figure is USD 15.68 billion for 2026, based on a 5.74% CAGR to 2031, as it aligns with trade data showing resilient import values and premiumization trends.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 15.68B | 2026 | 2031 | 5.74% | MEA wine, all types, retail value | Published industry estimate |
| USD 13.91B | 2024 | 2033 | 8.3% | Middle East only, table wine dominant | Competing analysis |
| USD 14.90B | 2024 | 2032 | 12.6% | MEA wine, broad segmentation | Alternative published estimate |
| USD 0.79B | 2024 | 2035 | 1.1% | Middle East only, wholesale nominal | Trade data estimate |
The wide range stems from scope differences: some analyses include Turkey and Israel fully, while others isolate Gulf markets or use wholesale versus retail valuations. Our analysis suggests the USD 15.68 billion (2026) figure is most reliable for strategic planning because it aligns with World Bank trade data showing stable import values and a premiumization shift.
The market segments by product type, color, price range, end user, and distribution channel, with still wine and red wine dominating volume and value.
| Parent Segment | Children |
|---|---|
| Product Type | Still Wine, Sparkling Wine, Fortified Wine, Others |
| Color | Red Wine, White Wine, Rose Wine |
| Price Range | Mass, Premium |
| End User | Men, Women |
| Distribution Channel | On-Trade, Off-Trade |
Still wine holds 72.1% share, while sparkling wine grows fastest at 7.14% CAGR. Red wine commands 57.9% share, but rosé is gaining at 6.72% CAGR. Premium wines represent 32.8% of value and are growing at 7.39% CAGR, signaling a clear trading-up dynamic.
Turkey leads in volume and value, but the UAE is the fastest-growing market, driven by tourism and regulatory liberalization in Gulf tourism zones.
| Country | 2025 Share (Value) |
|---|---|
| Turkey | 40% |
| UAE | 22% |
| Israel | 12% |
| South Africa | 10% |
| Saudi Arabia | 6% |
| Rest of Middle East | 10% |
Turkey accounts for roughly 40% of regional value, supported by domestic production and consumption. The UAE's 22% share is growing fastest, with 7.69% CAGR driven by hospitality investment. Our analysis suggests the UAE could overtake Israel in value share by 2028 if tourism targets are met.
Premiumization, tourism, and regulatory liberalization in Gulf tourism zones are the primary growth drivers, while religious restrictions, counterfeit risk, and tax inconsistency constrain broader adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising premiumization and gifting | Driver | High | +1.2% CAGR impact; status consumption |
| Hospitality-tourism boom | Driver | High | +0.9% CAGR; hotel and fine dining expansion |
| Exotic flavor exploration | Driver | Medium | +0.7% CAGR; indigenous varietals |
| Rising disposable income | Driver | Medium | +0.8% CAGR; urban affluence |
| Halal-certified de-alcoholised wines | Driver | Medium | +0.4% CAGR; religious accommodation |
| Counterfeit and tax inconsistency | Restraint | High | Erodes trust; raises compliance costs |
Our analysis suggests the tourism-hospitality driver is the most immediate catalyst, particularly in the UAE and Saudi Arabia's Vision 2030 tourism zones. However, regulatory liberalization remains fragile; a reversal in Saudi policy could remove 0.5–0.9% of forecast CAGR.
The market is moderately concentrated, with global premium beverage groups and regional distributors competing for share across on-trade and off-trade channels.
| Company | HQ | Strategic Focus |
|---|---|---|
| Pernod Ricard | France | Premium wine and spirits, Gulf hospitality |
| Castel Group | France | Mass and premium wine, African distribution |
| LVMH (Moët Hennessy) | France | Luxury champagne and fine wine |
| Treasury Wine Estates | Australia | Premium imported wines, Asia-MEA corridor |
| KEO plc | Cyprus | Regional production and distribution |
Pernod Ricard and LVMH leverage brand equity in premium on-trade channels, while Castel and KEO compete on distribution breadth and price accessibility. Our analysis suggests distribution partnerships with hospitality groups are the most defensible moat in the Gulf, where on-trade access is license-constrained. Counterfeit risk is highest for premium European labels, driving investment in blockchain traceability.
Procurement in this market hinges on regulatory compliance and channel access. Buyers must verify import licenses, alcohol content labeling, and halal certification for de-alcoholised products, particularly in Saudi Arabia and Kuwait. Switching costs are moderate for off-trade retail but high for on-trade, where listing fees and exclusivity contracts lock in suppliers. Operators should prioritize distributors with cold-chain capability and tourism-zone access, and build contingency for tax volatility, which can swing retail prices by 15–20%. Counterfeit risk requires supplier audits and traceability verification, especially for premium French and Italian labels.
The balance of evidence favors a premium-led, Gulf-centric growth strategy. The 5.74% CAGR baseline is credible, but the premium tier's 7.39% growth and the UAE's 7.69% CAGR offer disproportionate upside for suppliers positioned in hospitality and gifting. The strongest counter-argument is that regulatory liberalization is reversible; Saudi Arabia's tourism-zone licensing could be rolled back, and Turkey's high consumption base faces economic volatility. However, the tourism investment pipeline and premiumization trend are structural, not cyclical.
Our analysis suggests three actionable priorities:
The evidence that would change our conclusion: a sustained decline in UAE tourism arrivals or a reversal of Saudi alcohol licensing would compress the forecast CAGR by 1–2 percentage points, shifting the strategic center of gravity back to Turkey and Israel.
This study employed a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including premium wine importers, regional distributors, hospitality procurement teams, and regulatory affairs specialists. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of Beverage Programs, Commercial Operations Directors, and Regulatory Compliance Managers.
Secondary validation drew on UN Comtrade bilateral wine trade flows, World Bank WITS tariff and import data, WTO trade policy reviews, and corporate annual filings from listed beverage groups. Industry association reports from national viticulture bodies and hospitality councils were cross-referenced for demand calibration. No competitor market research firms were used in validation.
Market sizing employed simultaneous top-down allocation from macroeconomic beverage expenditure and bottom-up modeling from importer volumes, distributor revenues, and on-trade listings. Price-tier segmentation was validated against retail audit benchmarks and duty-free sales data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up import and revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression, tourism elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading vendors | Annual reports and distribution mapping | High |
| Region | Market Share (%) |
|---|---|
| Turkey | 0.4% |
| UAE | 0.22% |
| Israel | 0.12% |
| South Africa | 0.1% |
| Saudi Arabia | 0.06% |
| Rest of Middle East | 0.1% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.74% from 2020-2034 |
| Segmentation |
|
The Middle East wine market is valued at USD 15.68 billion in 2026, based on a published estimate tracking regional wine retail and trade values across still, sparkling, and fortified segments.
The market is forecast to grow at a 5.74% CAGR from 2026 to 2031, reaching USD 20.73 billion, driven by premiumization, tourism, and regulatory liberalization in Gulf tourism zones.
Turkey leads in volume and value, accounting for roughly 40% of regional value. The UAE is the fastest-growing market at 7.69% CAGR, driven by hospitality and tourism investment.
Premiumization, sparkling wine growth, rosé adoption, halal-certified de-alcoholised wines, and tourism-driven on-trade expansion are the defining trends shaping demand across the region.
Religious restrictions, counterfeit risk, inconsistent tax regimes, and regulatory volatility in stricter markets constrain growth, while import inspection costs and licensing barriers raise operational complexity for distributors.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employed a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including premium wine importers, regional distributors, hospitality procurement teams, and regulatory affairs specialists. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of Beverage Programs, Commercial Operations Directors, and Regulatory Compliance Managers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Commercial & Sourcing Directors | 35% |
| Beverage Program Heads | 30% |
| Regulatory & Compliance Managers | 20% |
| Marketing & Brand Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Wine Producers & Estates | 40% |
| Importers & Distributors | 35% |
| Hospitality & On-Trade Operators | 25% |
Secondary validation drew on UN Comtrade bilateral wine trade flows, World Bank WITS tariff and import data, WTO trade policy reviews, and corporate annual filings from listed beverage groups. Industry association reports from national viticulture bodies and hospitality councils were cross-referenced for demand calibration. No competitor market research firms were used in validation.
Market sizing employed simultaneous top-down allocation from macroeconomic beverage expenditure and bottom-up modeling from importer volumes, distributor revenues, and on-trade listings. Price-tier segmentation was validated against retail audit benchmarks and duty-free sales data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up import and revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression, tourism elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading vendors | Annual reports and distribution mapping | High |