 Middle East Fortified Dairy Products Market
 2025
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 189

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Fortified Dairy Products Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2024 | 2.250 B |
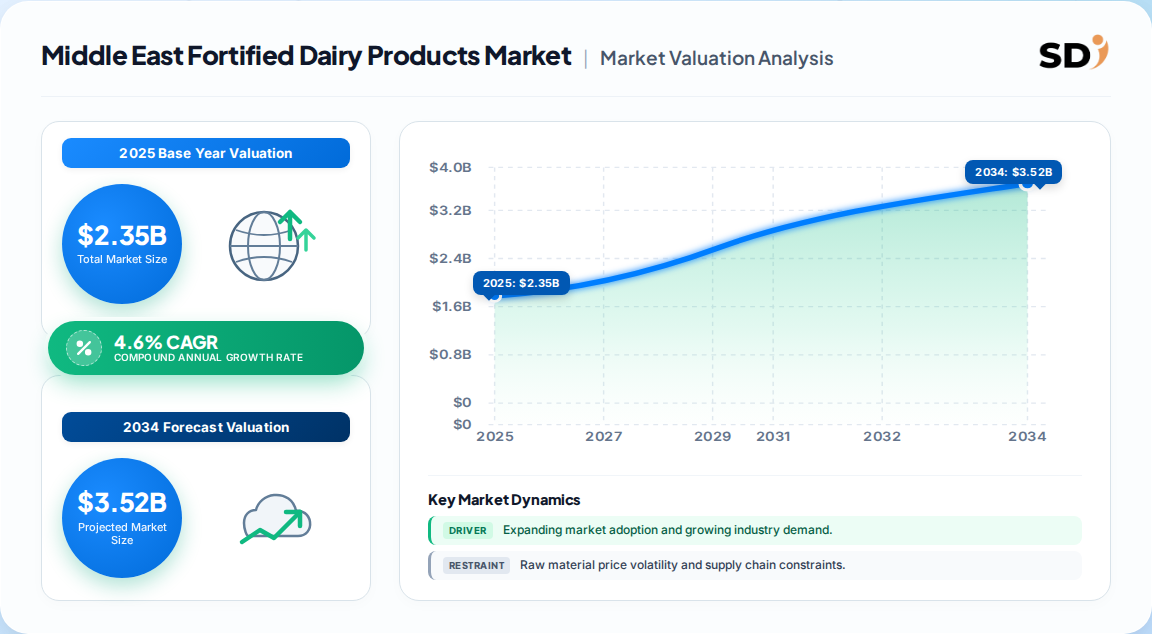
| 2025 | 2.350 B |
| 2026 | 2.460 B |
| 2027 | 2.570 B |
| 2028 | 2.690 B |
| 2029 | 2.820 B |
| 2030 | 2.950 B |

The Middle East fortified dairy products market covers milk, yogurt, cheese, butter and dairy desserts enriched with vitamins, minerals, probiotics, proteins or omega-3s beyond natural levels. It targets nutrient-gap correction — notably vitamin D and calcium — across GCC and wider Middle East consumers, sold largely through modern retail and institutional channels.
This analysis covers fortified fluid milk, yogurt, cheese, butter and dairy desserts across the Middle East, segmented by product, ingredient, distribution channel and country. It addresses GCC markets plus Egypt, Iran, Jordan and Lebanon where data permits. This analysis does not cover plant-based dairy alternatives as a standalone category, infant formula, or unfortified commodity dairy.
One published estimate places the Middle East fortified dairy products market at USD 2.25 billion in 2024, rising to USD 3.35 billion by 2033 at a 4.6% CAGR — implying roughly USD 2.35 billion in 2025. A competing global analysis frames the wider fortified dairy universe at USD 31.4 billion, with the Middle East and Africa contributing a single-digit share. The regional-specific figure is the more defensible basis for GCC execution planning.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 2.25 bn | 2024 | 2033 | 4.6% | Middle East fortified dairy, product-ingredient-channel | One published regional estimate |
| USD 3.35 bn | 2033 | 2033 | 4.6% | Same definition, forecast horizon | Same regional estimate |
| USD 31.4 bn | 2026 | 2036 | 5.1% | Global fortified dairy, all regions, broader product set | A competing global analysis |
| USD 44.82 bn | 2026 | 2031 | 4.64% | Middle East & Africa total dairy, fortified and unfortified | A separate trade analysis |
The regional figure is preferred because it isolates fortified SKUs and matches the GCC procurement reality. The global figure is useful only for comparative growth benchmarking, not for sizing a single-emirate tender.
Fortified dairy in the Middle East splits along three commercial axes: product form, ingredient function and distribution channel. Yogurt and probiotic ingredients are the dominant pairing, while protein and clean-label formulations are the growth vectors.
| Parent segment | Children |
|---|---|
| Product | Milk, Yogurt, Cheese, Butter, Dairy desserts, Frozen desserts |
| Ingredient | Probiotic & prebiotic, Protein, Vitamins & minerals, Omega-3, Fiber |
| Distribution channel | Hypermarket/supermarket, Convenience stores, Pharmacies, Online, Specialty |
Yogurt's 48.2% share reflects daily household use and digestive-health positioning. Probiotic dominance at 50.1% suggests ingredient spend is concentrated in gut-health claims rather than broad micronutrient blends — a signal that strain-specific science, not generic vitamin dosing, drives premium pricing.
Saudi Arabia leads the Middle East fortified dairy products market with 26.65% of 2024 revenue, while the UAE grows fastest at a 5.7% CAGR through 2033. Egypt, Qatar and Kuwait form the second tier of demand.
| Country | 2024 Share of Middle East Revenue | Growth Signal |
|---|---|---|
| Saudi Arabia | 26.7% | Largest base, school-milk contracts |
| UAE | ~18.5% | Fastest CAGR at 5.7% |
| Egypt | ~14.5% | Price-sensitive, probiotic volume growth |
| Qatar | ~9.0% | Institutional mandates, Baladna strength |
| Kuwait | ~7.5% | Premium urban demand |
| Oman | ~6.0% | Emerging modern trade |
| Bahrain | ~4.5% | Niche premium |
| Rest of Middle East | ~13.4% | Fragmented, informal channels |
Saudi dominance is structural: Almarai's farm-to-logistics integration and government school-milk contracts lock in volume. The UAE's faster growth reflects organic cow- and camel-milk premiumization. Our analysis suggests the UAE will close roughly 3 percentage points of share gap with Saudi Arabia by 2030 if premiumization outpaces Saudi volume-led expansion.
Growth is driven by government nutrition mandates, rising vitamin D deficiency awareness and modern retail expansion, while regulatory fragmentation and cold-chain gaps restrain speed-to-market and rural reach.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Vitamin D deficiency awareness | Driver | High | Public health campaigns convert to fortified milk/yogurt purchase |
| School milk & nutrition programs | Driver | High | Institutional contracts lock in volume and fortification specs |
| Modern retail expansion | Driver | Medium-High | Chilled shelves raise fortified SKU visibility |
| Probiotic gut-health claims | Driver | High | Strain-specific science justifies premium pricing |
| Regulatory fragmentation | Restraint | Medium | Uneven fortification dose rules delay cross-border launches |
| Cold-chain gaps | Restraint | Medium | Limits rural distribution of chilled fortified dairy |
| Plant-based alternatives | Restraint | Low-Medium | Competes for lactose-intolerant and clean-label buyers |
The balance favors growth. Institutional demand provides a floor that insulates leading vendors from retail volatility, but the same contracts impose traceability and calcium-vitamin thresholds that raise compliance costs and favor vertically integrated players. Our analysis suggests regulatory alignment across GCC — not consumer demand — is the binding constraint on faster category expansion.
Almarai leads Middle East fortified dairy through scale and government contracts, while Baladna, SADAFCO and NADEC compete on institutional and premium positioning. Multinationals Danone, Arla and FrieslandCampina bring strain science and clean-label credibility.
| Company | Headquarters | Strategic Positioning |
|---|---|---|
| Almarai | Saudi Arabia | Scale leader, farm-to-logistics, school milk |
| SADAFCO | Saudi Arabia | UHT and institutional supply |
| NADEC | Saudi Arabia | Integrated dairy, fortified lines |
| Baladna | Qatar | Domestic mandate supplier, vitamin D milk |
| Danone | France | Probiotic strain science (Activia) |
| Arla Foods | Denmark | Premium and clean-label fortified |
| FrieslandCampina | Netherlands | Ingredient and formulation depth |
Differentiation rests on three moats: vertical integration (Almarai, NADEC), strain-specific probiotic science (Danone), and institutional relationships (Baladna, SADAFCO). Our analysis suggests the integration moat is the most durable in GCC tenders, because fortification compliance and cold-chain reliability are procurement gatekeepers, not differentiators.
Buyers evaluating fortified dairy suppliers should prioritize four criteria: verified fortification retention after heat treatment, documented strain identity for probiotics, compliance with country-specific dose rules, and cold-chain reliability. Retention matters most — vitamin A and D degrade through UHT and storage, so suppliers who test post-process nutrient levels carry lower recall risk.
Procurement risk concentrates in single-source dependence on vertically integrated national players. Switching costs are moderate for commodity fortified milk but high for probiotic SKUs where strain science and shelf-life data are proprietary. Regulatory compliance varies by market: GCC school programs impose calcium and vitamin D thresholds that exclude commodity suppliers, while national fortification rules on dose and claims delay cross-border launches. Operators should map per-country dose ceilings before committing to a formulation, and build dual-sourcing for chilled yogurt where cold-chain gaps create service risk.
The balance of evidence favors a volume-led, institutionally anchored strategy over premium-led expansion in this region. Fortified dairy here is not a lifestyle category — it is a public-health delivery mechanism, and the buyers with the largest budgets are governments and school programs. Vendors that treat fortification as premium positioning will under-index against those who engineer compliance into the base SKU.
The strongest counter-argument is premiumization: UAE organic and camel-milk fortified lines are growing fastest, and affluent urban demand could reward science-backed premium claims. That argument is valid but narrow — it wins in Dubai and Doha, not in Riyadh's mass market or Cairo's price-sensitive tiers. A portfolio should run both, but capital allocation should follow institutional volume.
Actionable strategy:
Our conclusion would change if GCC regulators harmonized fortification dose ceilings, which would lower launch costs and favor faster-moving multinationals over integrated local incumbents. Absent that, scale and institutional relationships remain the decisive advantages.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.27% |
| UAE | 0.19% |
| Egypt | 0.14% |
| Qatar | 0.09% |
| Kuwait | 0.08% |
| Oman | 0.06% |
| Bahrain | 0.05% |
| Rest of Middle East | 0.13% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.6% from 2020-2034 |
| Segmentation |
|
It was estimated at USD 2.25 billion in 2024 and is projected to reach USD 3.35 billion by 2033, growing at a 4.6% CAGR. Roughly USD 2.35 billion is a defensible 2025 estimate.
Saudi Arabia led with 26.65% of 2024 revenue, supported by school milk contracts and vertically integrated producers. The UAE is the fastest-growing market at a 5.7% CAGR through 2033.
Yogurt held the largest share at 48.23% in 2024, driven by probiotic and prebiotic formulations that support digestive health and command premium pricing.
Probiotic and prebiotic ingredients held 50.12% share in 2024. Vitamins, minerals and protein follow, with vitamin D and calcium central to GCC public-health fortification mandates.
Almarai, SADAFCO, NADEC and Baladna lead regionally, while Danone, Arla Foods and FrieslandCampina bring probiotic science and clean-label formulation depth to the category.
Hypermarkets and supermarkets held 43.52% of 2024 revenue, supported by chilled retail formats and regular household grocery purchasing. Online and pharmacy channels are growing from a smaller base.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the fortified dairy value chain, including raw material and fortificant suppliers, specialized dairy producers, contract formulators, and regional distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both formulation economics and go-to-market strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Quality Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Dairy Producers & Processors | 45% |
| Fortificant & Ingredient Suppliers | 30% |
| Distributors & Modern Retailers | 25% |
Secondary validation draws on multilateral trade databases (UN Comtrade, WTO), regional statistical agencies, corporate annual filings and investor presentations, patent databases, and recognized technical standards from industry associations. These sources are used to triangulate capacity, trade flows and fortification compliance benchmarks across GCC markets.
Sizing runs simultaneous top-down and bottom-up models. The top-down model allocates macroeconomic dairy consumption and fortified penetration by country; the bottom-up model builds from manufacturer capacity, product pricing and end-use consumption. Divergence between the two is reconciled through category-level elasticity checks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |