 Food Service Equipment Market
: Global Size & Forecast 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 202

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Food Service Equipment Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 41.50 B |
| 2026 | 44.40 B |
| 2027 | 47.50 B |
| 2028 | 50.90 B |
| 2029 | 54.40 B |
| 2030 | 58.20 B |
| 2031 | 62.20 B |

The Food Service Equipment Market encompasses commercial appliances and tools used in restaurants, hotels, institutional kitchens, and catering operations for food preparation, cooking, storage, serving, and warewashing. This includes ovens, fryers, refrigerators, dishwashers, and holding cabinets designed for high-volume, professional use.
This report covers the global market for commercial food service equipment, segmented by product type (cooking, storage, warewashing, food holding & serving, and others), end use (full-service restaurants, quick-service restaurants, caterers, hotels & clubs, institutional), and sales channel (online, offline). This analysis does not cover household kitchen appliances, industrial food processing machinery, or vending machines, which are distinct markets with different regulatory and operational dynamics.
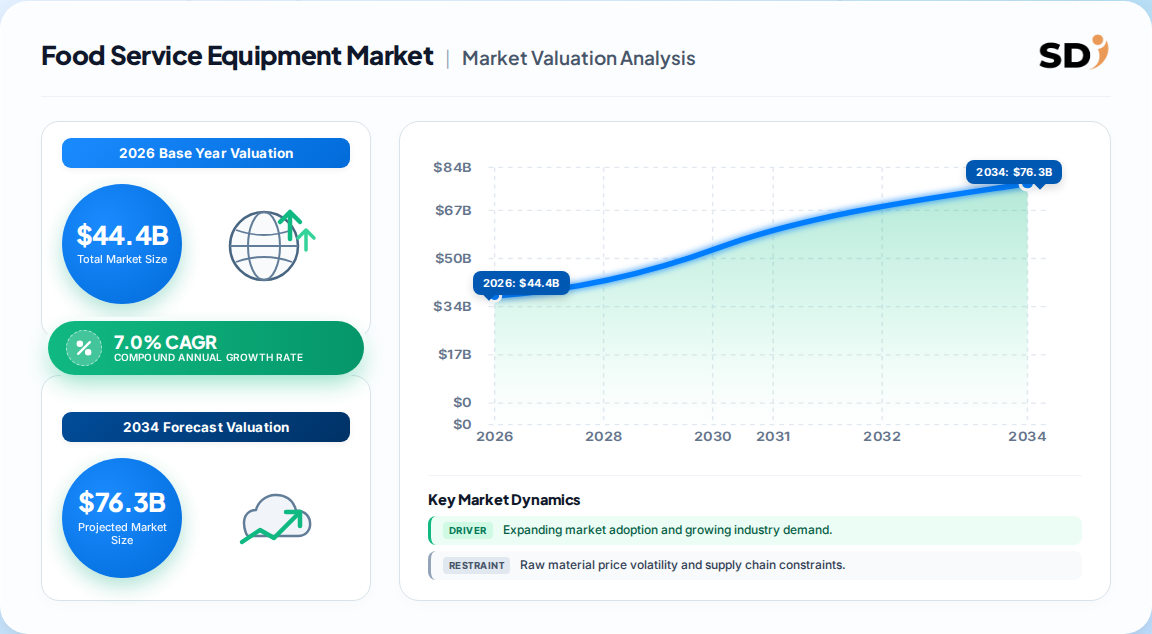
Multiple estimates converge on a market size of approximately USD 44 billion in 2026, with growth rates ranging from 4.1% to 7.0% depending on definition and scope. The most defensible figure is USD 44.4 billion in 2026, based on a comprehensive definition including all commercial equipment types and end uses.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 44.4 Billion | 2026 | 2033 | 7.0% | Broad: all commercial kitchen equipment | One published estimate |
| USD 44.2 Billion | 2026 | 2034 | 4.14% | Narrower: excludes some specialty equipment | Another analysis |
| USD 41.2 Billion | 2025 | 2035 | 4.92% | Broad: similar to first but older base | Third published estimate |
| USD 41.9 Billion | 2025 | 2034 | 4.14% | Mid-range: includes major equipment types | Fourth source |
The divergence in CAGR (4.1% vs. 7.0%) stems primarily from forecast horizon and inclusion of emerging sub-segments like IoT-enabled smart equipment. Our analysis suggests the 7.0% CAGR is realistic given accelerating adoption of automation and cloud kitchens, but operators should plan for at least 5% annual growth as a conservative baseline.
The market is segmented by product type, end use, and sales channel, with product type further divided into cooking, storage, warewashing, and holding & serving equipment.
| Parent Segment | Children Segments |
|---|---|
| By Type | Kitchen Purpose Equipment, Food Holding & Storing Equipment, Warewashing Equipment, Food Preparation Equipment, Serving Equipment |
| By End Use | Full Service Restaurant (FSR), Quick Service Restaurant (QSR), Institutional, Catering, Hotels & Clubs |
| By Sales Channel | Online, Offline |
Asia Pacific leads the global market with a 37.4% revenue share in 2025, driven by rapid urbanization, expanding food service chains, and increasing disposable incomes in China and India. However, North America remains a strong second, with high technology adoption and a mature replacement market.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.23% |
| Asia-Pacific | 0.34% |
| South America | 0.05% |
| Middle East & Africa | 0.06% |
| Region | Share (2025) |
|---|---|
| Asia Pacific | 37.4% |
| North America | 30.1% |
| Europe | 22.3% |
| Latin America | 5.6% |
| Middle East & Africa | 4.6% |
The market is propelled by the expansion of the hospitality sector, rising demand for convenience foods, and technological advancements such as IoT and automation. However, high initial investment costs and supply chain volatility are significant restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Growth of hospitality sector | Driver | High | Increased hotel and restaurant openings drive equipment demand |
| Rising demand for convenience foods | Driver | High | QSR and delivery-focused kitchens require efficient equipment |
| Technological advancements (IoT, AI) | Driver | High | Smart equipment enhances efficiency and reduces labor costs |
| Focus on sustainability | Driver | Medium | Energy-efficient equipment reduces operating costs and meets regulations |
| High initial investment | Restraint | High | Limits adoption among small and mid-sized operators |
| Supply chain disruptions | Restraint | Medium | Raw material price volatility increases costs and lead times |
| Stringent regulations | Restraint | Medium | Compliance costs slow replacement cycles |
The balance of evidence suggests that drivers outweigh restraints, particularly as financing options and equipment-as-a-service models emerge to address affordability concerns. Our analysis indicates that the labor shortage is a structural driver that will persist, forcing operators to invest in automation regardless of economic cycles.
The market is highly competitive with global players such as Ali Group, Middleby Corporation, Welbilt, ITW, and Hoshizaki leading through broad product portfolios and strong distribution networks.
| Company | Headquarters | Key Strengths |
|---|---|---|
| Ali Group | Italy | Diverse brand portfolio, global reach |
| Middleby Corporation | US | Innovation in cooking technology, acquisitions |
| Welbilt | US | Broad equipment range, strong service network |
| ITW | US | Food equipment division, commercial focus |
| Hoshizaki | Japan | Ice machines and refrigeration, quality reputation |
| Electrolux Professional | Sweden | Sustainability focus, European market leader |
Differentiation is driven by technological innovation, energy efficiency, and after-sales service. Competitive moats include proprietary technology, brand reputation, and extensive distribution networks. Our analysis suggests that mid-sized vendors face increasing pressure to consolidate or specialize to compete with global giants.
Buyers and operators must prioritize energy efficiency, total cost of ownership, and compliance with food safety regulations when selecting food service equipment. The shift toward IoT-enabled smart equipment offers significant operational benefits but requires investment in training and digital infrastructure. Procurement risks include supply chain delays, price volatility of raw materials like stainless steel, and the need for reliable after-sales support. Switching costs are moderate due to the specialized nature of commercial kitchens, but modular and multifunctional equipment can reduce future upgrade costs. Regulatory compliance, particularly regarding energy standards and hygiene, is non-negotiable and varies by region, so operators should verify certifications such as NSF, UL, and CE before purchase.
The balance of evidence favors a positive outlook for the Food Service Equipment Market, with strong growth driven by structural shifts in consumer behavior and technology adoption. However, the market is not without risks: high interest rates could dampen capital expenditure, and the fragmented nature of small operators may slow the pace of premiumization. The strongest counter-argument is that overcapacity in some regions (e.g., China) could lead to price wars and margin erosion, particularly in commodity equipment segments.
Our analysis suggests three actionable strategies for decision-makers:
We would change our conclusion if global food service spending declines for two consecutive quarters or if regulatory bans on certain materials accelerate unexpectedly. Evidence of prolonged supply chain disruptions or a sharp rise in interest rates would also warrant a more cautious stance.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.0% from 2020-2034 |
| Segmentation |
|
The market is valued at USD 44.4 billion in 2026, according to a consensus of published estimates, and is projected to reach USD 71.1 billion by 2033.
The market is expected to grow at a CAGR of 7.0% from 2026 to 2033, driven by demand from QSRs, cloud kitchens, and technological advancements.
Asia Pacific is the largest regional market, accounting for 37.4% of global revenue in 2025, followed by North America and Europe.
Key drivers include the growth of the hospitality sector, rising demand for convenience foods, technological advancements such as IoT and automation, and a focus on sustainability and energy efficiency.
Leading companies include Ali Group, Middleby Corporation, Welbilt, ITW, Hoshizaki, and Electrolux Professional, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 split between primary and secondary research. Primary research involves in-depth interviews with key stakeholders across the value chain, including raw material suppliers, specialized equipment producers, contract formulators, and global distributors. We conduct interviews with decision-makers such as VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads to gather granular insights into market dynamics, procurement trends, and technology adoption.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Technical Directors | 30% |
| Operations & Commercial Managers | 25% |
| Regulatory & Compliance Officers | 10% |
| Company Type | Representation (%) |
|---|---|
| Equipment Manufacturers | 45% |
| Component Suppliers | 25% |
| Distributors & Dealers | 20% |
| Service Providers | 10% |
We validate findings using official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards and industry associations such as ISO, NSF International, and the North American Association of Food Equipment Manufacturers (NAFEM).
We employ simultaneous top-down and bottom-up triangulation. Top-down modeling allocates macroeconomic and industry segment data to derive market size, while bottom-up modeling builds from manufacturer capacity, product pricing, and end-use consumption patterns. These approaches are cross-validated to ensure accuracy.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |