 North America Food Service Equipment Market
 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 229

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 North America Food Service Equipment Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2024 | 10.74 B |
| 2025 | 11.08 B |
| 2026 | 11.44 B |
| 2027 | 11.81 B |
| 2028 | 12.18 B |
| 2029 | 12.57 B |
| 2030 | 12.77 B |

The North America food service equipment market covers the manufacture and sale of commercial kitchen appliances, refrigeration, warewashing, food preparation, holding and storage, and serving equipment to restaurants, hotels, institutional kitchens, and other foodservice operators across the U.S., Canada, and Mexico. It is a specification-led, replacement-heavy capital goods market.
This analysis covers commercial-grade kitchen purpose equipment, food and beverage preparation equipment, refrigeration, warewashing, and food holding and storage equipment sold to full-service restaurants, quick-service restaurants, institutional kitchens, and independent operators across the U.S., Canada, and Mexico. It spans new-build and replacement occasions across traditional and online sales channels. This analysis does not cover residential appliances, vending machines, food trucks as vehicles, packaging machinery, or commercial laundry equipment.
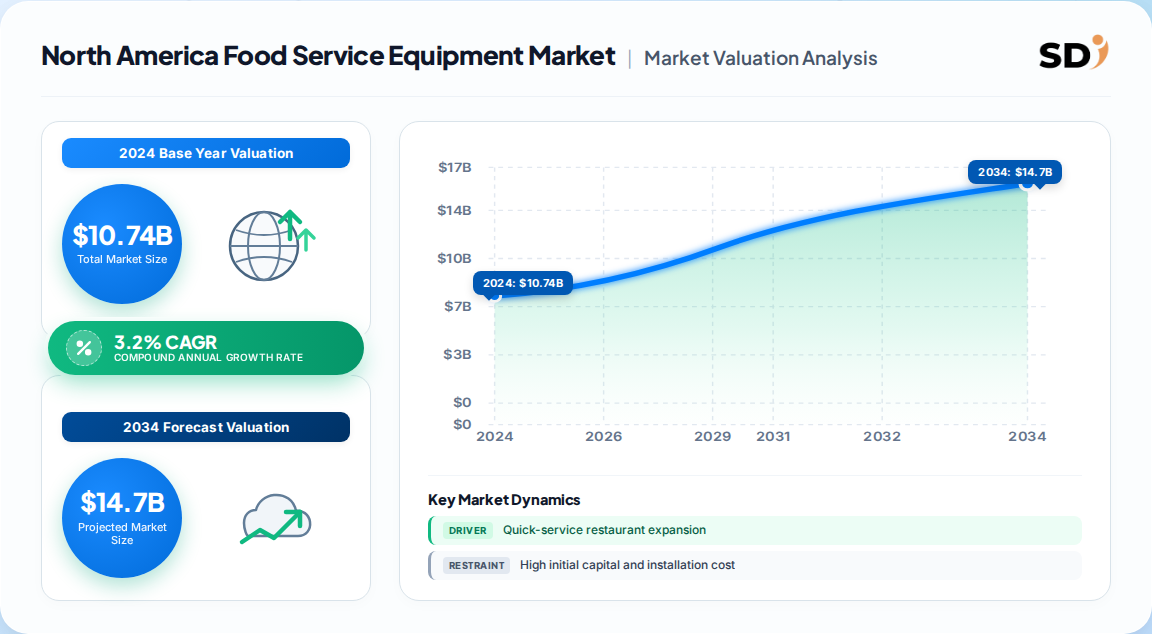
The most defensible regional figure is approximately 10.74 Billion in 2024, rising to 12.77 Billion by 2030 at 3.2% CAGR. A competing global analysis implies far higher growth, but that figure describes worldwide demand and should not be applied to this region.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 10.74 Billion | 2024 | 2030 | 3.2% | Regional commercial kitchen equipment, all channels | One published regional estimate |
| 12.77 Billion | 2030 | 2030 | 3.2% | Same regional scope, forecast endpoint | One published regional estimate |
| 41.5 Billion | 2025 | 2033 | 7.0% | Global food service equipment, all regions | A competing global analysis |
Our analysis suggests the 3.2% regional figure is more defensible than the 7.0% global one for North America. The region is a mature replacement market with high installed-base penetration; the 7.0% headline is inflated by Asia Pacific, which held 37.4% of global revenue in 2025 and is growing fastest. Applying global growth to North America is a common and expensive planning error.
Treat the 10.74 Billion base as a planning midpoint rather than a precise number. Definitional boundaries between kitchen purpose and food preparation equipment, and inconsistent treatment of installation and service revenue, can swing the base by several hundred million dollars. Vendors should triangulate against their own addressable installed base before committing capital.
Segmentation runs on five axes: product, end use, sales channel, purchase occasion, and operator type. Product and end use drive the most commercial variance.
| Parent segment | Children | 2024 position |
|---|---|---|
| Product | Kitchen purpose, food & beverage preparation, refrigeration, warewashing, food holding & storing, others | Kitchen purpose led at 36.9% |
| End use | Full-service restaurants, quick-service restaurants, institutional, independent restaurants, others | Independent restaurants led |
| Sales channel | Traditional (offline), online | Traditional led |
| Occasion | New build, replacement | New build led |
| End-use type | Chain, independent | Chain led |
Two nuances matter. First, the largest single product segment is not the fastest-growing one; food handling and storing equipment is forecast to outpace kitchen purpose equipment on delivery and takeout volume. Second, the end-use picture looks contradictory because "independent restaurants" and "chain" lead on different axes. This divergence implies that chain operators dominate spend per location while independents dominate the count of buying decisions, so route-to-market strategy must serve both a small number of large accounts and a long tail of small ones.
The U.S. leads decisively, accounting for roughly three-quarters of regional revenue on the strength of its restaurant density, hospitality chains, and regulatory-driven efficiency upgrades. Canada and Mexico follow at materially smaller scale.
Our analysis suggests the regional revenue distribution is close to 74% U.S., 15% Canada, 11% Mexico. Canada's demand tracks hotel and institutional renovation cycles more than restaurant unit growth, making it less volatile but slower. Mexico is where incremental volume growth concentrates, but import dependence and currency exposure raise landed cost risk for buyers.
The practical consequence: U.S. pricing and specification norms set the regional standard, while Mexico is the only sub-market where new-build occasion materially outpaces replacement. Vendors planning capacity should weight U.S. replacement demand for revenue stability and Mexico for growth optionality.
Growth is driven by QSR expansion, hotel food-and-beverage upgrades, and energy-efficiency regulation; it is restrained by high capital cost, maintenance burden, and a mature replacement cycle that caps volume upside.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| QSR and fast-casual expansion | Driver | Strong | High-volume automated fryers, griddles, and ovens required per unit |
| Hotel F&B diversification | Driver | Moderate | In-house restaurants and bars require specialized cooking and refrigeration |
| Energy-efficiency and emissions rules | Driver | Strong | Compliance forces early replacement of inefficient units |
| Smart/IoT equipment adoption | Driver | Moderate | Remote monitoring and predictive maintenance justify premium pricing |
| High initial capital and installation cost | Restraint | Strong | Deters small and mid-sized independent operators |
| Maintenance and accessory replacement cost | Restraint | Moderate | Raises total cost of ownership, slowing upgrade decisions |
| Raw material price volatility and import reliance | Restraint | Moderate | Heavy import dependence on China, Germany, Italy raises landed cost risk |
The balance favors cautious optimism. Drivers are structural and regulation-backed, which makes them relatively durable. Restraints are largely financial rather than structural, meaning they suppress timing rather than eliminate demand. The clearest second-order effect is that efficiency regulation effectively pulls forward replacement demand, compressing the natural replacement cycle and creating a demand air pocket once compliance deadlines pass. Vendors should not extrapolate compliance-driven spikes into baseline growth.
The vendor landscape is moderately concentrated, with large multi-brand groups and specialist manufacturers competing on breadth, service network, and energy performance.
| Company | Typical positioning | Differentiation lever |
|---|---|---|
| AB Electrolux | Broad commercial portfolio | Global brand and distribution reach |
| Ali Group | Multi-brand equipment group | Brand breadth across categories |
| The Middleby Corporation | Cooking and beverage solutions | Innovation pace and portfolio expansion |
| Illinois Tool Works | Component and equipment lines | Manufacturing scale and reliability |
| Dover Corporation | Refrigeration and foodservice systems | Engineering depth |
| Welbilt | Cooking and refrigeration | Chain-account specification strength |
| Hoshizaki | Ice and refrigeration | Category specialization |
| Duke Manufacturing | Serving and holding | Institutional relationships |
| The Vollrath Company | Smallwares and serving | Breadth of complementary lines |
Differentiation rests on three moats. First, specification lock-in: once an operator standardizes a platform, switching costs include retraining, spare-parts inventory, and service contracts. Second, service network density, which matters more than unit price in mission-critical downtime scenarios. Third, compliance credibility, where documented efficiency performance is a procurement gate rather than a differentiator.
Our analysis suggests consolidation will continue, with acquirers targeting refrigeration and warewashing specialists that add recurring service revenue. Portfolio breadth alone is no longer a durable moat; service attach rates are.
Buyers should optimize for total cost of ownership, not sticker price. Energy consumption, service response time, and spare-parts availability typically outweigh purchase price differences within two to three years of operation.
Procurement risk is concentrated in three areas. Import dependence on offshore components exposes buyers to tariff, freight, and currency shocks, so dual-sourcing agreements are prudent. Lead times for custom-specified equipment can extend well beyond standard catalog items, which matters for new-build schedules. And service-contract terms, including uptime guarantees and parts-depot proximity, should be negotiated at purchase rather than after failure.
Regulatory compliance is a gate, not a marketing claim. Buyers should require documented efficiency ratings and hygiene-standard conformity before specification. Switching costs are high and asymmetric: replacing a standardized platform means retraining staff and rebuilding spare-parts inventories, so standardizing too early can lock an operator into an underperforming platform for years. A deliberate two-vendor policy preserves leverage without sacrificing service depth.
The balance of evidence favors a replacement-led, efficiency-driven thesis over a volume-growth thesis. At 3.2% regional CAGR, North America is not a market where unit expansion carries the average vendor. Growth comes from price-mix improvement, efficiency upgrades, and service attachment. The strongest counter-argument is that Mexico's QSR and hotel build-out plus a U.S. replacement cycle bulge could push regional growth above 5% for a stretch; we regard this as plausible but not bankable, because it depends on construction timing that has historically slipped.
For operators, the implication is defensive: lock in service capability and spare-parts access now, before further consolidation tightens vendor leverage. For investors, the implication is selective: refrigeration, warewashing, and food holding are where recurring revenue and regulation-driven replacement intersect, which is a more durable earnings profile than pure cooking equipment. Note the data gap: published regional estimates rarely disclose service revenue separately from equipment revenue, which materially distorts valuation comparisons. Precise sub-segment and service-attach forecasting requires the full report's bottom-up modeling.
Actionable strategy:
Evidence that would change this conclusion: sustained regional construction permits and hotel pipeline data showing new-build occasion overtaking replacement, or a regulatory rollback that removes compliance-driven replacement pressure.
| Region | Market Share (%) |
|---|---|
| U.S. | 0.74% |
| Canada | 0.15% |
| Mexico | 0.11% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.2% from 2020-2034 |
| Segmentation |
|
The North America food service equipment market was valued at approximately 10.74 Billion in 2024 and is projected to reach 12.77 Billion by 2030. This reflects a mature, replacement-heavy regional market growing at roughly 3.2% annually, well below global growth rates.
Food handling and storing equipment is forecast to grow fastest, driven by takeout, delivery, and pre-packaged meal volume. Kitchen purpose equipment remains the largest segment at about 36.9% of 2024 revenue but grows more slowly, tracking replacement cycles rather than expansion.
The U.S. dominates, accounting for roughly three-quarters of regional revenue. Canada and Mexico follow at materially smaller scale, though Mexico shows the fastest build-out growth from quick-service restaurants and hotel food and beverage expansion.
High initial capital and installation costs, ongoing maintenance burden, and raw material price volatility restrain adoption, particularly among small and mid-sized independent operators. Import dependence on offshore components also raises landed cost risk and lengthens lead times.
Leading vendors include AB Electrolux, Ali Group, The Middleby Corporation, Illinois Tool Works, Dover Corporation, Welbilt, Hoshizaki, Duke Manufacturing, and The Vollrath Company. Competition centers on specification lock-in, service network density, and documented energy-efficiency compliance.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain with raw material and component suppliers, specialized equipment producers, contract manufacturers, and regional distributors. Decision-maker designations interviewed included VP-level sourcing executives, heads of product R&D, technical directors, and commercial operations leads responsible for specification and channel strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| Product R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Equipment Manufacturers | 40% |
| Component & Material Suppliers | 25% |
| Distributors & Dealers | 25% |
| Service & Maintenance Providers | 10% |
Findings were benchmarked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and recognized non-profit technical standards and industry associations. These sources validated import dependence patterns, pricing bands, and compliance requirements.
We ran simultaneous top-down macroeconomic and industry segment allocation alongside bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. Divergences between the two approaches were reconciled through weighted regression against historical replacement cycles and construction activity.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |