 Food Away From Home Market
 Size, Share & Forecast 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 209

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Food Away From Home Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 4.833 M |
| 2026 | 5.045 M |
| 2027 | 5.256 M |
| 2028 | 5.477 M |
| 2029 | 5.707 M |
| 2030 | 5.952 M |

The Food Away From Home market covers meals and beverages prepared and consumed outside the household, including restaurants, cafés, quick-service outlets, hotels, transport catering, institutional settings and retail foodservice. It captures value from dine-in, takeaway and delivery, spanning independent operators and chains across every eating occasion.
This analysis covers the global market for food prepared away from home across all ownership types, delivery models and occasion segments, spanning 2021 to 2030. This analysis does not cover packaged groceries, home-cooked food, food manufacturing for retail sale, agricultural commodities, or foodservice equipment and kitchen technology markets.
The market is best understood through three published estimates that diverge meaningfully on scale and momentum. Our analysis treats the 2026 base of roughly 5.0 trillion as the most defensible anchor because it sits between the most conservative and most optimistic readings.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 4833.08 Billion → 5952.18 Billion | 2025 → 2030 | 2026–2030 | 4.2% | Broad FAFH, occasion-led | One published estimate |
| 4.7 Trillion → 7.2 Trillion | 2025 → 2033 | 2026–2033 | 5.4% | Hospitality-dominant, wider horizon | A competing analysis |
| 4.3 Trillion → 5.9 Trillion | 2021 → 2031 | 2022–2031 | 2.3% | Legally framed, pre-pandemic base | A third industry benchmark |
The spread between 2.3% and 5.4% is not a data error; it reflects different start points, differing treatment of delivery platforms, and whether catering is fully captured. Our analysis suggests the 4.2% trajectory is the realistic central case for 2026–2030, with upside if digital ordering penetration accelerates in Asia-Pacific.
Segmentation follows occasion, ownership, delivery model and end application, each of which drives distinct economics and margin structures. The table below shows only the commercial dimensions used in this report.
| Parent segment | Children |
|---|---|
| Type of Occasion | Entertainment, Travel, Retail, Freestanding |
| Ownership Type | Independent, Chains |
| Delivery Model | Dine In, Take Away, Home Delivery |
| Application | Restaurants, Schools & Colleges, Hotels & Motels, Retail Stores & Vending, Others |
Travel is the single largest occasion segment, forecast to reach 2303.83 Billion by 2030, reflecting the structural coupling between tourism flows and foodservice spend. Restaurants remain the largest application, while dine-in retains the dominant delivery share at roughly 70%, even as home delivery grows fastest.
Asia-Pacific leads the global market with approximately 39% of revenue in 2025, and it is also the fastest-growing region, driven by urbanization in China, India and Southeast Asia. North America follows with roughly 24% and remains the most technologically mature.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.39% |
| North America | 0.24% |
| Europe | 0.2% |
| Latin America | 0.09% |
| Middle East & Africa | 0.07% |
| Region | Share (2025) |
|---|---|
| Asia-Pacific | 39.2% |
| North America | 24.3% |
| Europe | 20.1% |
| Latin America | 9.4% |
| Middle East & Africa | 7.0% |
Growth is driven by fast-food expansion, delivery-platform penetration, urbanization, dual-income households and tourism recovery, while food-safety compliance costs and price sensitivity restrain margin expansion. The balance favors volume growth over price growth through 2030.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Fast-food chain expansion | Driver | High | Density and value menus widen access |
| Delivery platforms and cloud kitchens | Driver | High | Lower friction, higher order frequency |
| Tourism and travel dining | Driver | High | 441.77 Billion incremental gain |
| Dual-income and time-poor households | Driver | Medium | Substitution of home cooking |
| Food safety and labeling regulation | Restraint | High | Compliance capex and audit burden |
| Food inflation and wage costs | Restraint | Medium | Menu-price ceilings compress margins |
The restraint side is underappreciated. Codex Alimentarius and FSMA-class regimes raise the fixed cost of entry, which disproportionately squeezes independents and accelerates chain consolidation in developed markets.
No single vendor holds a controlling share; the market remains fragmented across global chains, contract caterers and delivery aggregators. Differentiation rests on real-estate density, loyalty data and supply-chain resilience rather than menu alone.
| Company | Segment focus | Principal advantage |
|---|---|---|
| McDonald's Corporation | QSR, global | Scale, brand, franchise density |
| Starbucks Corporation | Café, global | Loyalty ecosystem, premium positioning |
| Compass Group PLC | Contract catering | Institutional contracts, retention |
| Yum! Brands | QSR, multi-brand | Emerging-market penetration, AI drive-thru |
| Domino's Pizza | Delivery-led | Digital ordering, asset-light model |
| DoorDash / Uber Eats | Aggregation | Demand capture, last-mile logistics |
Our analysis suggests aggregators are the structural winners in order frequency, while chains win on absolute ticket value. Contract caterers face the highest switching costs because institutional contracts are multi-year and compliance-heavy.
Procurement teams selecting foodservice partners should prioritize cold-chain reliability, allergen and labeling compliance, and multi-year pricing frameworks over headline unit cost. Switching costs are highest in institutional catering, where menu continuity, HACCP documentation and audit trails are contractually embedded. In retail and vending, the reverse is true: low switching costs mean vendors must compete on service frequency and range freshness.
The regulatory dimension is mission-critical. Operators in the EU face hygiene and traceability obligations under EU Food Law, while US operators must maintain FSMA-aligned preventive controls. Buyers should demand documented supplier verification and treat sustainability claims as audit items rather than marketing language, since tender scoring increasingly weights verified carbon and waste metrics.
The balance of evidence favors the 4.2% central trajectory over the more aggressive 5.4% reading, because the higher figure relies on sustained delivery-platform growth that will face regulatory and margin headwinds in mature markets. The strongest counter-argument is that AI-driven operational efficiency (self-order kiosks, drive-thru automation, dynamic pricing) could compress costs faster than expected and push growth toward the upper bound.
Our judgment is that value will migrate toward operators who own the customer relationship rather than the kitchen. Aggregators capture the data; chains that fail to build direct loyalty channels will become suppliers to someone else's platform. This is the single most important second-order effect in the dataset, and it is underweighted in most published forecasts.
The evidence that would change this conclusion is a sustained acceleration in Asia-Pacific delivery penetration combined with softening food-safety enforcement, which would justify upgrading to the 5.4% scenario. Precise sub-segment forecasting by occasion and city tier requires the full dataset, which this overview cannot substitute for.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.2% from 2020-2034 |
| Segmentation |
|
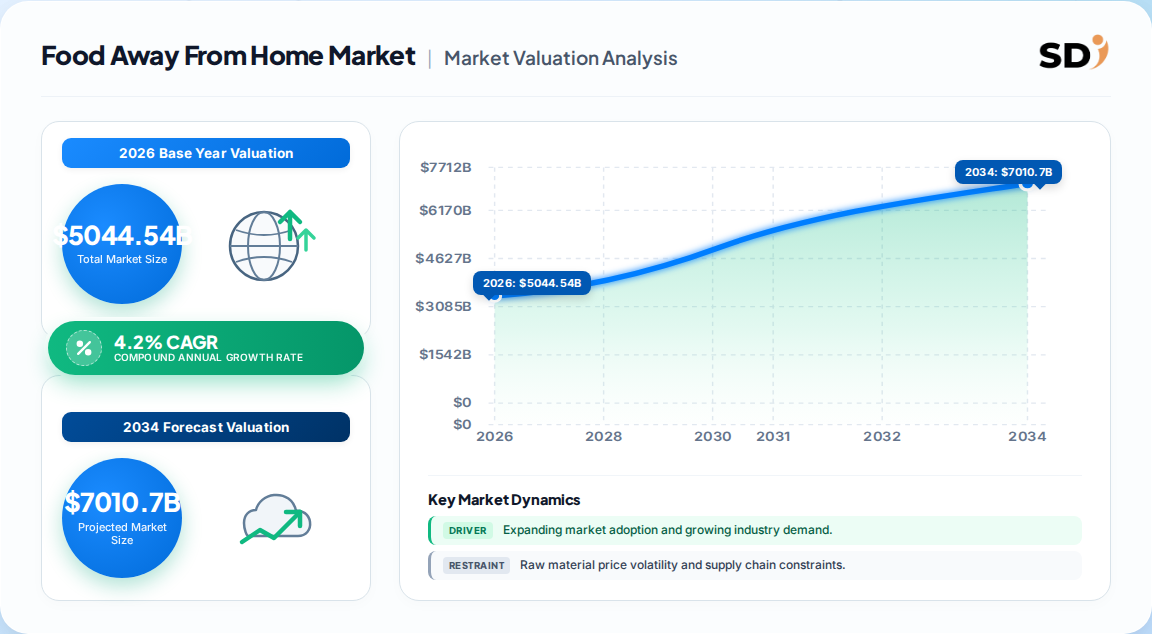
The global market is estimated at approximately 5044.54 Billion in 2026, up from 4833.08 Billion in 2025, reflecting steady post-pandemic normalization and continued delivery-led demand growth.
The market is forecast to grow at a 4.2% CAGR from 2026 to 2030, reaching 5952.18 Billion by 2030. More aggressive estimates of 5.4% hinge on faster Asia-Pacific delivery penetration.
Asia-Pacific leads with roughly 39% of global revenue in 2025, driven by urbanization in China and India. North America follows at about 24%, with Europe at approximately 20%.
Hospitality dominates the type mix with over 91% share, while travel is the largest occasion segment, expected to add 441.77 Billion in incremental value by 2030.
Leading players include McDonald's Corporation, Starbucks Corporation, Compass Group PLC, Yum! Brands and Domino's Pizza, alongside delivery aggregators such as DoorDash and Uber Eats.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct validation with value-chain participants. We conducted in-depth interviews with quick-service franchise operators, contract catering providers, foodservice distributors, cloud-kitchen platforms and institutional procurement teams across five regions. Decision-maker designations included VP of Sourcing, Head of Menu Innovation, Commercial Operations Leads and Quality & Compliance Directors, ensuring both demand-side and supply-side perspectives were captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| Commercial & Operations Directors | 30% |
| Menu Innovation & R&D Heads | 20% |
| Quality & Regulatory Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Quick-Service & Chain Restaurants | 42% |
| Contract Caterers & Institutional Providers | 26% |
| Foodservice Distributors & Wholesalers | 20% |
| Delivery Platforms & Cloud Kitchens | 12% |
Findings were cross-validated against official multilateral and governmental datasets, including UN Comtrade foodservice trade flows, Eurostat hospitality consumption indicators, US Bureau of Economic Analysis consumer spending data and US ITC sector filings. Corporate annual reports (10-K filings and investor presentations) of listed operators were reviewed for outlet counts, same-store sales and capex guidance. Patent and trademark databases supplemented technology-adoption signals, while Codex Alimentarius and FSMA frameworks informed regulatory overlays.
We run simultaneous top-down and bottom-up models. The top-down approach allocates macroeconomic consumption and tourism spend to foodservice categories, while the bottom-up model builds from outlet counts, average ticket size and transaction frequency. Divergence between the two is reconciled through demand elasticity and cross-border consumption flow analysis.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |