Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Canned Food Market by Product (Fruits & Vegetables, Meat, Fish/Seafood, Ready Meals, Condiments), by Type (Organic, Conventional), by Distribution Channel (Food Services, Retail), by Packaging (Metal Cans, Aluminum Cans, Steel Cans), by Application (Household Consumption, Foodservice Industry, Institutional Use), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, Australia), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, UAE) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 221
Canned Food Market Valuation and 2026-2033 Timeline
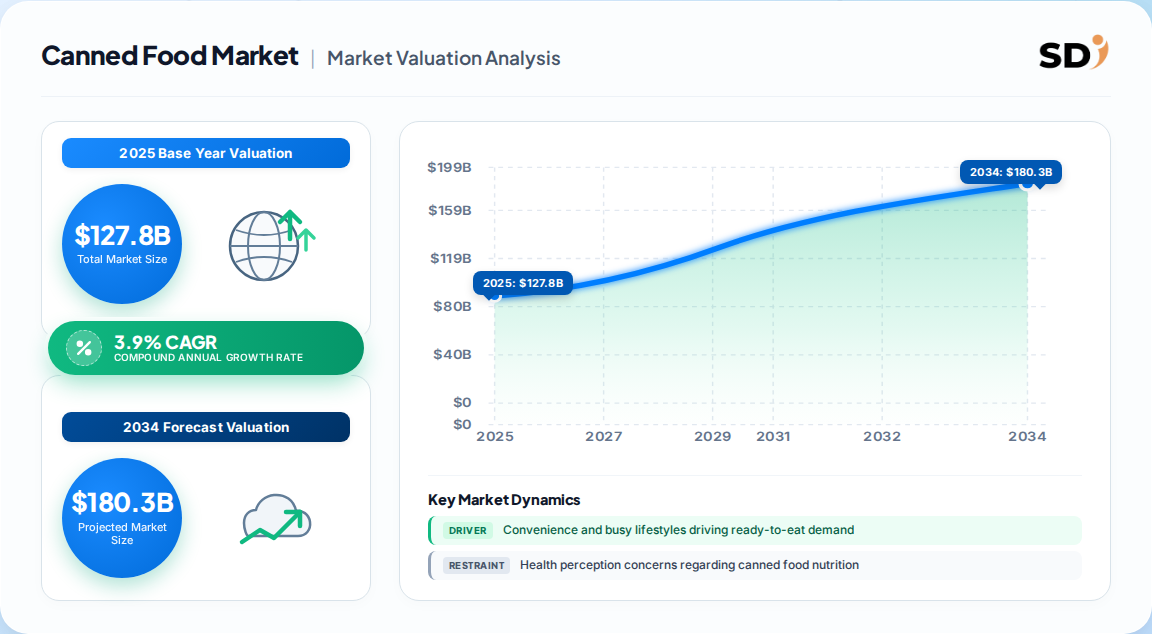
The global canned food market was valued at USD 127.8 billion in 2025 and is projected to grow from USD 132.8 billion in 2026 to USD 173.6 billion by 2033, expanding at a CAGR of 3.9% over the forecast period. This growth reflects sustained demand across retail and foodservice channels, underpinned by convenience, shelf stability, and product innovation.
Canned Food Market Size (In Billion)
200.0B
150.0B
100.0B
50.0B
0
127.8 B
2025
132.8 B
2026
138.0 B
2027
143.3 B
2028
148.9 B
2029
154.7 B
2030
160.8 B
2031
Canned Food Market Size (In Billion)
Year
Market Size
2025
127.8 B
2026
132.8 B
2027
138.0 B
2028
143.3 B
2029
148.9 B
2030
154.7 B
2031
160.8 B
Market size 2025: USD 127.8 billion
Market estimate 2026: USD 132.8 billion
Forecast 2033: USD 173.6 billion
CAGR 2026-2033: 3.9%
Largest region: Europe (38.0% revenue share, 2025)
Fastest-growing region: Asia Pacific
Region
2025 Share
Growth Outlook
Europe
38.0%
Mature, premiumization driven
North America
32.0%
Steady, emergency preparedness
Asia Pacific
24.0%
Fastest CAGR, urbanization
Rest of World
6.0%
Emerging, retail expansion
Fruits and Vegetables Segment Leadership
The canned fruits and vegetables segment led the market with the largest revenue share of over 30.0% in 2025. This dominance is driven by high nutritional retention from peak-ripeness canning, convenience, and versatility in meal preparation. The canned fish/seafood segment is expected to grow at the fastest CAGR of over 3.0% from 2026 to 2033, supported by ready-to-eat seafood trends, protein affordability, and innovations such as tinned fish tastings and boutique retail formats.
Canned ready meals: driven by dual-income households
Canned soups and sauces: steady demand in foodservice
Conventional Versus Organic Product Type Dynamics
The conventional segment dominated the market with a revenue share of over 88.0% in 2025, owing to lower production costs, wider availability, and an extensive distribution network. However, the organic segment is anticipated to grow at the fastest CAGR of approximately 7.5% from 2026 to 2033, fueled by health-conscious consumer preferences for clean-label, pesticide-free products and premiumization trends.
Type
2025 Share
CAGR 2026-2033
Conventional
88.0%
3.2%
Organic
12.0%
7.5%
Retail Channel Dominance and Foodservice Penetration
The retail distribution channel led the market with a revenue share of over 68.0% in 2025, driven by supermarkets, hypermarkets, and the rapid expansion of e-commerce grocery platforms. The foodservice segment remains a significant volume driver, particularly for canned ready meals and seafood in institutional catering. Online retail is gaining traction, particularly in Asia Pacific, where e-commerce grocery sales reached approximately USD 650 billion in 2024, with canned goods among the top purchased categories due to lightweight shipping and no refrigeration needs.
Retail: >68.0% share (2025), led by supermarkets and e-commerce
Foodservice: steady demand from restaurants and catering
E-commerce: fastest-growing sub-channel, particularly in Asia Pacific
Europe and Asia Pacific Regional Market Trends
Europe dominated the global market, accounting for the largest revenue share of 38.0% in 2025, supported by strict food safety standards, expanding private-label offerings, and strong demand for sustainably packaged canned proteins. Asia Pacific is the fastest-growing regional market, driven by urbanization (57% of the global population lived in cities in 2024, projected to reach 68% by 2050), rising incomes in China and India, and expanding modern retail channels. China's e-commerce market, valued at USD 2.16 trillion in online retail sales in 2024, is a key accelerator for canned food distribution.
Emergency preparedness, high per-capita consumption
Asia Pacific
24.0%
Urbanization, e-commerce, rising incomes
South America
4.0%
Expanding retail infrastructure
Middle East & Africa
2.0%
Emerging demand, food security initiatives
Trade Barriers and Import Duty Implications
Trade policy significantly influences canned food market dynamics. For instance, Lebanon's Decree 5497 (August 2019) imposed additional import duties of 7% to 20% on 18 product categories, including canned food, affecting EU exports. Such tariff measures can disrupt supply chains and elevate costs for exporters, prompting manufacturers to diversify sourcing or adjust pricing strategies. Additionally, non-tariff barriers such as the EU's RASFF (Rapid Alert System for Food and Feed) ensure stringent safety standards, influencing trade flows and compliance requirements for canned food products.
Lebanon's Decree 5497: 7-20% additional duties on canned food imports from the EU
RASFF notifications: safety and compliance alerts affecting market access
Tariff volatility: impacts margins for exporters and importers
Emergency Preparedness and Outdoor Recreation Demand
Canned food is integral to emergency kits and relief supplies, a demand driver reinforced by post-COVID-19 stockpiling behaviors. In the U.S., outdoor recreation participation reached a record 183.2 million in 2025, boosting demand for canned food during camping and hiking activities. The global frozen food market exceeding USD 295 billion in 2024 presents competition, but canned food's longer shelf life and no-refrigeration requirement maintain its distinct advantage.
U.S. outdoor recreation: 183.2 million participants (2025)
Emergency preparedness: structural demand for shelf-stable proteins
Competition from frozen food: USD 295 billion market in 2024
Health Perception, Packaging, and Competitive Landscape
Health perception remains a restraint: nearly 40% of consumers consider canned foods less nutritious than frozen, and 60% view them as inferior to fresh options. However, manufacturers are responding with BPA-free cans, low-sodium formulations, and organic variants to appeal to health-conscious consumers. The competitive landscape includes major players such as Nestlé S.A., Conagra Brands, Del Monte Foods, Hormel Foods, Campbell Soup Company, The Kraft Heinz Company, General Mills Inc., and Bolton Group. Recent developments include expansion of organic and clean-label canned product lines, sustainable packaging innovations, and e-commerce channel growth.
Company
Key Focus Areas
Nestlé S.A.
Broad portfolio, organic offerings
Conagra Brands
Ready meals, snacks
Del Monte Foods
Fruits and vegetables
Hormel Foods
Meat and seafood
Campbell Soup Company
Soups and sauces
The Kraft Heinz Company
Condiments and ready meals
General Mills Inc.
Organic and premium canned goods
Bolton Group
Seafood and specialty products
Canned Food Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Canned Food Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.9% from 2020-2034
Segmentation
By Product
Fruits & Vegetables
Meat
Fish/Seafood
Ready Meals
Condiments
By Type
Organic
Conventional
By Distribution Channel
Food Services
Retail
By Packaging
Metal Cans
Aluminum Cans
Steel Cans
By Application
Household Consumption
Foodservice Industry
Institutional Use
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
Australia
South America
Brazil
Argentina
Middle East & Africa
South Africa
UAE
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Fruits & Vegetables
5.1.2. Meat
5.1.3. Fish/Seafood
5.1.4. Ready Meals
5.1.5. Condiments
5.2. Market Analysis, Insights and Forecast - by Type
5.2.1. Organic
5.2.2. Conventional
5.3. Market Analysis, Insights and Forecast - by Distribution Channel
5.3.1. Food Services
5.3.2. Retail
5.4. Market Analysis, Insights and Forecast - by Packaging
5.4.1. Metal Cans
5.4.2. Aluminum Cans
5.4.3. Steel Cans
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Household Consumption
5.5.2. Foodservice Industry
5.5.3. Institutional Use
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Fruits & Vegetables
6.1.2. Meat
6.1.3. Fish/Seafood
6.1.4. Ready Meals
6.1.5. Condiments
6.2. Market Analysis, Insights and Forecast - by Type
6.2.1. Organic
6.2.2. Conventional
6.3. Market Analysis, Insights and Forecast - by Distribution Channel
6.3.1. Food Services
6.3.2. Retail
6.4. Market Analysis, Insights and Forecast - by Packaging
6.4.1. Metal Cans
6.4.2. Aluminum Cans
6.4.3. Steel Cans
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Household Consumption
6.5.2. Foodservice Industry
6.5.3. Institutional Use
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Fruits & Vegetables
7.1.2. Meat
7.1.3. Fish/Seafood
7.1.4. Ready Meals
7.1.5. Condiments
7.2. Market Analysis, Insights and Forecast - by Type
7.2.1. Organic
7.2.2. Conventional
7.3. Market Analysis, Insights and Forecast - by Distribution Channel
7.3.1. Food Services
7.3.2. Retail
7.4. Market Analysis, Insights and Forecast - by Packaging
7.4.1. Metal Cans
7.4.2. Aluminum Cans
7.4.3. Steel Cans
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Household Consumption
7.5.2. Foodservice Industry
7.5.3. Institutional Use
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Fruits & Vegetables
8.1.2. Meat
8.1.3. Fish/Seafood
8.1.4. Ready Meals
8.1.5. Condiments
8.2. Market Analysis, Insights and Forecast - by Type
8.2.1. Organic
8.2.2. Conventional
8.3. Market Analysis, Insights and Forecast - by Distribution Channel
8.3.1. Food Services
8.3.2. Retail
8.4. Market Analysis, Insights and Forecast - by Packaging
8.4.1. Metal Cans
8.4.2. Aluminum Cans
8.4.3. Steel Cans
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Household Consumption
8.5.2. Foodservice Industry
8.5.3. Institutional Use
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Fruits & Vegetables
9.1.2. Meat
9.1.3. Fish/Seafood
9.1.4. Ready Meals
9.1.5. Condiments
9.2. Market Analysis, Insights and Forecast - by Type
9.2.1. Organic
9.2.2. Conventional
9.3. Market Analysis, Insights and Forecast - by Distribution Channel
9.3.1. Food Services
9.3.2. Retail
9.4. Market Analysis, Insights and Forecast - by Packaging
9.4.1. Metal Cans
9.4.2. Aluminum Cans
9.4.3. Steel Cans
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Household Consumption
9.5.2. Foodservice Industry
9.5.3. Institutional Use
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Fruits & Vegetables
10.1.2. Meat
10.1.3. Fish/Seafood
10.1.4. Ready Meals
10.1.5. Condiments
10.2. Market Analysis, Insights and Forecast - by Type
10.2.1. Organic
10.2.2. Conventional
10.3. Market Analysis, Insights and Forecast - by Distribution Channel
10.3.1. Food Services
10.3.2. Retail
10.4. Market Analysis, Insights and Forecast - by Packaging
10.4.1. Metal Cans
10.4.2. Aluminum Cans
10.4.3. Steel Cans
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Household Consumption
10.5.2. Foodservice Industry
10.5.3. Institutional Use
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Nestlé S.A.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Conagra Brands
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Del Monte Foods
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Hormel Foods
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Campbell Soup Company
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. The Kraft Heinz Company
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. General Mills Inc.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Bolton Group
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
12. Research Methodology
List of Figures
Figure 1: Canned Food Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Canned Food Market Revenue (Billion), by Product 2026 & 2034
Figure 3: North America Canned Food Market Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Canned Food Market Revenue (Billion), by Type 2026 & 2034
Figure 5: North America Canned Food Market Revenue Share (%), by Type 2026 & 2034
Figure 6: North America Canned Food Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 7: North America Canned Food Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 8: North America Canned Food Market Revenue (Billion), by Packaging 2026 & 2034
Figure 9: North America Canned Food Market Revenue Share (%), by Packaging 2026 & 2034
Figure 10: North America Canned Food Market Revenue (Billion), by Application 2026 & 2034
Figure 11: North America Canned Food Market Revenue Share (%), by Application 2026 & 2034
Figure 12: North America Canned Food Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Canned Food Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Canned Food Market Revenue (Billion), by Product 2026 & 2034
Figure 15: Europe Canned Food Market Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Canned Food Market Revenue (Billion), by Type 2026 & 2034
Figure 17: Europe Canned Food Market Revenue Share (%), by Type 2026 & 2034
Table 16: Europe Canned Food Market Revenue Billion Forecast, by Product 2020 & 2034
Europe Canned Food Market Revenue Billion Forecast, by Type 2020 & 2034
Frequently Asked Questions
1. What is the current size of the global canned food market?
The global canned food market was valued at USD 127.8 billion in 2025 and is projected to reach USD 173.6 billion by 2033, growing at a CAGR of 3.9% from 2026 to 2033.
2. Which region dominates the canned food market?
Europe led the market with a 38.0% revenue share in 2025, driven by strict food safety standards, premium organic demand, and strong private-label growth.
3. What is the fastest-growing segment in the canned food market?
The organic canned food segment is expected to grow at a CAGR of approximately 7.5% from 2026 to 2033, fueled by health-conscious consumer preferences and clean-label trends.
4. Who are the key players in the canned food market?
Key players include Nestlé S.A., Conagra Brands, Del Monte Foods, Hormel Foods, Campbell Soup Company, The Kraft Heinz Company, General Mills Inc., and Bolton Group.
5. What are the main drivers of the canned food market?
Convenience, busy lifestyles, emergency preparedness, and expansion of retail and e-commerce channels are the primary growth drivers, supported by product innovation such as BPA-free and organic offerings.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of research effort is dedicated to primary research, including interviews with C-level executives, procurement managers, and technical directors across the canned food value chain.
We conduct in-depth interviews with 4–5 specific company types: canned food manufacturers, can and packaging suppliers, raw material (agricultural and seafood) suppliers, retail and e-commerce distributors, and foodservice operators.
Stakeholder job titles interviewed include Procurement Director, Supply Chain Manager, R&D Director, and Category Manager.
Primary research also involves plant visits and validation with industry associations such as the European Canned Food Association (CEPF), the North American Meat Institute, and the National Fisheries Institute.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Supply Chain Manager
25%
R&D Director
25%
Category Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Canned Food Manufacturers
35%
Can and Packaging Suppliers
25%
Raw Material Suppliers
20%
Retail and E-commerce Distributors
15%
Foodservice Operators
5%
Secondary Research & Industry Benchmarking
20–30% of research effort leverages secondary sources, including official databases such as UN Comtrade, Eurostat, US ITC, World Bank, and OECD, as well as trade statistics from the WTO and government agencies.
We benchmark against industry standards and regulations from the FDA, EFSA, and RASFF, ensuring compliance and safety considerations are integrated.
Financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook are used to analyze company financials and market trends.
All reports are updated to the date of purchase, incorporating the latest available data and market developments.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up market sizing uses specific quantitative metrics: per-capita canned food consumption, retail sales data from supermarket scanners, e-commerce transaction volumes, and foodservice procurement records.
Demand modeling incorporates macro-economic indicators such as urbanization rates, dual-income household percentages, and outdoor recreation participation statistics.
Segment-level forecasts are built using historical growth patterns, price elasticity, and innovation pipelines.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous cross-validation and expert review.
Data triangulation is performed across primary interviews, secondary sources, and our proprietary databases to ensure consistency.
Quality checks include outlier detection, trend analysis, and reconciliation with known industry benchmarks.
Final validation is conducted by our senior analyst panel before report delivery.
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 18: Europe Canned Food Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 19: Europe Canned Food Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 20: Europe Canned Food Market Revenue (Billion), by Packaging 2026 & 2034
Figure 21: Europe Canned Food Market Revenue Share (%), by Packaging 2026 & 2034
Figure 22: Europe Canned Food Market Revenue (Billion), by Application 2026 & 2034
Figure 23: Europe Canned Food Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Europe Canned Food Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Canned Food Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Canned Food Market Revenue (Billion), by Product 2026 & 2034
Figure 27: Asia Pacific Canned Food Market Revenue Share (%), by Product 2026 & 2034
Figure 28: Asia Pacific Canned Food Market Revenue (Billion), by Type 2026 & 2034
Figure 29: Asia Pacific Canned Food Market Revenue Share (%), by Type 2026 & 2034
Figure 30: Asia Pacific Canned Food Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 31: Asia Pacific Canned Food Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 32: Asia Pacific Canned Food Market Revenue (Billion), by Packaging 2026 & 2034
Figure 33: Asia Pacific Canned Food Market Revenue Share (%), by Packaging 2026 & 2034
Figure 34: Asia Pacific Canned Food Market Revenue (Billion), by Application 2026 & 2034
Figure 35: Asia Pacific Canned Food Market Revenue Share (%), by Application 2026 & 2034
Figure 36: Asia Pacific Canned Food Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Canned Food Market Revenue Share (%), by Country 2026 & 2034
Figure 38: South America Canned Food Market Revenue (Billion), by Product 2026 & 2034
Figure 39: South America Canned Food Market Revenue Share (%), by Product 2026 & 2034
Figure 40: South America Canned Food Market Revenue (Billion), by Type 2026 & 2034
Figure 41: South America Canned Food Market Revenue Share (%), by Type 2026 & 2034
Figure 42: South America Canned Food Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 43: South America Canned Food Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 44: South America Canned Food Market Revenue (Billion), by Packaging 2026 & 2034
Figure 45: South America Canned Food Market Revenue Share (%), by Packaging 2026 & 2034
Figure 46: South America Canned Food Market Revenue (Billion), by Application 2026 & 2034
Figure 47: South America Canned Food Market Revenue Share (%), by Application 2026 & 2034
Figure 48: South America Canned Food Market Revenue (Billion), by Country 2026 & 2034
Figure 49: South America Canned Food Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Canned Food Market Revenue (Billion), by Product 2026 & 2034
Figure 51: Middle East & Africa Canned Food Market Revenue Share (%), by Product 2026 & 2034
Figure 52: Middle East & Africa Canned Food Market Revenue (Billion), by Type 2026 & 2034
Figure 53: Middle East & Africa Canned Food Market Revenue Share (%), by Type 2026 & 2034
Figure 54: Middle East & Africa Canned Food Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 55: Middle East & Africa Canned Food Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 56: Middle East & Africa Canned Food Market Revenue (Billion), by Packaging 2026 & 2034
Figure 57: Middle East & Africa Canned Food Market Revenue Share (%), by Packaging 2026 & 2034
Figure 58: Middle East & Africa Canned Food Market Revenue (Billion), by Application 2026 & 2034
Figure 59: Middle East & Africa Canned Food Market Revenue Share (%), by Application 2026 & 2034
Figure 60: Middle East & Africa Canned Food Market Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Canned Food Market Revenue Share (%), by Country 2026 & 2034
Table 17:
Table 18: Europe Canned Food Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 19: Europe Canned Food Market Revenue Billion Forecast, by Packaging 2020 & 2034
Table 20: Europe Canned Food Market Revenue Billion Forecast, by Application 2020 & 2034
Table 21: Europe Canned Food Market Revenue Billion Forecast, by Country 2020 & 2034
 Canned Food Market