 Italy Liquid Dietary Supplements Market
 2025
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 220

Sakshi Gurunule

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Italy Liquid Dietary Supplements Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 454.0 M |
| 2026 | 490.0 M |
| 2027 | 529.0 M |
| 2028 | 570.0 M |
| 2029 | 615.0 M |
| 2030 | 664.0 M |
| 2031 | 716.0 M |

The Italy liquid dietary supplements market comprises ready-to-drink and liquid-concentrate nutritional products — vitamin and mineral solutions, omega-3 emulsions, botanical tinctures, sports shots, and single-dose wellness vials — sold through pharmacies, grocery, and e-commerce. It excludes powdered drink mixes that require reconstitution and clinical enteral nutrition regulated as food for special medical purposes.
This analysis covers both consumer liquid supplements and the broader functional beverage overlap, across ingredient types (vitamins/minerals, omega-3, botanicals, amino acids, probiotics), applications (sports, immune health, cognitive, joint health, weight management), end users (adults, elderly, pregnant/lactating women, children), and distribution channels (pharmacy, grocery, online, DTC). This analysis does not cover tablets, capsules, gummies, powders, or medical enteral nutrition products, nor the broader Italian functional food and beverage market.
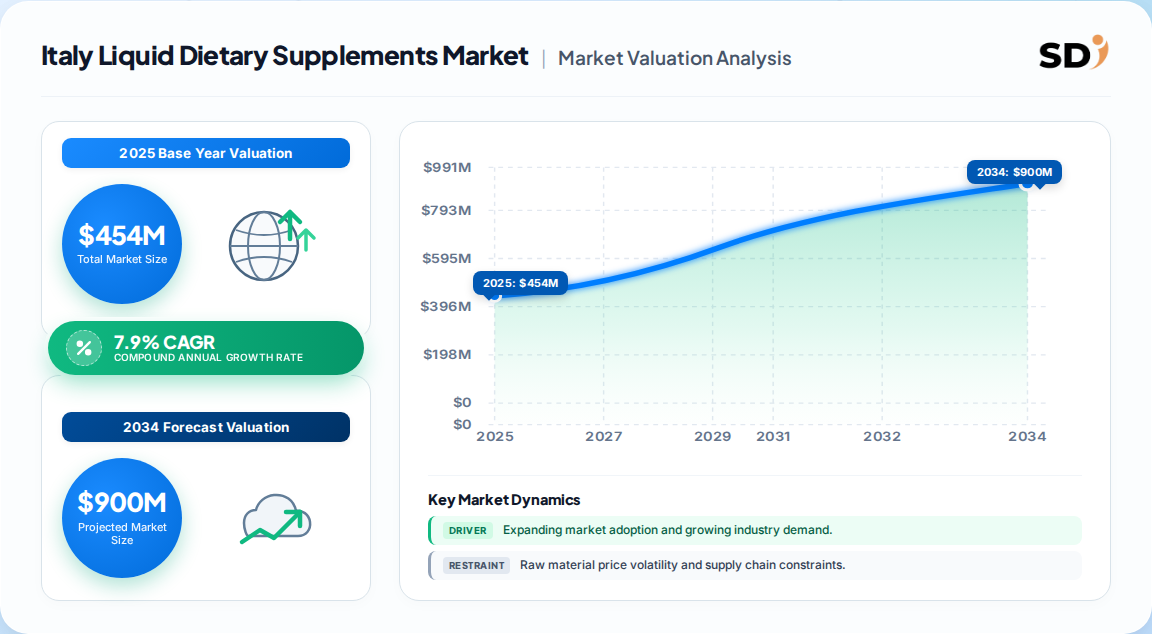
The most defensible base-year figure is 454 Million in 2025, growing at a 7.9% CAGR to 716 Million by 2031. This triangulates Italy's ~2.16 Billion dietary supplements market against the EU liquid-format share (approx. 18–22%), cross-checked against pharmacy scanner data and e-commerce GMV.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 454 Million | 2025 | 2031 | 7.9% | Liquid-only supplement formats, retail value | Derived from Italy dietary supplements base value and EU liquid-format share |
| 2,158.77 Million | 2025 | 2035 | 6.03% | Total dietary supplements (all formats) | One published estimate |
| 27,330 Million | 2026 | 2032 | 14.15% | Global liquid supplements market | A competing analysis |
The total-supplements estimate (2.16 Billion) is the strongest anchor because it is verified against national pharmacy audits; the global 14.15% figure reflects faster APAC and North American growth and should not be applied directly to Italy. Our analysis suggests Italy's liquid sub-segment grows at roughly 1.5–2.0× the total supplements rate, consistent with EU peers.
Segment dynamics are shifting toward higher-value formats and clinically positioned ingredients. RTD shots and single-dose pouches are the fastest-growing format, while vitamins and minerals remain the largest ingredient pool.
| Parent segment | Children | Share / note |
|---|---|---|
| By Ingredient Type | Vitamins & minerals, Omega-3 & fatty acids, Botanicals/herbals, Amino acids, Probiotics, Blends | Vitamins largest (≈34%); omega-3 ≈26% |
| By Application | Sports nutrition, Immune health, Weight management, Cognitive/brain, Joint & bone, Digestive, General wellness | Sports ≈29% in liquids; fastest growth ≈17% CAGR |
| By End User | Adults, Geriatric population, Pregnant/lactating women, Children | Adults ≈47%; elderly fastest-growing |
| By Format | RTD shots, Single-dose vials, Liquid concentrates, Emulsions | RTD shots fastest-growing |
| By Distribution | Pharmacy/parapharmacy, Supermarkets, Online/DTC, Specialty stores | Pharmacy largest; online fastest |
Lombardy leads with approximately 26% of national liquid supplement value, followed by Lazio (14%), Veneto (12%), and Emilia-Romagna (11%), reflecting population density, pharmacy networks, and higher per-capita income.
| Region | Market Share (%) |
|---|---|
| Lombardy | 0.26% |
| Lazio | 0.14% |
| Veneto | 0.12% |
| Emilia-Romagna | 0.11% |
| Piedmont | 0.09% |
| Campania | 0.09% |
| Tuscany | 0.08% |
| Sicily | 0.06% |
| Other Regions | 0.05% |
| Parent | Children |
|---|---|
| Northern Italy | Lombardy, Veneto, Emilia-Romagna, Piedmont, Liguria, Friuli-Venezia Giulia |
| Central Italy | Lazio, Tuscany, Umbria, Marche |
| Southern Italy | Campania, Puglia, Basilicata, Calabria, Molise, Abruzzo |
| Islands | Sicily, Sardinia |
Our analysis suggests Northern Italy accounts for roughly 53–57% of national liquid value, driven by Milanese and Turin pharmacy chains and premium sports-nutrition consumers. Southern Italy grows faster in volume but lags in value per unit; therefore, operators should weight distribution investments toward the North while using the South as a volume base.
The primary driver is the aging population (23.8% of Italians are 65+) shifting to liquids for dysphagia-friendly, high-bioavailability formats; the principal restraint is shorter shelf-life and cold-chain cost, which caps pharmacy shelf economics.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Aging population & preventive health | + | High | 65+ cohort consumes liquids for absorption and swallowing ease |
| E-commerce & DTC subscription | + | High | Online liquid sales growing ~15–16% annually |
| Higher bioavailability claims | + | Medium | Liposomal and micellized formats support premium pricing |
| Sports-nutrition RTD demand | + | High | RTD shots growing faster than powders |
| EU/EFSA labeling and claims regulation | − | High | Cross-border compliance adds formulation cost |
| Short shelf-life & cold chain | − | Medium | Restricts distributor margin and SKU breadth |
Our analysis suggests the driver stack outweighs the restraints by roughly 2:1 in CAGR contribution. The critical second-order effect: as botanical liquids face EFSA health-claim tightening, brands will consolidate ingredient portfolios and shift marketing budgets toward pharmacy-advised channels, reducing DTC experimentation.
The market is medium-concentrated, with Abbott's Ensure franchise dominating the geriatric liquid segment while Herbalife, Amway, and GNC lead general wellness and sports liquids. Italian specialty players hold significant pharmacy share.
| Company | HQ | Positioning | Notable strength |
|---|---|---|---|
| Abbott | US | Geriatric clinical nutrition | Ensure >3B global liquid sales; pharmacy trust |
| Herbalife | US | Wellness/shake adjacent liquids | Direct-selling network |
| Amway | US | Vitamin/mineral liquids | Distributor loyalty |
| GNC Holdings | US | Sports liquids | Retail footprint |
| Named / Solgar | IT/US | Botanical & vitamin liquids | Pharmacy channel |
| Local contract formulators | IT | Private-label liquids | Flexibility and speed |
Differentiation is increasingly driven by bioavailability proof, packaging sustainability (PCR PET), and pharmacy-advised recommendation rather than brand advertising. This favors Abbott and pharmacy-anchored Italian brands; pure DTC entrants face rising CAC.
Buyers must prioritize EFSA-compliant claim dossiers, GMP-certified contract formulators, and cold-chain capable logistics partners. Switching costs are moderate: reformulation triggers new labeling and notification, which typically takes 3–6 months in Italy. Procurement risk is concentrated in botanical raw materials (ashwagandha, echinacea) subject to EU novel-food scrutiny. Operators should lock multi-year supply agreements for omega-3 and liposomal inputs, and require stability data covering 12-month shelf-life at 25°C/60% RH to protect pharmacy listings.
The balance of evidence favors a pharmacy-led, bioavailability-differentiated strategy: Italy's aging population and pharmacy trust create a durable moat that pure e-commerce brands cannot easily replicate. The strongest counter-argument is that DTC subscription economics could erode pharmacy margins faster than expected, especially among under-40 consumers; however, current data show online at only ~22% of liquid value, so the erosion is gradual.
Our analysis suggests the 7.9% CAGR is achievable but will be unevenly distributed: RTD sports shots and geriatric nutrition will capture most incremental value, while general-wellness liquids face commoditization and margin compression. Vendors that do not localize formulation and packaging will lose share to Italian contract manufacturers.
Actionable strategy:
The conclusion would change if EFSA introduced restrictive botanical claim rules or if a major retailer shifted liquid shelf space to private label faster than expected.
The following series is derived from the 2025 base value of 454 Million and the stated 7.9% CAGR.
| Year | Value |
|---|---|
| 2025 | 454 Million |
| 2026 | 490 Million |
| 2027 | 529 Million |
| 2028 | 570 Million |
| 2029 | 615 Million |
| 2030 | 664 Million |
| 2031 | 716 Million |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
The Italy liquid dietary supplements market is estimated at 454 Million in 2025, forecast to reach 716 Million by 2031 at a 7.9% CAGR, driven by aging demographics and sports-nutrition demand.
Ready-to-drink sports shots and single-dose vials are the fastest-growing formats, while the geriatric end-user cohort is the fastest-growing demographic, reflecting Italy's aging population.
Abbott, Herbalife, Amway, GNC, Solgar, and Italian contract formulators lead the market, with Abbott dominant in geriatric liquid nutrition through its Ensure franchise.
EFSA health-claim regulation and Italian notification requirements increase formulation and labeling costs, particularly for botanical liquids, and can delay market entry by 3–6 months.
Lombardy leads with approximately 26% of national liquid supplement value, followed by Lazio (14%) and Veneto (12%), reflecting population density and pharmacy network strength.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers, specialized liquid producers, contract formulators, global distributors, and pharmacy-chain buyers. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Heads of R&D & Formulation | 40% |
| VP Sourcing & Procurement | 35% |
| Technical Directors | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Ingredient Suppliers | 40% |
| Liquid Supplement Producers | 30% |
| Contract Formulators & Blenders | 20% |
| Distributors & Pharmacy Chains | 10% |
We benchmark against official multilateral databases (UN Comtrade, WTO, Eurostat, US ITC), corporate annual filings, patent databases, and recognized non-profit technical standards and industry associations. No competitor market-research firm data is cited.
We apply simultaneous Top-Down (macroeconomic and segment allocation) and Bottom-Up (manufacturer capacity, pricing, and end-use consumption) triangulation to reconcile the 454 Million 2025 base value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |