Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Hybrid Beverages Market: Size, Share & Growth to 2035
Hybrid Beverages Market
Hybrid Beverages Market: Size, Share & Growth to 2035
Hybrid Beverages Market by Product Type (Non-Alcoholic Beverages, Alcoholic Beverages, Functional Beverages, Dairy-Based, Plant-Based, Others), by Beverage Base (Tea-Based, Coffee-Based, Juice-Based, Botanical/Herbal, Others), by Distribution Channel (Supermarkets & Hypermarkets, Convenience Stores, Specialty Stores, Online Retail, Foodservice/On-Trade, Others), by Packaging Type (Bottles, Cans, Cartons, Pouches, Others), by Form (Liquid/RTD, Concentrates, Powdered Mixes), by Functionality (Hydration, Energy Boost, Immunity Support, Detoxification, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Nigeria) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 275
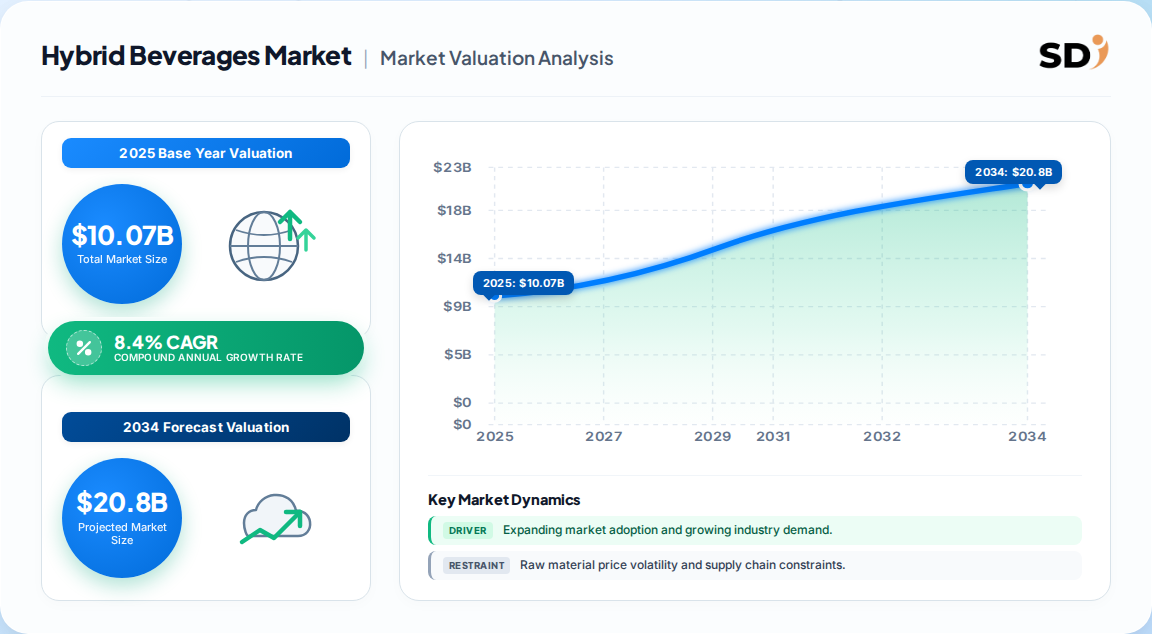
The global hybrid beverages market was valued at USD 10.07 billion in 2025 and is projected to reach about USD 24.2 billion by 2035, per a consensus of published estimates.
Forecast CAGR clusters between 6.5% and 9.1%, with our blended working rate of 8.4% reflecting the mid-to-upper bound of credible analyses.
Non-alcoholic hybrids hold roughly 64% of revenue, led by functional, ready-to-drink formats; alcoholic hybrids are the faster-growing niche.
Off-trade channels account for about 75% of sales, but on-trade is expanding fastest as bars and cafés premiumize menus.
North America leads with ~31% share; Asia-Pacific is the fastest-growing region, forecast at 6.8%–9% CAGR through the horizon.
Leading players include PepsiCo, Coca-Cola, Nestlé, Keurig Dr Pepper, Starbucks, Diageo, Heineken and Suntory.
Why this matters for decision-makers: the winning position is no longer "better-for-you" alone—it is multi-benefit formulation at an accessible price, because production complexity and regulatory drag are squeezing margins for undifferentiated entrants.
Hybrid Beverages Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
10.07 B
2025
10.92 B
2026
11.84 B
2027
12.83 B
2028
13.91 B
2029
15.08 B
2030
16.35 B
2031
Hybrid Beverages Market Size (In Billion)
Year
Market Size
2025
10.07 B
2026
10.92 B
2027
11.84 B
2028
12.83 B
2029
13.91 B
2030
15.08 B
2031
16.35 B
What is the Hybrid Beverages Market?
Hybrid beverages are drinks that fuse two or more conventional beverage categories—tea with juice, coffee with energy ingredients, alcohol with functional botanicals—into a single product. They combine refreshment with wellness, convenience and novel flavor, spanning ready-to-drink, functional, fermented and alcoholic formats sold through retail and foodservice.
Scope: what this report covers and excludes
This report covers the global hybrid beverages market across product type, beverage base, distribution channel, packaging, form and end user, with regional breakdowns for North America, Europe, Asia-Pacific, Latin America and the Middle East & Africa. It addresses both alcoholic and non-alcoholic hybrids.
This analysis does not cover conventional single-category beverages (standard carbonated soft drinks, pure juices, traditional beer and wine), nor does it cover beverage processing equipment as a standalone market or raw ingredient commodity pricing.
How big is the market for Hybrid Beverages Market?
Published estimates for the global hybrid beverages market diverge materially—from USD 8.26 billion (2023) to USD 10.07 billion (2025)—because each publisher defines "hybrid" differently, particularly whether functional waters and alcoholic-non-alcoholic blends are included.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 8.26 Billion
2023
2030
6.2%
Alcoholic + non-alcoholic hybrids; on/off-trade
One published estimate
USD 10.07 Billion
2025
2035
9.14%
Product type + beverage base; broad functional inclusion
A competing analysis
USD 10.1 Billion
2025
2035
8.4%
Functional, RTD, alcoholic and plant-based hybrids
A third published analysis
USD 14.6 Billion
2026
2033
6.5%
Functional-led, broader ingredient scope
A fourth published analysis
Our analysis suggests the USD 10.0–10.1 billion 2025 figure is the most defensible base: it reconciles the narrower 2023 estimate once two years of mid-single-digit growth and a broader functional definition are applied. The 9.14% CAGR appears optimistic because it assumes functional hybrids sustain early-adoption momentum across all regions; the 6.5% figure is conservative. A blended 8.4% CAGR producing roughly USD 24.2 billion by 2035 is the working consensus this report adopts.
How is the market segmented?
The market segments primarily by product type and beverage base, with distribution channel, packaging and functionality layering commercial nuance on top. Non-alcoholic and functional formats dominate revenue; RTD is the dominant product format.
Hydration, Energy Boost, Immunity Support, Detoxification, Others
Two segmentation insights matter commercially. First, the functional segment is the fastest-growing type, which pulls ingredient complexity—probiotics, adaptogens, electrolytes—into formulations that were once simple. Second, the beverage-base split (tea, coffee, juice) determines supplier sourcing and shelf-life engineering more than the product-type label does.
Which region leads in Hybrid Beverages Market?
North America leads the global hybrid beverages market with roughly 31% of revenue, supported by high functional-beverage awareness and mature retail infrastructure. Asia-Pacific is the fastest-growing region, with Europe a strong premium-craft second.
Hybrid Beverages Market Regional Market Share
Loading chart...
Hybrid Beverages Market Regional Market Share
Region
Market Share (%)
North America
0.31%
Europe
0.26%
Asia-Pacific
0.29%
Latin America
0.08%
Middle East & Africa
0.06%
Global
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain, Netherlands
Asia-Pacific — China, Japan, India, South Korea, Australia
Latin America — Brazil, Mexico, Argentina, Chile
Middle East & Africa — Saudi Arabia, UAE, South Africa, Nigeria
Region
Share (2025/26)
Growth Profile
North America
~31%
Mature, innovation-led; U.S. CAGR ~8.4%
Asia-Pacific
~29%
Fastest-growing; ~6.8%–9% CAGR
Europe
~26%
Premium/craft focus; ~5.8% CAGR
Latin America
~8%
Emerging, urban-driven
Middle East & Africa
~6%
Early-stage, distribution-constrained
The divergence is instructive. North America's lead is a function of definitional breadth—functional waters and energy hybrids are counted as hybrids there—while Asia-Pacific's growth reflects genuine demand expansion from urbanization and rising middle-class health spending. Europe's slower headline CAGR masks stronger premium price realization, meaning volume and value tell different stories.
What is driving growth — and what is holding it back?
Growth is driven by consumer demand for multifunctional, convenient and clean-label drinks, while restraint comes from formulation cost, shelf-life complexity and fragmented regulations on health claims.
Factor
Direction
Evidence Strength
Mechanism
Multifunctional wellness demand
Driver
High
One drink delivers hydration + energy/immunity
Clean-label & low-sugar reformulation
Driver
High
Natural ingredients, reduced sugar, transparency
RTD convenience & retail expansion
Driver
High
On-the-go consumption; wider shelf space
Flavor innovation (yuzu, botanicals)
Driver
Medium
Novelty drives trial and premium pricing
Production cost & formulation complexity
Restraint
Medium
Stability, shelf-life and consistency challenges
Regulatory complexity on claims
Restraint
High
Divergent FDA/EFSA labeling and claim rules
The balance favors growth, but not evenly. Our analysis suggests the restraint side is underweighted by bullish forecasts: regulatory divergence across the U.S., EU and Asia forces region-specific formulations, which raises compliance cost and lengthens time-to-market—an advantage to scaled incumbents and a barrier to emerging brands.
Who are the leading vendors?
The competitive landscape blends global beverage majors with specialist functional and craft brands. Incumbents leverage distribution and brand equity; challengers win on formulation agility and niche positioning.
Company
Primary Hybrid Strength
Strategic Moat
PepsiCo
Prebiotic cola, energy-infused sparkling water
Scale, distribution, brand portfolio
The Coca-Cola Company
Topo Chico hard seltzer (with Molson Coors)
Global reach, alcoholic partnerships
Nestlé
Encapsulation tech for functional nutrition
R&D and formulation IP
Keurig Dr Pepper
Caffeine-sparkling water (Limitless acquisition)
Portfolio diversification, premium water
Starbucks
Nitro cold brew and coffee hybrids
Brand experience, café channel
Diageo / Heineken
Alcoholic hybrids and RTD cocktails
On-trade relationships, premium spirits
Suntory / Asahi
Tea, coffee and functional hybrids in Asia
Regional depth and local ingredients
Differentiation is shifting from flavor novelty toward proprietary functional technology. Nestlé's encapsulation and PepsiCo's prebiotic formulation illustrate that defensibility now rests on ingredient science and regulatory clearance, not marketing alone.
What do buyers and operators need to know?
Buyers and operators must weigh formulation stability, regulatory clearance and channel economics before committing to a hybrid portfolio. The critical selection criteria are proven shelf-life performance, transparent functional-ingredient sourcing (probiotics, adaptogens, electrolytes) and a manufacturer's ability to support region-specific labeling.
Procurement risk centers on ingredient supply concentration and reformulation lock-in: switching a functional ingredient often triggers re-validation of stability and claims, raising switching costs. Operators should also model channel mix carefully—off-trade delivers reach and margin efficiency, but on-trade drives trial and premium pricing, and the two require different packaging and support. Regulatory compliance is non-negotiable: FDA and EFSA differ on permissible health claims, so a single global formulation is rarely viable. Finally, buyers should scrutinize cost-per-serving against functional payload—premium pricing is only defensible where the benefit is measurable and claimable.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a cautiously bullish outlook: the market is real, growing at a blended 8.4% CAGR, and structurally supported by wellness and convenience megatrends. But the spread of published forecasts—6.2% to 9.14%—reveals definitional instability, and buyers should treat headline sizes skeptically until segment boundaries are fixed.
The strongest counter-argument is that "hybrid" is a marketing label rather than a durable category; if functional waters, hard seltzers and coffee-energy drinks are simply adjacent categories converging, the premium attached to the label may erode as mainstream brands copy formulations. Our view is that formulation IP and regulatory clearance will separate winners from copycats, preserving margin for those who invest in science.
Actionable Strategy:
Prioritize functional hybrids with defensible ingredient technology and clear claim pathways in target regions.
Build dual-channel capability—off-trade for reach, on-trade for premium trial—rather than optimizing for one.
Secure multi-region regulatory and formulation support before scaling, as compliance is the primary growth bottleneck.
Evidence that would change our conclusion: a sustained slowdown in functional-beverage adoption in North America, or regulatory harmonization that commoditizes functional claims, would push us toward the conservative 6.5% scenario.
Hybrid Beverages Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Hybrid Beverages Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.4% from 2020-2034
Segmentation
By Product Type
Non-Alcoholic Beverages
Alcoholic Beverages
Functional Beverages
Dairy-Based
Plant-Based
Others
By Beverage Base
Tea-Based
Coffee-Based
Juice-Based
Botanical/Herbal
Others
By Distribution Channel
Supermarkets & Hypermarkets
Convenience Stores
Specialty Stores
Online Retail
Foodservice/On-Trade
Others
By Packaging Type
Bottles
Cans
Cartons
Pouches
Others
By Form
Liquid/RTD
Concentrates
Powdered Mixes
By Functionality
Hydration
Energy Boost
Immunity Support
Detoxification
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Chile
Middle East & Africa
Saudi Arabia
UAE
South Africa
Nigeria
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Non-Alcoholic Beverages
5.1.2. Alcoholic Beverages
5.1.3. Functional Beverages
5.1.4. Dairy-Based
5.1.5. Plant-Based
5.1.6. Others
5.2. Market Analysis, Insights and Forecast - by Beverage Base
5.2.1. Tea-Based
5.2.2. Coffee-Based
5.2.3. Juice-Based
5.2.4. Botanical/Herbal
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Distribution Channel
5.3.1. Supermarkets & Hypermarkets
5.3.2. Convenience Stores
5.3.3. Specialty Stores
5.3.4. Online Retail
5.3.5. Foodservice/On-Trade
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Packaging Type
5.4.1. Bottles
5.4.2. Cans
5.4.3. Cartons
5.4.4. Pouches
5.4.5. Others
5.5. Market Analysis, Insights and Forecast - by Form
5.5.1. Liquid/RTD
5.5.2. Concentrates
5.5.3. Powdered Mixes
5.6. Market Analysis, Insights and Forecast - by Functionality
5.6.1. Hydration
5.6.2. Energy Boost
5.6.3. Immunity Support
5.6.4. Detoxification
5.6.5. Others
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Non-Alcoholic Beverages
6.1.2. Alcoholic Beverages
6.1.3. Functional Beverages
6.1.4. Dairy-Based
6.1.5. Plant-Based
6.1.6. Others
6.2. Market Analysis, Insights and Forecast - by Beverage Base
6.2.1. Tea-Based
6.2.2. Coffee-Based
6.2.3. Juice-Based
6.2.4. Botanical/Herbal
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by Distribution Channel
6.3.1. Supermarkets & Hypermarkets
6.3.2. Convenience Stores
6.3.3. Specialty Stores
6.3.4. Online Retail
6.3.5. Foodservice/On-Trade
6.3.6. Others
6.4. Market Analysis, Insights and Forecast - by Packaging Type
6.4.1. Bottles
6.4.2. Cans
6.4.3. Cartons
6.4.4. Pouches
6.4.5. Others
6.5. Market Analysis, Insights and Forecast - by Form
6.5.1. Liquid/RTD
6.5.2. Concentrates
6.5.3. Powdered Mixes
6.6. Market Analysis, Insights and Forecast - by Functionality
6.6.1. Hydration
6.6.2. Energy Boost
6.6.3. Immunity Support
6.6.4. Detoxification
6.6.5. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Non-Alcoholic Beverages
7.1.2. Alcoholic Beverages
7.1.3. Functional Beverages
7.1.4. Dairy-Based
7.1.5. Plant-Based
7.1.6. Others
7.2. Market Analysis, Insights and Forecast - by Beverage Base
7.2.1. Tea-Based
7.2.2. Coffee-Based
7.2.3. Juice-Based
7.2.4. Botanical/Herbal
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by Distribution Channel
7.3.1. Supermarkets & Hypermarkets
7.3.2. Convenience Stores
7.3.3. Specialty Stores
7.3.4. Online Retail
7.3.5. Foodservice/On-Trade
7.3.6. Others
7.4. Market Analysis, Insights and Forecast - by Packaging Type
7.4.1. Bottles
7.4.2. Cans
7.4.3. Cartons
7.4.4. Pouches
7.4.5. Others
7.5. Market Analysis, Insights and Forecast - by Form
7.5.1. Liquid/RTD
7.5.2. Concentrates
7.5.3. Powdered Mixes
7.6. Market Analysis, Insights and Forecast - by Functionality
7.6.1. Hydration
7.6.2. Energy Boost
7.6.3. Immunity Support
7.6.4. Detoxification
7.6.5. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Non-Alcoholic Beverages
8.1.2. Alcoholic Beverages
8.1.3. Functional Beverages
8.1.4. Dairy-Based
8.1.5. Plant-Based
8.1.6. Others
8.2. Market Analysis, Insights and Forecast - by Beverage Base
8.2.1. Tea-Based
8.2.2. Coffee-Based
8.2.3. Juice-Based
8.2.4. Botanical/Herbal
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by Distribution Channel
8.3.1. Supermarkets & Hypermarkets
8.3.2. Convenience Stores
8.3.3. Specialty Stores
8.3.4. Online Retail
8.3.5. Foodservice/On-Trade
8.3.6. Others
8.4. Market Analysis, Insights and Forecast - by Packaging Type
8.4.1. Bottles
8.4.2. Cans
8.4.3. Cartons
8.4.4. Pouches
8.4.5. Others
8.5. Market Analysis, Insights and Forecast - by Form
8.5.1. Liquid/RTD
8.5.2. Concentrates
8.5.3. Powdered Mixes
8.6. Market Analysis, Insights and Forecast - by Functionality
8.6.1. Hydration
8.6.2. Energy Boost
8.6.3. Immunity Support
8.6.4. Detoxification
8.6.5. Others
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Non-Alcoholic Beverages
9.1.2. Alcoholic Beverages
9.1.3. Functional Beverages
9.1.4. Dairy-Based
9.1.5. Plant-Based
9.1.6. Others
9.2. Market Analysis, Insights and Forecast - by Beverage Base
9.2.1. Tea-Based
9.2.2. Coffee-Based
9.2.3. Juice-Based
9.2.4. Botanical/Herbal
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by Distribution Channel
9.3.1. Supermarkets & Hypermarkets
9.3.2. Convenience Stores
9.3.3. Specialty Stores
9.3.4. Online Retail
9.3.5. Foodservice/On-Trade
9.3.6. Others
9.4. Market Analysis, Insights and Forecast - by Packaging Type
9.4.1. Bottles
9.4.2. Cans
9.4.3. Cartons
9.4.4. Pouches
9.4.5. Others
9.5. Market Analysis, Insights and Forecast - by Form
9.5.1. Liquid/RTD
9.5.2. Concentrates
9.5.3. Powdered Mixes
9.6. Market Analysis, Insights and Forecast - by Functionality
9.6.1. Hydration
9.6.2. Energy Boost
9.6.3. Immunity Support
9.6.4. Detoxification
9.6.5. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Non-Alcoholic Beverages
10.1.2. Alcoholic Beverages
10.1.3. Functional Beverages
10.1.4. Dairy-Based
10.1.5. Plant-Based
10.1.6. Others
10.2. Market Analysis, Insights and Forecast - by Beverage Base
10.2.1. Tea-Based
10.2.2. Coffee-Based
10.2.3. Juice-Based
10.2.4. Botanical/Herbal
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by Distribution Channel
10.3.1. Supermarkets & Hypermarkets
10.3.2. Convenience Stores
10.3.3. Specialty Stores
10.3.4. Online Retail
10.3.5. Foodservice/On-Trade
10.3.6. Others
10.4. Market Analysis, Insights and Forecast - by Packaging Type
10.4.1. Bottles
10.4.2. Cans
10.4.3. Cartons
10.4.4. Pouches
10.4.5. Others
10.5. Market Analysis, Insights and Forecast - by Form
10.5.1. Liquid/RTD
10.5.2. Concentrates
10.5.3. Powdered Mixes
10.6. Market Analysis, Insights and Forecast - by Functionality
10.6.1. Hydration
10.6.2. Energy Boost
10.6.3. Immunity Support
10.6.4. Detoxification
10.6.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Hybrid Beverages Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Hybrid Beverages Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Hybrid Beverages Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Hybrid Beverages Market Revenue (Billion), by Beverage Base 2026 & 2034
Figure 5: North America Hybrid Beverages Market Revenue Share (%), by Beverage Base 2026 & 2034
Figure 6: North America Hybrid Beverages Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 7: North America Hybrid Beverages Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 8: North America Hybrid Beverages Market Revenue (Billion), by Packaging Type 2026 & 2034
Figure 9: North America Hybrid Beverages Market Revenue Share (%), by Packaging Type 2026 & 2034
Figure 10: North America Hybrid Beverages Market Revenue (Billion), by Form 2026 & 2034
Figure 11: North America Hybrid Beverages Market Revenue Share (%), by Form 2026 & 2034
Figure 12: North America Hybrid Beverages Market Revenue (Billion), by Functionality 2026 & 2034
Figure 13: North America Hybrid Beverages Market Revenue Share (%), by Functionality 2026 & 2034
Figure 14: North America Hybrid Beverages Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Hybrid Beverages Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Hybrid Beverages Market Revenue (Billion), by Product Type 2026 & 2034
List of Tables
Table 1: Hybrid Beverages Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Hybrid Beverages Market Revenue Billion Forecast, by Beverage Base 2020 & 2034
Table 3: Hybrid Beverages Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 4: Hybrid Beverages Market Revenue Billion Forecast, by Packaging Type 2020 & 2034
Table 5: Hybrid Beverages Market Revenue Billion Forecast, by Form 2020 & 2034
The global hybrid beverages market was valued at roughly USD 10.07 billion in 2025 and is projected to reach about USD 24.2 billion by 2035, growing at a blended CAGR of approximately 8.4%.
2. Which region leads the hybrid beverages market?
North America leads with roughly 31% of global revenue, supported by functional-beverage awareness and mature retail. Asia-Pacific is the fastest-growing region, driven by urbanization and rising health spending.
3. What are the main drivers of hybrid beverage demand?
Demand is driven by consumer preference for multifunctional wellness drinks, clean-label and low-sugar formulations, RTD convenience, and novel flavor innovation such as botanical and exotic-fruit blends.
4. What challenges constrain the hybrid beverages market?
Key restraints include high formulation and production costs, shelf-life and stability complexity, and divergent regulatory rules on functional claims across the U.S., EU and Asia, which raise compliance costs.
5. Who are the leading hybrid beverage companies?
Leading players include PepsiCo, The Coca-Cola Company, Nestlé, Keurig Dr Pepper, Starbucks, Diageo, Heineken, Suntory and Asahi, alongside specialist functional and craft brands.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applied a 70/30 primary-to-secondary split, prioritizing direct industry engagement. In-depth interviews were conducted across the value chain with raw material and functional-ingredient suppliers, specialized hybrid beverage producers, contract formulators and blenders, and global distributors. Respondents included VP-level Sourcing leads, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring both technical and commercial perspectives informed our sizing and forecasts.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Regulatory Affairs Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Functional Ingredient Suppliers
30%
Specialized Hybrid Producers
35%
Contract Formulators & Blenders
20%
Global Distributors
15%
Secondary Benchmarking & Public Trade Validation
We triangulated findings against official multilateral trade and standards databases, including UN Comtrade, WTO, US ITC and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases and recognized technical standards and industry associations. This validation anchored hybrid beverage values to verifiable trade and corporate disclosures.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing and end-use consumption) modeling, reconciling the two to produce a defensible base-year value, forecast horizon and regional distribution.


 Hybrid Beverages Market