 Liquor Confectionery Market
: Size, Share & Forecast to 2033
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 191

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Liquor Confectionery Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 784.0 M |
| 2026 | 831.0 M |
| 2027 | 889.0 M |
| 2028 | 950.0 M |
| 2029 | 1.020 B |
| 2030 | 1.080 B |
| 2031 | 1.160 B |

The liquor confectionery market encompasses chocolate and sugar confections infused with or flavored by alcoholic beverages — including liqueurs, whisky, rum, brandy, and wine. Products span liquor-filled chocolates, truffles, gummies, and pralines, serving adult indulgence, gifting, and seasonal consumption occasions.
This report covers the global liquor confectionery market by product type (chocolates, candies and gums), distribution channel (supermarkets/hypermarkets, specialty stores, online), and region. It includes value-chain analysis, competitive benchmarking, and regulatory assessment. This analysis does not cover non-alcoholic confectionery with artificial spirit flavoring, standalone alcoholic beverages, or confectionery ingredients sold to food manufacturers for further processing.
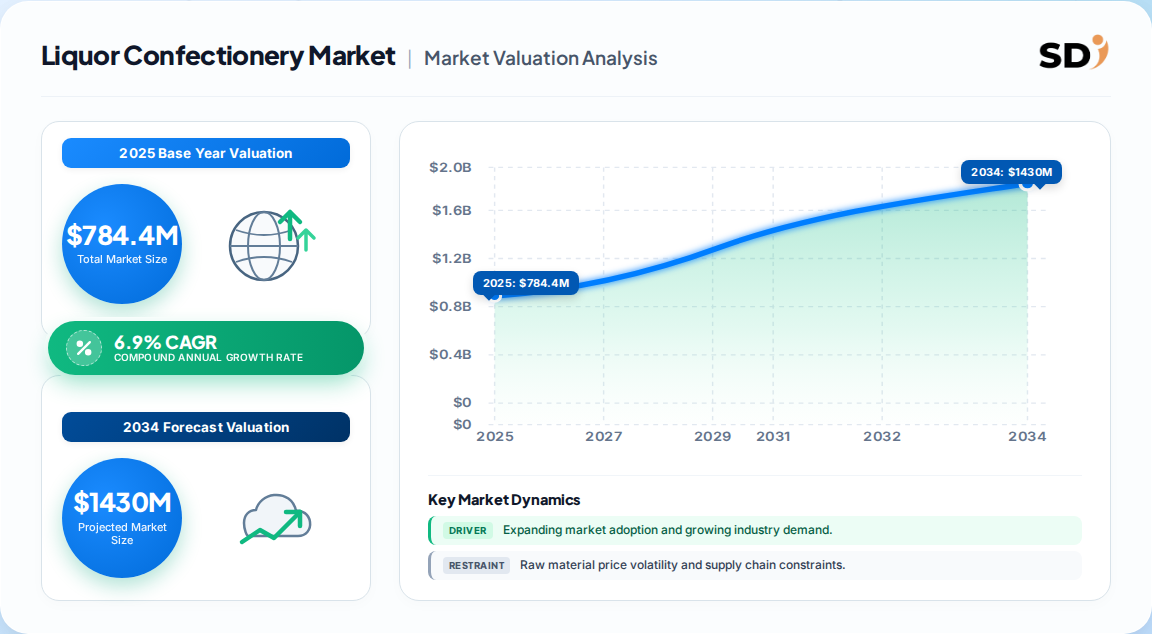
The global liquor confectionery market was valued at 784.4 Million in 2025, with forecasts diverging across published estimates due to differences in scope, base year, and segmentation depth.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 784.4 Million | 2025 | 2033 (1,322.7M) | 6.9% | Chocolates, candies & gums; retail distribution | One published estimate |
| 1.09 Billion | 2026 | 2031 (1.52B) | 6.88% | Bar, tablets, box assortment; alcohol base segmentation | A competing analysis |
| 750.3 Million | 2023 | 2032 (1.21B) | 5.5% | Broad confectionery including gummies and candies | Another published analysis |
| 699.9 Million | 2026 | 2036 (1,184.2M) | 5.4% | Chocolate-based, sugar-based, gummy; retail & gifting | Alternative research estimate |
| 790.77 Million | 2025 | 2033 (1,056.67M) | 5.10% | Chocolates, candies and gums; broad retail | A separate published estimate |
Our analysis suggests the 784.4 Million (2025) and 6.9% CAGR estimate is the most defensible, as it balances conservative base-year sizing with a realistic growth trajectory supported by premiumization and gifting tailwinds. Lower-CAGR estimates likely reflect broader product definitions that dilute the premium chocolate segment’s growth contribution.
The liquor confectionery market is segmented by product type, alcohol base, distribution channel, and form — with chocolates commanding the dominant share and specialty retail leading distribution.
| Parent Segment | Children |
|---|---|
| By Product Type | Chocolates, Candies & Gums |
| By Alcohol Base | Whisky/Bourbon, Rum, Liqueurs, Tequila/Mezcal, Wine/Champagne |
| By Distribution Channel | Supermarkets/Hypermarkets, Specialty Stores, Online Retail, Others |
| By Form | Solid Confectionery, Liquid Center Confectionery, Layered Confectionery |
Chocolates accounted for 70.4% of revenue in 2025, driven by liquor-filled pralines and truffles. Whisky/bourbon is the leading alcohol base at 38.12% share, while tequila/mezcal is the fastest-growing base at a 7.41% CAGR through 2031.
Europe leads the global liquor confectionery market, accounting for 48.2% of revenue in 2025, followed by North America and Asia Pacific. Europe’s dominance is anchored in countries such as the U.K., Germany, and Belgium, where liquor-filled chocolates are a established gifting tradition.
| Region | Market Share (%) |
|---|---|
| Europe | 0.47% |
| North America | 0.27% |
| Asia-Pacific | 0.17% |
| South America | 0.05% |
| Middle East & Africa | 0.04% |
| Parent Region | Children |
|---|---|
| Europe | Germany, UK, France, Belgium, Italy, Netherlands, Switzerland, Russia, Turkey |
| North America | USA, Canada, Mexico |
| Asia Pacific | China, Japan, India, South Korea, Singapore, Malaysia, Australia |
| South America | Brazil, Argentina, Rest of South America |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Egypt, Israel |
Asia Pacific is the fastest-growing region, with Japan leading country-level growth at 5.6% CAGR through 2036, supported by premium gifting culture and department-store distribution. North America is advancing at 8.24% CAGR, driven by craft-spirits culture and e-commerce expansion.
Growth is driven by premiumization, gifting culture, and flavor innovation, while stringent alcohol regulations and health concerns constrain market expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Premium & luxury confectionery preference | Driver | High (+1.8% CAGR impact) | Consumers pay EUR 50–80/kg for liquor-infused vs. EUR 25–35/kg for non-alcoholic premium |
| Gifting culture & luxury occasions | Driver | High (+1.2% CAGR impact) | Seasonal and corporate gifting spikes demand; Costco holiday assortments |
| Flavor innovation (tequila, mezcal, amaro) | Driver | Medium (+1.3% CAGR impact) | Cocktail culture inspires new SKUs; tequila/mezcal growing at 7.41% CAGR |
| Stringent labeling & age restrictions | Restraint | High | Compliance complexity; Karnataka FDA testing imported chocolates for undisclosed alcohol |
| Health consciousness (sugar/calorie concerns) | Restraint | Medium | Consumers demand sugar-free and low-calorie options |
The balance of evidence favors sustained premium-led growth, but regulatory fragmentation remains the single greatest execution risk. Manufacturers that invest in compliance infrastructure and transparent labeling will convert regulatory complexity into a competitive moat.
The liquor confectionery market is moderately concentrated, with Ferrero, Lindt & Sprüngli, Neuhaus, Anthon Berg, and Mars among the leading players, alongside specialist artisanal producers.
| Company | Headquarters | Key Strength |
|---|---|---|
| Ferrero Group | Italy | Global scale, premium chocolate portfolio, brand equity |
| Lindt & Sprüngli | Switzerland | Premium chocolate craftsmanship, liquor-filled truffle expertise |
| Neuhaus | Belgium | Belgian heritage, artisanal pralines, liquor-filled chocolates |
| Anthon Berg | Denmark | Iconic liquor-filled chocolate assortment, duty-free presence |
| Mars, Incorporated | USA | Mass-market distribution, brand portfolio breadth |
| Toms Gruppen | Denmark | Nordic confectionery leadership, liquor-filled chocolates |
| Chocolaterie Abtey | France | French artisanal tradition, premium liqueur chocolates |
Differentiation is rooted in spirit-brand licensing partnerships, artisanal craftsmanship, and provenance storytelling. Companies that combine premium chocolate manufacturing with recognized spirit brands command pricing power and shelf positioning that generic producers cannot replicate.
Buyers and operators must prioritize regulatory compliance, spirit-brand partnerships, and channel strategy when selecting liquor confectionery suppliers. Regulatory requirements vary materially across jurisdictions — some classify liquor confectionery as food regardless of alcohol content, while others impose age restrictions, labeling mandates, or alcohol limits. Procurement risk is elevated by unclear classification between food and alcoholic products, which can delay product rollouts. Switching costs are moderate, as artisanal production techniques and proprietary flavor formulations create differentiation. Operators should favor suppliers with demonstrated compliance infrastructure, transparent labeling practices, and established spirit-brand relationships. The expansion of e-commerce and duty-free channels offers margin-accretive growth, but requires investment in cold-chain and regulatory-ready packaging.
The balance of evidence favors premium-led growth with regulatory discipline as the critical differentiator. The market is transitioning from niche gifting to mainstream premium indulgence, with liquor confectionery commanding a 2x price premium over non-alcoholic premium assortments. However, the strongest counter-argument is that regulatory tightening could compress margins and slow innovation cycles, particularly for smaller artisanal producers lacking compliance resources.
Our analysis suggests three strategic imperatives for operators and investors:
The evidence that would change our conclusion is a sharp regulatory shock — such as a major jurisdiction reclassifying liquor confectionery as an alcoholic product — which would materially alter the addressable market and growth trajectory.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.9% from 2020-2034 |
| Segmentation |
|
The global liquor confectionery market was valued at 784.4 Million in 2025 and is projected to reach 1,322.7 Million by 2033, growing at a 6.9% CAGR from 2026 to 2033.
Europe dominates the market, accounting for 48.2% of global revenue in 2025, driven by strong confectionery heritage and premium consumption in countries like Germany, Belgium, and the U.K.
The market is segmented into chocolates, candies and gums. Chocolates dominate with a 70.4% revenue share in 2025, led by liquor-filled pralines, truffles, and molded chocolate formats.
Growth is driven by premiumization, rising gifting culture, and flavor innovation. Consumers increasingly seek artisanal, liquor-infused chocolates as luxury gifts, with whisky/bourbon and tequila/mezcal leading alcohol-base demand.
Key players include Ferrero Group, Lindt & Sprüngli, Neuhaus, Anthon Berg, Mars, Toms Gruppen, and Chocolaterie Abtey. Differentiation is rooted in spirit-brand partnerships and artisanal craftsmanship.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary methodology. In-depth interviews were conducted with stakeholders across the value chain: cocoa and spirit suppliers, specialized liquor confectionery producers, contract formulators, and global distributors. Decision-maker roles interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring granular insights into procurement, formulation, and channel dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Heads of R&D & Product Innovation | 35% |
| Procurement & Sourcing Directors | 30% |
| Regulatory & Compliance Leads | 20% |
| Commercial & Channel Operations | 15% |
| Company Type | Representation (%) |
|---|---|
| Liquor Confectionery Producers | 40% |
| Spirit Brand Licensing Partners | 25% |
| Specialty Retail & Distributors | 20% |
| Raw Material & Cocoa Suppliers | 15% |
We cross-validate findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized industry associations. These sources provide a robust foundation for trade-flow analysis, capacity mapping, and regulatory assessment.
Our sizing framework triangulates top-down macroeconomic and industry segment allocation with bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. This dual approach ensures market estimates reflect both macro demand drivers and micro-level supply constraints.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |