 Soft Drinks Market
: $740.6B in 2026 to $990.8B by 2032
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 269

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Soft Drinks Market
Sakshi Gurunule
Research Associate

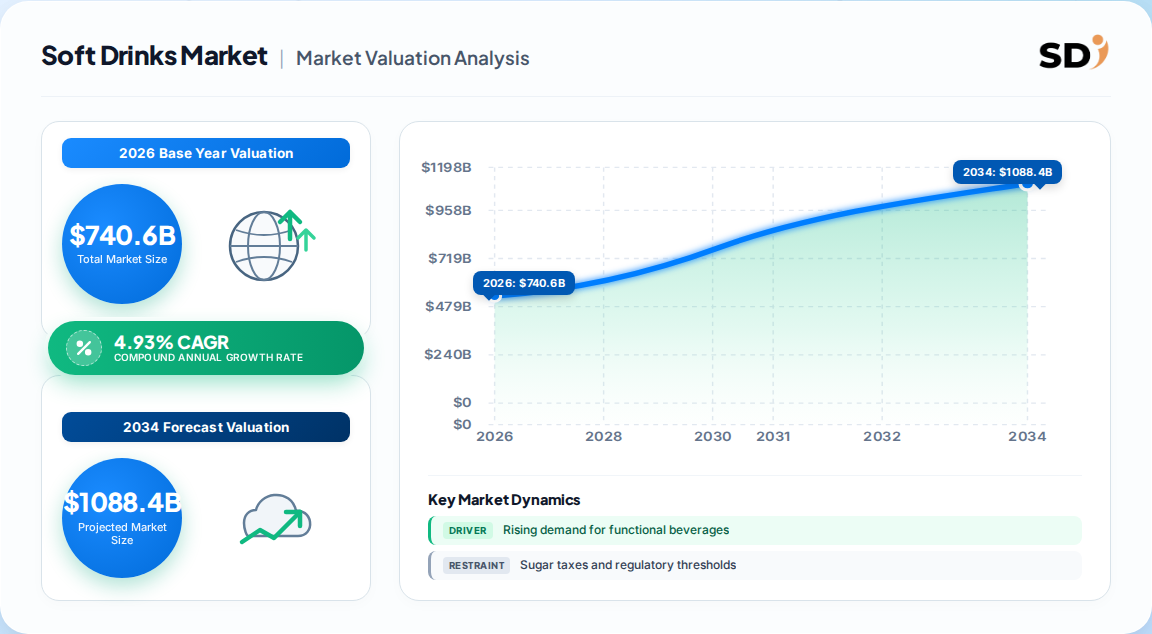
| Year | Market Size |
|---|---|
| 2026 | 740.6 B |
| 2027 | 777.1 B |
| 2028 | 815.4 B |
| 2029 | 855.6 B |
| 2030 | 897.9 B |
| 2031 | 942.2 B |
| 2032 | 990.8 B |

The soft drinks market covers prepared, water-based, non-alcoholic beverages with added flavoring, sweeteners, or aromas. It spans carbonated soft drinks, juices and nectars, functional and flavored waters, and energy drinks sold through at-home and out-of-home channels worldwide.
This analysis covers the global soft drinks market by category, packaging type, distribution channel, and region, with 2021–2032 historical and forecast framing. This analysis does not cover bottled water, hot drinks, powdered drink mixes and syrups, ready-to-drink coffee and tea, or stand-alone sports drinks where tracked separately.
Our lead estimate is USD 740.6 billion for 2026, but definitions differ sharply across published benchmarks, so buyers must reconcile scope before committing capital. The table below compares the main competing estimates and their underlying scope.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 740.6 billion | 2026 | 2032 | 4.93% | Total soft drinks, value, at- and out-of-home | One published estimate |
| USD 727.36 billion (combined) | 2026 | 2031 | 4.12% (at-home) | At-home plus out-of-home, excludes energy and sports drinks | Another published benchmark |
| USD 653.4 billion | 2025 | 2034 | 3.54% | Broad soft drinks incl. juices and functional | A competing analysis |
| USD 416.19 billion | 2021 | 2028 | 5.2% | Carbonated and non-carbonated, mature-market weighted | A third-party analysis |
The USD 740.6 billion figure is the most defensible for strategic planning because it is explicit on both value and volume for a single base year. The USD 727.36 billion benchmark is close but explicitly excludes energy drinks, which explains most of the gap. The lower USD 653.4 billion and USD 416.19 billion figures appear to use narrower category boundaries or older base years, so they should not be used interchangeably.
Segmentation matters more than totals: the fastest value pools sit in functional and zero-sugar formats rather than mainstream carbonates. The non-geographic structure below is the practical lens for portfolio and procurement decisions.
| Parent | Children | 2026 share / growth signal |
|---|---|---|
| By Category | Carbonated soft drinks; Juices; Energy drinks; Functional and enhanced drinks; Flavored and value-added water | Carbonates 45.27% share; energy fastest at 6.4% CAGR |
| By Packaging | PET bottles; Metal cans; Glass bottles; Other formats | PET 59.13% share; glass fastest at 5.5% CAGR |
| By Distribution Channel | Off-trade; On-trade | Off-trade 64.85% of value; on-trade fastest at 5.75% CAGR |
Our analysis suggests the category mix is shifting faster than the headline CAGR implies. Carbonates still carry the base, but the incremental growth dollars are concentrating in energy and functional drink occasions, which demand different formulation, packaging, and cold-chain economics.
North America leads the global soft drinks market with 34.24% of 2026 value, but Asia-Pacific is the growth engine at a forecast 6.1% CAGR through 2032. The geography tree below shows the working structure used in this report.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.22% |
| Asia Pacific | 0.28% |
| Latin America | 0.09% |
| Middle East & Africa | 0.07% |
The regional split is not just about size: it is about risk. North America carries the most mature regulatory and reformulation pressure, while Asia-Pacific offers volume runway but more fragmented distribution and pricing. That divergence argues against a single global pricing and packaging architecture.
Functional demand and sugar-reduction technology are the two strongest growth drivers, while sugar taxes and resource constraints are the most material brakes. The table assesses direction, evidence strength, and the transmission mechanism for each factor.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Functional beverage demand | Driver | Strong | Adds consumption occasions beyond refreshment |
| Sugar reduction and natural sweeteners | Driver | Strong | Enables volume growth within existing brands |
| Digital marketing and connected packaging | Driver | Moderate | Drives repeat purchase and direct ordering |
| Convenience and mini-can formats | Driver | Moderate | Matches immediate-consumption occasions |
| Sugar taxes and regulatory thresholds | Restraint | Strong | Raises cost of unchanged formulations |
| Clean-label and ingredient scrutiny | Restraint | Moderate | Forces reformulation and recipe complexity |
| Water scarcity and capture limits | Restraint | Moderate | Constrains bottling supply in exposed regions |
| Counterfeit beverages | Restraint | Weak | Erodes brand trust in specific markets |
The balance favors continued growth, but the composition changes. Sugar taxes are no longer a tail risk: 12 EU countries already tax soft drinks, and the UK plans to lower its levy threshold from 5g to 4.5g per 100ml from January 2028. Reformulation is therefore a cost of entry, not a differentiator.
The global soft drinks market is medium-concentration, anchored by five groups with distinct moats across brand, distribution, and functional niches. The comparison below focuses on strategic position rather than financial disclosure, which varies by entity.
| Company | Primary strength | Structural moat | Strategic watch |
|---|---|---|---|
| The Coca-Cola Company | Carbonates and zero-sugar franchise | Global bottler network and brand equity | Reformulation pace under tax thresholds |
| PepsiCo Inc. | Carbonates, snacks adjacency, functional hydration | Channel breadth and food pairing | Functional and enhanced-water scaling |
| Red Bull GmbH | Energy drinks | Category ownership and pricing power | Exposure to energy-tax discrimination |
| Keurig Dr Pepper Inc. | Flavored and non-carbonated portfolio | Distribution reach and brand portfolio | Portfolio shift toward health formats |
| Suntory Holdings Ltd. | Broad beverage and Asian footprint | Regional depth and premium assets | Asia-Pacific growth capture |
Differentiation increasingly comes from reformulation capability and channel execution rather than brand alone. Coca-Cola's 16% year-over-year growth in Coca-Cola Zero Sugar unit-case volume in the quarter ended July 3, 2026, illustrates how an existing franchise can absorb health-driven demand without losing shelf position.
Procurement and operator decisions hinge on regulatory exposure, formulation flexibility, and channel fit. Sugar-tax thresholds differ by jurisdiction, and the GCC's January 2026 volumetric tax reform left energy drinks outside the tiered structure, creating asymmetric cost burdens across categories. Buyers should model tax-adjusted landed cost per liter rather than per unit case.
Packaging choice is a second decision axis. PET dominates at 59.13% share, but glass is growing fastest at 5.5% CAGR, reflecting premium and on-trade positioning. Switching between formats changes filling lines, logistics, and sustainability reporting, so multi-year supply contracts should specify format flexibility. On-trade growth at 5.75% CAGR also raises the value of cold-chain and foodservice partnerships.
Compliance risk is uneven. EU-level analysis shows taxes on sugary drinks can reduce consumption and shift demand toward healthier products, so reformulation timing directly affects volume planning. Operators should secure natural-sweetener supply and validate label claims before tax thresholds bite, not after.
The balance of evidence favors a growth story concentrated in reformulation and functional formats, not in volume expansion of mainstream carbonates. The 4.93% CAGR is credible, but it masks a 2.9% volume CAGR: value growth is being carried by premiumization, smaller packs, and functional positioning. The strongest counter-argument is that volume growth is decelerating in mature markets and could undershoot, particularly if sugar taxes tighten faster than reformulation cycles.
Our analysis suggests the highest-return moves sit in portfolio reallocation toward energy, functional, and zero-sugar lines, matched to on-trade and convenience channels. Vendors that treat tax thresholds as a re-formulation deadline rather than a strategic cue will face margin compression and shelf losses. Asia-Pacific remains the clearest volume opportunity, but fragmented distribution raises execution risk.
The conclusion would change if two signals appeared: sustained volume declines in North America beyond cyclical softness, or a rapid EU-wide harmonization of soft drink taxes that compresses pricing power faster than reformulation can offset.
Our research applies a 70/30 primary-to-secondary split, anchored in in-depth interviews across the soft drinks value chain. We conducted structured interviews with raw material and ingredient suppliers, specialized beverage producers, contract formulators and co-packers, global distributors, and retail and foodservice channel operators. Decision-maker designations interviewed include VP-level sourcing and procurement leads, heads of R&D and formulation, technical directors, and commercial operations leads. Interviews were fielded across North America, Europe, and Asia-Pacific to capture regulatory and channel divergence.
Secondary validation draws on official multilateral trade and standards databases, including UN Comtrade, WTO SPS and TBT notifications, Eurostat, and US ITC data. Corporate disclosures including annual reports, 10-K filings, and investor presentations were used to verify capacity, volumes, and reformulation commitments. Patent databases and recognized non-profit technical and industry associations were reviewed to corroborate functional-ingredient and packaging innovation trends.
We triangulate simultaneously from the top down, allocating macroeconomic and industry segment output to soft drink categories, and from the bottom up, modeling manufacturer capacity, product pricing, and end-use consumption. Reconciliation across both directions reduces single-source bias and anchors the base-year valuation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis, and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, and commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.93% from 2020-2034 |
| Segmentation |
|
The soft drinks market is valued at approximately USD 740.6 billion in 2026, with volume of about 427.6 billion liters. Published estimates vary by scope, so buyers should confirm whether energy drinks and out-of-home sales are included.
The market is forecast to grow at a 4.93% CAGR in value from 2027 to 2032, reaching USD 990.8 billion. Volume growth is slower at about 2.9%, indicating value is being driven by premiumization and functional formats.
North America leads with 34.24% of 2026 value share, supported by mature branding and distribution. Asia-Pacific is the fastest-growing region at a forecast 6.1% CAGR, driven by urbanization and youth demographics.
Energy drinks are forecast to grow fastest at a 6.4% CAGR, followed by functional and enhanced beverages. Glass bottles are the fastest-growing packaging format at 5.5% CAGR, and on-trade is the fastest-growing channel at 5.75%.
The Coca-Cola Company, PepsiCo Inc., Red Bull GmbH, Keurig Dr Pepper Inc., and Suntory Holdings Ltd. are the major players. Competition centers on reformulation capability, bottler networks, and functional portfolio breadth.
Sugar taxes raise the cost of unchanged formulations and push manufacturers toward reformulation. Twelve EU countries already tax soft drinks, and the UK plans to lower its levy threshold to 4.5g per 100ml from January 2028.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split, anchored in in-depth interviews across the soft drinks value chain. We conducted structured interviews with raw material and ingredient suppliers, specialized beverage producers, contract formulators and co-packers, global distributors, and retail and foodservice channel operators. Decision-maker designations interviewed include VP-level sourcing and procurement leads, heads of R&D and formulation, technical directors, and commercial operations leads. Interviews were fielded across North America, Europe, and Asia-Pacific to capture regulatory and channel divergence.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Ingredient Suppliers | 40% |
| Specialized Beverage Producers | 30% |
| Contract Formulators & Co-Packers | 20% |
| Global Distributors & Channel Operators | 10% |
Secondary validation draws on official multilateral trade and standards databases, including UN Comtrade, WTO SPS and TBT notifications, Eurostat, and US ITC data. Corporate disclosures including annual reports, 10-K filings, and investor presentations were used to verify capacity, volumes, and reformulation commitments. Patent databases and recognized non-profit technical and industry associations were reviewed to corroborate functional-ingredient and packaging innovation trends.
We triangulate simultaneously from the top down, allocating macroeconomic and industry segment output to soft drink categories, and from the bottom up, modeling manufacturer capacity, product pricing, and end-use consumption. Reconciliation across both directions reduces single-source bias and anchors the base-year valuation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis, and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, and commercial filings | High |