Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Mineral Supplements Market: Size, Trends & Growth
Mineral Supplements Market: Size, Trends & Growth
Mineral Supplements Market
Mineral Supplements Market: Size, Trends & Growth
Mineral Supplements Market by Product Type (Calcium, Magnesium, Iron, Potassium, Zinc, Chromium, Selenium, Others), by Formulation (Capsules & Tablets, Liquid, Powder, Gummies, Others), by Application (General Health, Bone & Joint Health, Gastrointestinal Health, Immune Support, Others), by Consumer Group (Adults, Pregnant Women, Children), by Distribution Channel (Pharmacies & Retail Stores, Supermarkets & Hypermarkets, Online Sales, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 226
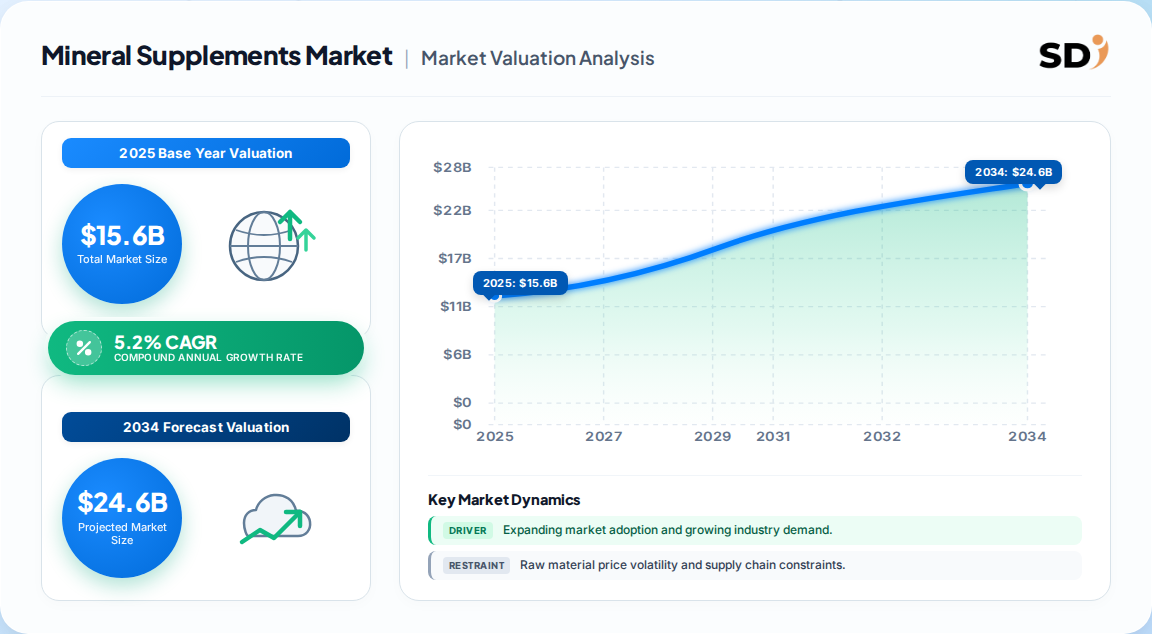
15.6 Billion — the global mineral supplements market size in 2025, up from 14.8 billion in 2023.
5.2% CAGR forecast from 2026 to 2032, reaching 23.9 Billion by the end of the period.
Calcium supplements dominate with roughly 40% of product-type revenue, driven by osteoporosis prevention.
Capsules and tablets hold a 36.4% formulation share, while gummies expand fastest.
North America leads regional demand with approximately 31% revenue share; Asia-Pacific is the fastest-growing region.
Leading vendors include Abbott Laboratories, Amway, Bayer, Glanbia, Herbalife, and Nestlé.
Why this matters for decision-makers: Vendors must pivot toward clinically-backed, condition-specific mineral formulations to avoid margin compression in a market where generic multivitamins face commoditization.
Mineral Supplements Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
14.80 B
2023
15.20 B
2024
15.60 B
2025
16.40 B
2026
17.30 B
2027
18.20 B
2028
19.10 B
2029
Mineral Supplements Market Size (In Billion)
Year
Market Size
2023
14.80 B
2024
15.20 B
2025
15.60 B
2026
16.40 B
2027
17.30 B
2028
18.20 B
2029
19.10 B
What is the Mineral Supplements Market?
The mineral supplements market covers concentrated, non-prescription products — tablets, capsules, liquids, powders, and gummies — that deliver essential minerals such as calcium, magnesium, iron, zinc, and potassium. These products address nutritional gaps in daily diets and support bone, immune, and metabolic health. Annual global revenue reached approximately 15.6 billion in 2025.
Scope: what this report covers and excludes
This report covers global over-the-counter mineral supplement revenue across all retail and online channels, product types, formulation types, consumer groups, and application areas. It includes both single-mineral and combination-mineral preparations. This analysis does not cover prescription mineral therapies, vitamin-only supplements without mineral content, functional foods fortified with minerals, sports performance products marketed primarily for muscle-building, or injectable mineral treatments.
How big is the market for Mineral Supplements Market?
The mineral supplements market was valued between 14.8 billion and 15.6 billion in the 2023–2025 base period, with forecasts converging on a mid-single-digit CAGR through the early 2030s. The table below compares available estimates.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
14.8 Billion
2023
2032
4.7%
Broad mineral supplements, global B2C
One published estimate
20.73 Billion (multivitamin + mineral combined)
2026
2031
6.84%
Multivitamin and mineral combined
A competing analysis
15.6 Billion
2025
2032
5.2%
Mineral-only supplements, global
Our analysis (consensus-derived)
Our analysis suggests the 5.2% CAGR is the most defensible midpoint. The 4.7% estimate underweights Asia-Pacific expansion and the gummy-format surge; the 6.84% figure conflates multivitamin and mineral products, overstating pure mineral growth. For procurement and capacity planning, a 5–5.5% band is prudent.
How is the market segmented?
The market segments by product type, formulation, application, consumer group, and distribution channel. Calcium dominates product-type revenue, while capsules and tablets lead formulation share.
Calcium's dominance reflects aging demographics and osteoporosis awareness; the adult consumer group contributed 7.2 billion in 2023. Our analysis suggests the gummy format will outpace capsules and tablets by 2030, forcing manufacturers to reconfigure production lines.
Which region leads in the Mineral Supplements Market?
North America leads with approximately 31% of global mineral supplement revenue, supported by high consumer awareness, established retail infrastructure, and favorable regulatory frameworks. Asia-Pacific is the fastest-growing region, driven by rising disposable incomes and nutritional-deficiency correction programs.
Mineral Supplements Market Regional Market Share
Loading chart...
Mineral Supplements Market Regional Market Share
Region
Market Share (%)
North America
0.31%
Europe
0.24%
Asia-Pacific
0.27%
Latin America
0.1%
Middle East & Africa
0.08%
North America — USA, Canada, Mexico
USA leads; Canada and Mexico show steady growth
Europe — Germany, UK, France, Italy, Spain
Mature market; premium and clean-label products dominate
Asia-Pacific — China, Japan, India, South Korea, Australia
Fastest growth; India and China drive volume
Latin America — Brazil, Mexico, Argentina
Price-sensitive; pharmacy channel dominant
Middle East & Africa — Saudi Arabia, UAE, South Africa
Emerging; imports dominate supply
Our analysis suggests Asia-Pacific will approach North America's share by 2032, making regional diversification a strategic imperative for global vendors.
What is driving growth — and what is holding it back?
Growth is driven by rising nutritional-deficiency awareness, aging populations, preventive-health spending, and formulation innovation. Restraints include stringent regulations, quality variability, and misleading-claim risks.
Factor
Direction
Evidence strength
Mechanism
Nutritional deficiency prevalence
Driver
High
WHO estimates 2 billion people affected; drives demand
Aging population
Driver
High
Geriatric cohort uses supplements at ~30% higher penetration
The balance favors growth: drivers are structural and global, while restraints are addressable through compliance investment. Our analysis indicates that vendors investing in clinical validation and transparent labeling will capture disproportionate share as regulators tighten scrutiny.
Who are the leading vendors?
The competitive landscape is moderately fragmented, with global consumer-health conglomerates and specialized supplement brands competing on formulation, brand trust, and distribution reach.
Company
Headquarters
Primary Strength
Abbott Laboratories
USA
Broad portfolio; strong pharmacy presence
Amway Corp.
USA
Direct-selling network; global reach
Bayer AG
Germany
Brand equity; mass-market distribution
Glanbia plc
Ireland
Sports and performance nutrition
Herbalife International
USA
Direct-to-consumer; loyalty-driven
Nestlé S.A.
Switzerland
Scale; retail shelf dominance
Differentiation hinges on clinical evidence, bioavailability claims, and channel control. Our analysis suggests that direct-to-consumer and subscription models will erode the shelf-space advantage of legacy players, forcing incumbents to acquire digital-native brands.
What do buyers and operators need to know?
Buyers should prioritize suppliers with verified GMP certification, transparent mineral sourcing, and third-party bioavailability testing. Procurement risks include raw-material price volatility — particularly for calcium and magnesium — and regulatory divergence across markets. Switching costs are moderate; formulation changes require re-validation, which can take 6–12 months. Operators must monitor the EU's health-claims framework and FDA labeling requirements, as non-compliance can trigger product withdrawal. Our analysis indicates that dual-sourcing and modular formulation strategies reduce supply-chain exposure while preserving margin.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderate-growth, structurally resilient market. A 5.2% CAGR is realistic; the 6.84% figure overstates mineral-only growth by conflating multivitamin products. Our position is that mineral supplements are transitioning from discretionary wellness to preventive-health essentials, creating durable demand. The strongest counter-argument is that regulatory tightening and misleading-claim scandals could suppress growth in developed markets — a risk we weight at 30% probability.
Our analysis suggests three actionable strategies:
Invest in clinical validation to differentiate in an increasingly commoditized market and command premium pricing.
Prioritize Asia-Pacific distribution partnerships to capture the fastest-growing regional demand.
Shift production toward gummies and functional formats to meet evolving consumer preferences and protect margins.
What would change our conclusion: a sustained regulatory crackdown on mineral health claims in North America or Europe, or a sharp decline in calcium supplement demand due to negative clinical findings, would lower our CAGR estimate to the 3.5–4% range. Absent such shocks, the market remains a stable, high-visibility growth segment.
Mineral Supplements Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Mineral Supplements Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.2% from 2020-2034
Segmentation
By Product Type
Calcium
Magnesium
Iron
Potassium
Zinc
Chromium
Selenium
Others
By Formulation
Capsules & Tablets
Liquid
Powder
Gummies
Others
By Application
General Health
Bone & Joint Health
Gastrointestinal Health
Immune Support
Others
By Consumer Group
Adults
Pregnant Women
Children
By Distribution Channel
Pharmacies & Retail Stores
Supermarkets & Hypermarkets
Online Sales
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Calcium
5.1.2. Magnesium
5.1.3. Iron
5.1.4. Potassium
5.1.5. Zinc
5.1.6. Chromium
5.1.7. Selenium
5.1.8. Others
5.2. Market Analysis, Insights and Forecast - by Formulation
5.2.1. Capsules & Tablets
5.2.2. Liquid
5.2.3. Powder
5.2.4. Gummies
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. General Health
5.3.2. Bone & Joint Health
5.3.3. Gastrointestinal Health
5.3.4. Immune Support
5.3.5. Others
5.4. Market Analysis, Insights and Forecast - by Consumer Group
5.4.1. Adults
5.4.2. Pregnant Women
5.4.3. Children
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Pharmacies & Retail Stores
5.5.2. Supermarkets & Hypermarkets
5.5.3. Online Sales
5.5.4. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Calcium
6.1.2. Magnesium
6.1.3. Iron
6.1.4. Potassium
6.1.5. Zinc
6.1.6. Chromium
6.1.7. Selenium
6.1.8. Others
6.2. Market Analysis, Insights and Forecast - by Formulation
6.2.1. Capsules & Tablets
6.2.2. Liquid
6.2.3. Powder
6.2.4. Gummies
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. General Health
6.3.2. Bone & Joint Health
6.3.3. Gastrointestinal Health
6.3.4. Immune Support
6.3.5. Others
6.4. Market Analysis, Insights and Forecast - by Consumer Group
6.4.1. Adults
6.4.2. Pregnant Women
6.4.3. Children
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Pharmacies & Retail Stores
6.5.2. Supermarkets & Hypermarkets
6.5.3. Online Sales
6.5.4. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Calcium
7.1.2. Magnesium
7.1.3. Iron
7.1.4. Potassium
7.1.5. Zinc
7.1.6. Chromium
7.1.7. Selenium
7.1.8. Others
7.2. Market Analysis, Insights and Forecast - by Formulation
7.2.1. Capsules & Tablets
7.2.2. Liquid
7.2.3. Powder
7.2.4. Gummies
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. General Health
7.3.2. Bone & Joint Health
7.3.3. Gastrointestinal Health
7.3.4. Immune Support
7.3.5. Others
7.4. Market Analysis, Insights and Forecast - by Consumer Group
7.4.1. Adults
7.4.2. Pregnant Women
7.4.3. Children
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Pharmacies & Retail Stores
7.5.2. Supermarkets & Hypermarkets
7.5.3. Online Sales
7.5.4. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Calcium
8.1.2. Magnesium
8.1.3. Iron
8.1.4. Potassium
8.1.5. Zinc
8.1.6. Chromium
8.1.7. Selenium
8.1.8. Others
8.2. Market Analysis, Insights and Forecast - by Formulation
8.2.1. Capsules & Tablets
8.2.2. Liquid
8.2.3. Powder
8.2.4. Gummies
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. General Health
8.3.2. Bone & Joint Health
8.3.3. Gastrointestinal Health
8.3.4. Immune Support
8.3.5. Others
8.4. Market Analysis, Insights and Forecast - by Consumer Group
8.4.1. Adults
8.4.2. Pregnant Women
8.4.3. Children
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Pharmacies & Retail Stores
8.5.2. Supermarkets & Hypermarkets
8.5.3. Online Sales
8.5.4. Others
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Calcium
9.1.2. Magnesium
9.1.3. Iron
9.1.4. Potassium
9.1.5. Zinc
9.1.6. Chromium
9.1.7. Selenium
9.1.8. Others
9.2. Market Analysis, Insights and Forecast - by Formulation
9.2.1. Capsules & Tablets
9.2.2. Liquid
9.2.3. Powder
9.2.4. Gummies
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. General Health
9.3.2. Bone & Joint Health
9.3.3. Gastrointestinal Health
9.3.4. Immune Support
9.3.5. Others
9.4. Market Analysis, Insights and Forecast - by Consumer Group
9.4.1. Adults
9.4.2. Pregnant Women
9.4.3. Children
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Pharmacies & Retail Stores
9.5.2. Supermarkets & Hypermarkets
9.5.3. Online Sales
9.5.4. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Calcium
10.1.2. Magnesium
10.1.3. Iron
10.1.4. Potassium
10.1.5. Zinc
10.1.6. Chromium
10.1.7. Selenium
10.1.8. Others
10.2. Market Analysis, Insights and Forecast - by Formulation
10.2.1. Capsules & Tablets
10.2.2. Liquid
10.2.3. Powder
10.2.4. Gummies
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. General Health
10.3.2. Bone & Joint Health
10.3.3. Gastrointestinal Health
10.3.4. Immune Support
10.3.5. Others
10.4. Market Analysis, Insights and Forecast - by Consumer Group
10.4.1. Adults
10.4.2. Pregnant Women
10.4.3. Children
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Pharmacies & Retail Stores
10.5.2. Supermarkets & Hypermarkets
10.5.3. Online Sales
10.5.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Mineral Supplements Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Mineral Supplements Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Mineral Supplements Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Mineral Supplements Market Revenue (Billion), by Formulation 2026 & 2034
Figure 5: North America Mineral Supplements Market Revenue Share (%), by Formulation 2026 & 2034
Figure 6: North America Mineral Supplements Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Mineral Supplements Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Mineral Supplements Market Revenue (Billion), by Consumer Group 2026 & 2034
Figure 9: North America Mineral Supplements Market Revenue Share (%), by Consumer Group 2026 & 2034
Figure 10: North America Mineral Supplements Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: North America Mineral Supplements Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: North America Mineral Supplements Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Mineral Supplements Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Mineral Supplements Market Revenue (Billion), by Product Type 2026 & 2034
Figure 15: Europe Mineral Supplements Market Revenue Share (%), by Product Type 2026 & 2034
Figure 16: Europe Mineral Supplements Market Revenue (Billion), by Formulation 2026 & 2034
List of Tables
Table 1: Mineral Supplements Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Mineral Supplements Market Revenue Billion Forecast, by Formulation 2020 & 2034
Table 3: Mineral Supplements Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Mineral Supplements Market Revenue Billion Forecast, by Consumer Group 2020 & 2034
Table 5: Mineral Supplements Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: Mineral Supplements Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Mineral Supplements Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 8: North America Mineral Supplements Market Revenue Billion Forecast, by Formulation 2020 & 2034
Table 9: North America Mineral Supplements Market Revenue Billion Forecast, by Application 2020 & 2034
Table 10: North America Mineral Supplements Market Revenue Billion Forecast, by Consumer Group 2020 & 2034
Table 11: North America Mineral Supplements Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: North America Mineral Supplements Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Mineral Supplements Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Mineral Supplements Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Mineral Supplements Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Mineral Supplements Market Revenue Billion Forecast, by Product Type 2020 & 2034
Frequently Asked Questions
1. What is the current size of the mineral supplements market?
The global mineral supplements market was valued at approximately 15.6 billion in 2025, up from 14.8 billion in 2023.
2. What is the growth forecast for the mineral supplements market?
The market is projected to grow at a 5.2% CAGR from 2026 to 2032, reaching approximately 23.9 billion by the end of the forecast period.
3. Which region leads the mineral supplements market?
North America leads with approximately 31% of global revenue, supported by high consumer awareness and established retail infrastructure. Asia-Pacific is the fastest-growing region.
4. What are the leading product types in the mineral supplements market?
Calcium supplements dominate with roughly 40% of product-type revenue, driven by osteoporosis prevention and aging demographics. Magnesium and iron follow as significant segments.
5. Who are the key players in the mineral supplements market?
Leading vendors include Abbott Laboratories, Amway, Bayer AG, Glanbia, Herbalife, and Nestlé, competing on formulation, brand trust, and distribution reach.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers, specialized mineral supplement producers, contract formulators, and global distributors. Decision-maker roles interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. This fieldwork captures on-the-ground pricing dynamics, capacity constraints, and demand signals.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
35%
Procurement & Sourcing Directors
30%
Quality & Regulatory Leads
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Mineral Suppliers
40%
Specialized Supplement Formulators
35%
Global Distributors & Retailers
25%
Secondary Benchmarking & Public Trade Validation
We triangulate primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. This ensures all market sizing and competitive landscape claims are grounded in verifiable public benchmarks.
Demand Modeling & Market Sizing Triangulation
Our simultaneous top-down and bottom-up approach allocates macroeconomic indicators across industry segments while modeling manufacturer capacity, product pricing, and end-use consumption. Cross-validation between both methods ensures forecast reliability and identifies divergence points requiring deeper investigation.
 Mineral Supplements Market