Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
US Powder Dietary Supplements Market Size & Forecast 2026
Us Powder Dietary Supplements Market
US Powder Dietary Supplements Market Size & Forecast 2026
Us Powder Dietary Supplements Market by Product Type (Protein, Multivitamin & Mineral, Amino Acid, Meal Replacement, Probiotic & Prebiotic, Herbal & Botanical, Electrolyte & Hydration, Collagen & Beauty, Weight Management, Specialty Functional), by Ingredient (Animal-based, Plant-based, Synthetic/Isolated), by Functionality (Sports & Performance, General Wellness, Weight Management, Digestive Health, Immunity, Healthy Aging), by Consumer Group (Adults, Geriatric, Pediatric, Athletes), by End Use (Household, Clinical, Institutional), by Distribution Channel (Supermarkets/Hypermarkets, Pharmacies, Specialty Stores, Online/DTC), by North America (United States, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 262
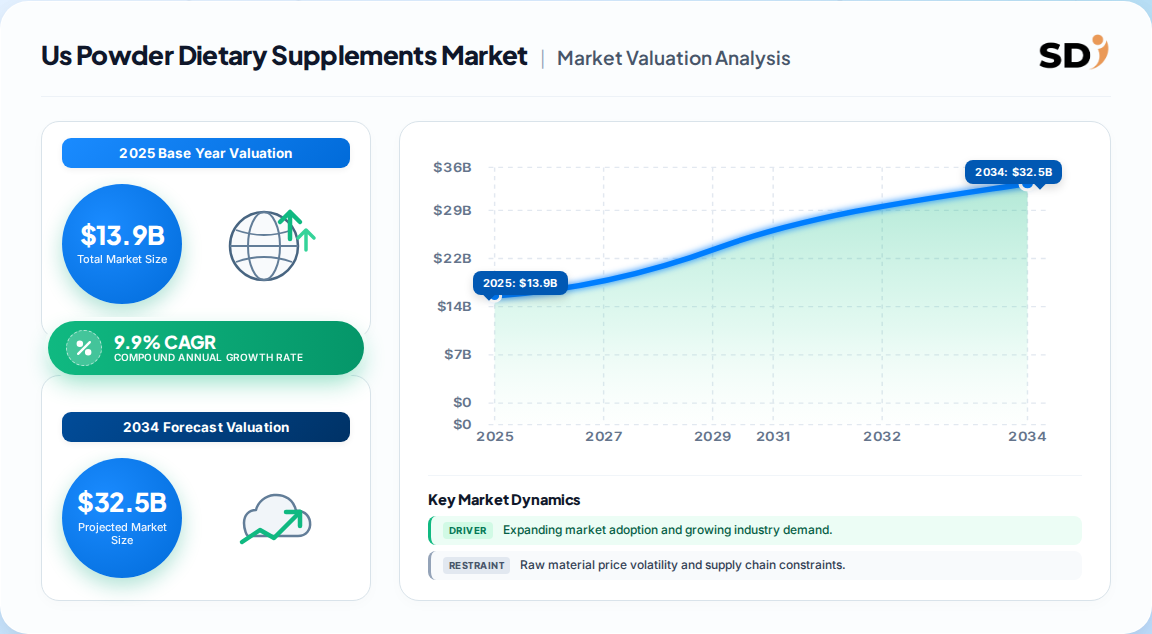
The US powder dietary supplements market was valued at approximately 13.9 Billion in 2025, representing 47.2% of the global powder supplements market, according to one published estimate.
Forecasts project the US segment to reach between 30.5 Billion (at 9.9% global CAGR) and 35.8 Billion (at 11.3% global CAGR) by 2034, depending on the growth scenario adopted.
Protein powders dominate product type with 31.8% share, while sports and performance nutrition leads functionality at 38.9%, reflecting the category's fitness-oriented consumer base.
Adults represent 56.6% of end users, and household consumption accounts for 61.4% of demand, indicating that everyday wellness rather than clinical or institutional use is the primary volume driver.
North America holds the largest regional share at 47.2%, but Asia Pacific is the fastest-growing region, creating a strategic tension for US-based brands weighing domestic saturation against export-led expansion.
Why this matters for decision-makers: Vendors must pivot toward personalized, condition-specific powder formulations (gut health, healthy aging, beauty-from-within) to avoid margin compression in the commoditized protein category, where private-label competition is eroding brand premiums.
Us Powder Dietary Supplements Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
12.60 B
2024
13.90 B
2025
15.30 B
2026
16.80 B
2027
18.50 B
2028
20.30 B
2029
22.30 B
2030
Us Powder Dietary Supplements Market Size (In Billion)
Year
Market Size
2024
12.60 B
2025
13.90 B
2026
15.30 B
2027
16.80 B
2028
18.50 B
2029
20.30 B
2030
22.30 B
What is the Us Powder Dietary Supplements Market?
The US powder dietary supplements market encompasses concentrated nutritional products in powder form—protein, multivitamin, amino acid, meal replacement, probiotic, herbal, electrolyte, collagen, and specialty functional powders—sold primarily for mixing into beverages or foods to support health, fitness, and wellness goals across adult and pediatric populations.
Scope: what this report covers and excludes
This report covers the US powder dietary supplements market across product types, ingredients, functionality, consumer groups, end uses, and distribution channels. It includes OTC and prescribed powder supplements sold through offline and online channels. This analysis does not cover capsule, tablet, gummy, or softgel supplement formats; functional foods and beverages; sports nutrition bars or ready-to-drink shakes; or medical foods regulated under separate FDA frameworks.
How big is the market for Us Powder Dietary Supplements Market?
The US powder dietary supplements market is estimated at 13.9 Billion in 2025, derived from the global powder supplements market of 29.6 Billion at a 47.2% North American share. Competing global estimates imply different US trajectories, as shown below.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
29.6 Billion (global powder supplements)
2024
2034
9.9%
Global, all powder supplement types
One published estimate
30.8 Billion (global powder supplements)
2025
2033
11.3%
Global, all powder supplement types
A competing analysis
13.9 Billion (US share)
2024
2034
9.9%
US, 47.2% of global
Derived from global estimate
Our analysis suggests the 9.9% CAGR is the more defensible figure for the US, because it aligns with the broader dietary supplements market growth of 6.85% and accounts for the maturity of the domestic market relative to Asia Pacific. The 11.3% CAGR likely reflects emerging-market growth that does not fully apply to the US. The divergence between the two global estimates—29.6 Billion versus 30.8 Billion for nearly the same period—implies definitional differences in what constitutes a "powder dietary supplement," particularly whether meal replacements and electrolyte powders are included.
How is the market segmented?
The US powder dietary supplements market is segmented by product type, ingredient source, functionality, consumer group, end use, and distribution channel, with protein powders and sports nutrition representing the largest revenue pools.
Protein powders lead at 31.8% because scoop-and-mix convenience, broad flavor variety, and strong gym and online placement keep trial and repeat high. Animal-based ingredients hold 47.2% on the strength of whey and casein familiarity, while plant-based blends are gaining share among health-conscious and lactose-intolerant consumers.
Which region leads in Us Powder Dietary Supplements Market?
North America leads the global powder dietary supplements market with 47.2% share, and within North America the United States is the dominant country market, accounting for the majority of regional revenue. The US market's leadership is reinforced by high supplement penetration (77% of adults report taking supplements), mature retail infrastructure, and a well-developed DTC e-commerce ecosystem.
Us Powder Dietary Supplements Market Regional Market Share
Loading chart...
Us Powder Dietary Supplements Market Regional Market Share
Region
Market Share (%)
North America
0.47%
Europe
0.22%
Asia-Pacific
0.19%
South America
0.06%
Middle East & Africa
0.06%
North America (47.2%)
United States (dominant)
Canada
Mexico
Europe (22.0%)
Germany
UK
France
Italy
Asia Pacific (19.0%)
China
Japan
India
South Korea
Latin America (6.0%)
Brazil
Argentina
Middle East & Africa (6.0%)
Saudi Arabia
UAE
South Africa
Our analysis suggests the US share is likely to erode modestly over the forecast period as Asia Pacific posts a higher CAGR. However, the US will remain the single largest country market through 2034 because per-capita supplement spending and brand concentration are significantly higher than in emerging regions.
What is driving growth — and what is holding it back?
Growth is driven by demand for convenient, customizable nutrition; rising health consciousness; an aging population; e-commerce expansion; and formulation innovation in probiotics, nootropics, and single-serve formats. Restraining factors include quality and transparency concerns, taste and texture failures, and regulatory ambiguity under DSHEA.
Factor
Direction
Evidence Strength
Mechanism
Convenient, customizable nutrition
Driver
High
Powders mix into beverages and allow serving-size adjustment; suits busy lifestyles
Rising health consciousness
Driver
High
77% of US adults take supplements; preventive health spending rising
Aging population
Driver
High
Adults 50+ are heavy supplement users for joint, cognitive, and cardiovascular support
E-commerce and DTC expansion
Driver
High
Online channels widen access and enable niche brand discovery
Poor solubility or aftertaste discourages repeat purchase
Regulatory ambiguity under DSHEA
Restraint
Medium
Pre-market safety burden is low; compliance risk varies by ingredient
The balance of evidence favors the drivers, but the restraints are not trivial. Transparency concerns are especially acute in protein and multi-ingredient formulations, where consumers increasingly seek third-party testing certification. Our analysis suggests that brands investing in clean-label certification and transparent sourcing will convert restraint into competitive advantage.
Who are the leading vendors?
The US powder dietary supplements market is fragmented, with established supplement majors, sports nutrition specialists, and DTC-native brands competing across price tiers and channels.
Company
Primary Category Focus
Channel Strength
Differentiation
Herbalife
Meal replacement, wellness
DTC/distributor network
Global distributor base; weight-management heritage
Amway (Nutrilite)
Multivitamin, wellness
DTC/distributor
Vertically integrated farming and traceability
GNC Holdings
Sports nutrition, general
Specialty retail, online
Retail brand recognition; private-label programs
Nature's Bounty
Vitamins, general wellness
Mass retail, pharmacy
Broad portfolio; mass-channel distribution
NOW Foods
Natural, general wellness
Health food stores, online
Value pricing; natural channel loyalty
Garden of Life
Plant-based, organic
Mass, online
Certified organic and non-GMO positioning
Optimum Nutrition
Protein, sports
Specialty, online
Whey protein category leadership; gym presence
USANA Health Sciences
Multivitamin, wellness
DTC
Science-backed positioning; high consumer trust
The competitive moat in this market is built on brand trust, third-party certifications, and channel relationships rather than proprietary formulations. Our analysis suggests DTC-native brands are eroding incumbents' share in the personalized and functional powder niches, where agility and direct consumer data provide an edge.
What do buyers and operators need to know?
Buyers and operators must prioritize ingredient traceability, third-party testing certification, and label-claim substantiation, because these are the leading sources of procurement risk and regulatory exposure in the US powder supplements market. Switching costs are moderate: contract formulators can be replaced, but reformulation triggers stability, taste, and compliance re-validation. Operators should also monitor DSHEA compliance and FTC advertising standards, which are increasingly enforced against structure-function claims. Channel strategy matters: offline still holds roughly 79.5% of global powder supplement sales, but online is growing faster, so a hybrid channel model is essential for reach and margin balance.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderate-growth, high-fragmentation outlook for the US powder dietary supplements market. The 9.9% CAGR scenario is more defensible than the 11.3% figure because it aligns with broader US supplement growth and accounts for domestic market maturity. The strongest counter-argument is that personalized nutrition and GLP-1-adjacent weight-management powders could accelerate growth beyond current forecasts, but this upside is contingent on clinical validation and regulatory clarity that do not yet exist.
Our analysis suggests three strategic imperatives. First, brands should shift portfolio weight toward condition-specific functional powders—gut health, healthy aging, and beauty-from-within—where margins are higher and private-label competition is thinner. Second, operators should invest in transparency infrastructure, including third-party testing and clear sourcing disclosure, to convert consumer skepticism into brand equity. Third, investors should monitor Asia Pacific growth as a leading indicator of global brand trajectories, because the region's higher CAGR will shape the next wave of category leadership.
The evidence that would change our conclusion is a sustained acceleration in US protein powder volume growth above 12% annualized, or a regulatory shift that clarifies and standardizes powder supplement labeling. Absent either, the moderate-growth, share-shift thesis holds.
Actionable Strategy:
Prioritize functional and condition-specific powder SKUs to capture premium margins and reduce exposure to commoditized protein.
Invest in third-party certification and transparent sourcing as a defensive moat against quality concerns and private-label encroachment.
Build a hybrid offline-online channel model, using DTC data to inform formulation and targeting while leveraging retail for trial and reach.
Us Powder Dietary Supplements Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Us Powder Dietary Supplements Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 9.9% from 2020-2034
Segmentation
By Product Type
Protein
Multivitamin & Mineral
Amino Acid
Meal Replacement
Probiotic & Prebiotic
Herbal & Botanical
Electrolyte & Hydration
Collagen & Beauty
Weight Management
Specialty Functional
By Ingredient
Animal-based
Plant-based
Synthetic/Isolated
By Functionality
Sports & Performance
General Wellness
Weight Management
Digestive Health
Immunity
Healthy Aging
By Consumer Group
Adults
Geriatric
Pediatric
Athletes
By End Use
Household
Clinical
Institutional
By Distribution Channel
Supermarkets/Hypermarkets
Pharmacies
Specialty Stores
Online/DTC
By Geography
North America
United States
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Protein
5.1.2. Multivitamin & Mineral
5.1.3. Amino Acid
5.1.4. Meal Replacement
5.1.5. Probiotic & Prebiotic
5.1.6. Herbal & Botanical
5.1.7. Electrolyte & Hydration
5.1.8. Collagen & Beauty
5.1.9. Weight Management
5.1.10. Specialty Functional
5.2. Market Analysis, Insights and Forecast - by Ingredient
5.2.1. Animal-based
5.2.2. Plant-based
5.2.3. Synthetic/Isolated
5.3. Market Analysis, Insights and Forecast - by Functionality
5.3.1. Sports & Performance
5.3.2. General Wellness
5.3.3. Weight Management
5.3.4. Digestive Health
5.3.5. Immunity
5.3.6. Healthy Aging
5.4. Market Analysis, Insights and Forecast - by Consumer Group
5.4.1. Adults
5.4.2. Geriatric
5.4.3. Pediatric
5.4.4. Athletes
5.5. Market Analysis, Insights and Forecast - by End Use
5.5.1. Household
5.5.2. Clinical
5.5.3. Institutional
5.6. Market Analysis, Insights and Forecast - by Distribution Channel
5.6.1. Supermarkets/Hypermarkets
5.6.2. Pharmacies
5.6.3. Specialty Stores
5.6.4. Online/DTC
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Protein
6.1.2. Multivitamin & Mineral
6.1.3. Amino Acid
6.1.4. Meal Replacement
6.1.5. Probiotic & Prebiotic
6.1.6. Herbal & Botanical
6.1.7. Electrolyte & Hydration
6.1.8. Collagen & Beauty
6.1.9. Weight Management
6.1.10. Specialty Functional
6.2. Market Analysis, Insights and Forecast - by Ingredient
6.2.1. Animal-based
6.2.2. Plant-based
6.2.3. Synthetic/Isolated
6.3. Market Analysis, Insights and Forecast - by Functionality
6.3.1. Sports & Performance
6.3.2. General Wellness
6.3.3. Weight Management
6.3.4. Digestive Health
6.3.5. Immunity
6.3.6. Healthy Aging
6.4. Market Analysis, Insights and Forecast - by Consumer Group
6.4.1. Adults
6.4.2. Geriatric
6.4.3. Pediatric
6.4.4. Athletes
6.5. Market Analysis, Insights and Forecast - by End Use
6.5.1. Household
6.5.2. Clinical
6.5.3. Institutional
6.6. Market Analysis, Insights and Forecast - by Distribution Channel
6.6.1. Supermarkets/Hypermarkets
6.6.2. Pharmacies
6.6.3. Specialty Stores
6.6.4. Online/DTC
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Protein
7.1.2. Multivitamin & Mineral
7.1.3. Amino Acid
7.1.4. Meal Replacement
7.1.5. Probiotic & Prebiotic
7.1.6. Herbal & Botanical
7.1.7. Electrolyte & Hydration
7.1.8. Collagen & Beauty
7.1.9. Weight Management
7.1.10. Specialty Functional
7.2. Market Analysis, Insights and Forecast - by Ingredient
7.2.1. Animal-based
7.2.2. Plant-based
7.2.3. Synthetic/Isolated
7.3. Market Analysis, Insights and Forecast - by Functionality
7.3.1. Sports & Performance
7.3.2. General Wellness
7.3.3. Weight Management
7.3.4. Digestive Health
7.3.5. Immunity
7.3.6. Healthy Aging
7.4. Market Analysis, Insights and Forecast - by Consumer Group
7.4.1. Adults
7.4.2. Geriatric
7.4.3. Pediatric
7.4.4. Athletes
7.5. Market Analysis, Insights and Forecast - by End Use
7.5.1. Household
7.5.2. Clinical
7.5.3. Institutional
7.6. Market Analysis, Insights and Forecast - by Distribution Channel
7.6.1. Supermarkets/Hypermarkets
7.6.2. Pharmacies
7.6.3. Specialty Stores
7.6.4. Online/DTC
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Protein
8.1.2. Multivitamin & Mineral
8.1.3. Amino Acid
8.1.4. Meal Replacement
8.1.5. Probiotic & Prebiotic
8.1.6. Herbal & Botanical
8.1.7. Electrolyte & Hydration
8.1.8. Collagen & Beauty
8.1.9. Weight Management
8.1.10. Specialty Functional
8.2. Market Analysis, Insights and Forecast - by Ingredient
8.2.1. Animal-based
8.2.2. Plant-based
8.2.3. Synthetic/Isolated
8.3. Market Analysis, Insights and Forecast - by Functionality
8.3.1. Sports & Performance
8.3.2. General Wellness
8.3.3. Weight Management
8.3.4. Digestive Health
8.3.5. Immunity
8.3.6. Healthy Aging
8.4. Market Analysis, Insights and Forecast - by Consumer Group
8.4.1. Adults
8.4.2. Geriatric
8.4.3. Pediatric
8.4.4. Athletes
8.5. Market Analysis, Insights and Forecast - by End Use
8.5.1. Household
8.5.2. Clinical
8.5.3. Institutional
8.6. Market Analysis, Insights and Forecast - by Distribution Channel
8.6.1. Supermarkets/Hypermarkets
8.6.2. Pharmacies
8.6.3. Specialty Stores
8.6.4. Online/DTC
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Protein
9.1.2. Multivitamin & Mineral
9.1.3. Amino Acid
9.1.4. Meal Replacement
9.1.5. Probiotic & Prebiotic
9.1.6. Herbal & Botanical
9.1.7. Electrolyte & Hydration
9.1.8. Collagen & Beauty
9.1.9. Weight Management
9.1.10. Specialty Functional
9.2. Market Analysis, Insights and Forecast - by Ingredient
9.2.1. Animal-based
9.2.2. Plant-based
9.2.3. Synthetic/Isolated
9.3. Market Analysis, Insights and Forecast - by Functionality
9.3.1. Sports & Performance
9.3.2. General Wellness
9.3.3. Weight Management
9.3.4. Digestive Health
9.3.5. Immunity
9.3.6. Healthy Aging
9.4. Market Analysis, Insights and Forecast - by Consumer Group
9.4.1. Adults
9.4.2. Geriatric
9.4.3. Pediatric
9.4.4. Athletes
9.5. Market Analysis, Insights and Forecast - by End Use
9.5.1. Household
9.5.2. Clinical
9.5.3. Institutional
9.6. Market Analysis, Insights and Forecast - by Distribution Channel
9.6.1. Supermarkets/Hypermarkets
9.6.2. Pharmacies
9.6.3. Specialty Stores
9.6.4. Online/DTC
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Protein
10.1.2. Multivitamin & Mineral
10.1.3. Amino Acid
10.1.4. Meal Replacement
10.1.5. Probiotic & Prebiotic
10.1.6. Herbal & Botanical
10.1.7. Electrolyte & Hydration
10.1.8. Collagen & Beauty
10.1.9. Weight Management
10.1.10. Specialty Functional
10.2. Market Analysis, Insights and Forecast - by Ingredient
10.2.1. Animal-based
10.2.2. Plant-based
10.2.3. Synthetic/Isolated
10.3. Market Analysis, Insights and Forecast - by Functionality
10.3.1. Sports & Performance
10.3.2. General Wellness
10.3.3. Weight Management
10.3.4. Digestive Health
10.3.5. Immunity
10.3.6. Healthy Aging
10.4. Market Analysis, Insights and Forecast - by Consumer Group
10.4.1. Adults
10.4.2. Geriatric
10.4.3. Pediatric
10.4.4. Athletes
10.5. Market Analysis, Insights and Forecast - by End Use
10.5.1. Household
10.5.2. Clinical
10.5.3. Institutional
10.6. Market Analysis, Insights and Forecast - by Distribution Channel
10.6.1. Supermarkets/Hypermarkets
10.6.2. Pharmacies
10.6.3. Specialty Stores
10.6.4. Online/DTC
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Us Powder Dietary Supplements Market Revenue Breakdown (Billion, %) by Product 2026 & 2034
Figure 2: Us Powder Dietary Supplements Market Value Share (%), by Product Type 2026 & 2034
Figure 3: Us Powder Dietary Supplements Market Value Share (%), by Ingredient 2026 & 2034
Figure 4: Us Powder Dietary Supplements Market Value Share (%), by Functionality 2026 & 2034
Figure 5: Us Powder Dietary Supplements Market Value Share (%), by Consumer Group 2026 & 2034
Figure 6: Us Powder Dietary Supplements Market Value Share (%), by End Use 2026 & 2034
Figure 7: Us Powder Dietary Supplements Market Value Share (%), by Distribution Channel 2026 & 2034
Figure 8: Us Powder Dietary Supplements Market Share (%) by Company 2026
List of Tables
Table 1: Us Powder Dietary Supplements Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Us Powder Dietary Supplements Market Revenue Billion Forecast, by Ingredient 2020 & 2034
Table 3: Us Powder Dietary Supplements Market Revenue Billion Forecast, by Functionality 2020 & 2034
Table 4: Us Powder Dietary Supplements Market Revenue Billion Forecast, by Consumer Group 2020 & 2034
Table 5: Us Powder Dietary Supplements Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 6: Us Powder Dietary Supplements Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 7: Us Powder Dietary Supplements Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Us Powder Dietary Supplements Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 9: North America Us Powder Dietary Supplements Market Revenue Billion Forecast, by Ingredient 2020 & 2034
Table 10: North America Us Powder Dietary Supplements Market Revenue Billion Forecast, by Functionality 2020 & 2034
Table 11: North America Us Powder Dietary Supplements Market Revenue Billion Forecast, by Consumer Group 2020 & 2034
Table 12: North America Us Powder Dietary Supplements Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 13: North America Us Powder Dietary Supplements Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 14: North America Us Powder Dietary Supplements Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: United States Us Powder Dietary Supplements Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the US powder dietary supplements market?
The US powder dietary supplements market was valued at approximately 13.9 Billion in 2025, representing 47.2% of the global powder supplements market. It is projected to grow at a CAGR of around 9.9% through 2034, driven by convenience, personalization, and fitness trends.
2. What is the fastest-growing segment in the US powder dietary supplements market?
Weight management and personalized functional powders are the fastest-growing segments, reflecting consumer shifts toward fitness and condition-specific nutrition. Sports and performance nutrition remains the largest functionality segment at 38.9% share, but weight management and healthy aging are gaining momentum rapidly.
3. Who are the leading vendors in the US powder dietary supplements market?
Leading vendors include Herbalife, Amway (Nutrilite), GNC Holdings, Nature's Bounty, NOW Foods, Garden of Life, Optimum Nutrition, and USANA Health Sciences. Competition is fragmented, with differentiation built on brand trust, third-party certifications, and channel relationships rather than proprietary formulations.
4. What are the main challenges in the US powder dietary supplements market?
Key challenges include product quality and ingredient transparency concerns, taste and texture failures that discourage repeat purchase, and regulatory ambiguity under DSHEA. Independent testing has identified labeling inconsistencies, pushing consumers toward certified clean-label brands and raising compliance costs for manufacturers.
5. What is driving growth in the US powder dietary supplements market?
Growth is driven by demand for convenient, customizable nutrition; rising health consciousness (77% of US adults take supplements); an aging population; e-commerce and DTC expansion; and formulation innovation in probiotics, nootropics, and single-serve formats that improve palatability and ease of use.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary split, prioritizing direct industry engagement over desk research. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers, specialized powder producers, contract formulators and blenders, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads. This fieldwork captured procurement dynamics, formulation trends, and channel strategies that published data cannot fully reveal.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing & Procurement
30%
Heads of R&D & Formulation
30%
Technical Directors & Quality Leads
25%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Ingredient Suppliers
30%
Specialized Powder Producers & Formulators
35%
Contract Manufacturers & Blenders
20%
Distributors & Retailers
15%
Secondary Benchmarking & Public Trade Validation
We validate primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. These sources provide independent corroboration of market sizing, trade flows, and competitive positioning.
Demand Modeling & Market Sizing Triangulation
We triangulate sizing through simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) approaches. Discrepancies between the two methods are resolved through primary interview validation and weighted averaging.


 Us Powder Dietary Supplements Market