 Us Cordial Drink Market
US Cordial Drink Market Size, Share & Forecast 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 190

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Cordial Drink Market
Sakshi Gurunule
Research Associate

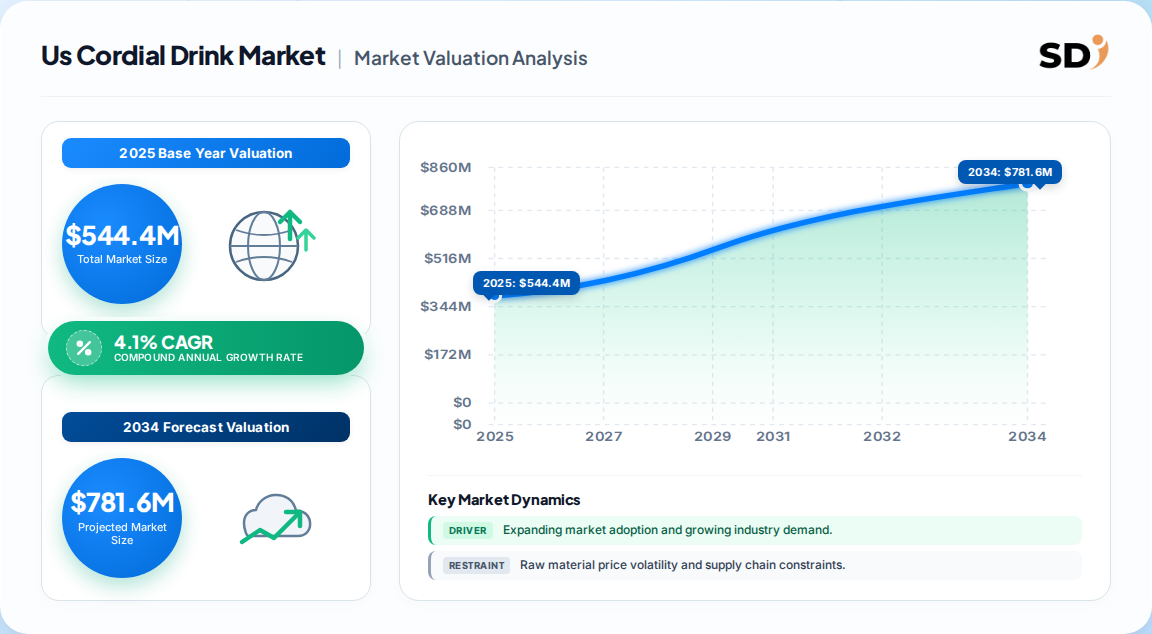
| Year | Market Size |
|---|---|
| 2025 | 544.0 M |
| 2026 | 562.0 M |
| 2027 | 585.0 M |
| 2028 | 609.0 M |
| 2029 | 634.0 M |
| 2030 | 660.0 M |
| 2031 | 687.0 M |

The U.S. cordial drink market comprises concentrated, non-alcoholic beverage syrups — typically fruit-, vegetable-, or botanical-based — that consumers dilute with water, soda, or spirits. These products serve household refreshment, at-home mixology, foodservice, and mocktail applications, with growing emphasis on low-sugar, natural, and premium formulations.
This analysis covers the U.S. cordial drink market across product types (fruit, vegetable, herbs & spices), distribution channels (supermarkets & hypermarkets, convenience stores, foodservice/HoReCa, and online), and source categories (organic and conventional). It addresses market sizing, segmentation, competitive dynamics, and strategic outlook through 2033. This analysis does not cover ready-to-drink beverages, flavored waters, functional beverage concentrates, or alcoholic cordials and liqueurs, which are tracked under separate categories.
The U.S. cordial drink market was valued at approximately USD 544.4 million in 2025, with forecasts diverging modestly across published estimates. The table below compares leading estimates and their underlying definitions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 544.4 M → 745.1 M | 2025 | 2033 | 4.1% | U.S.-only, non-alcoholic cordials, all channels | One published estimate |
| USD 387.1 M → 532.4 M | 2025 | 2034 | 3.5% | Global cordial drinks (narrower definition) | A competing analysis |
| USD 418.2 M → 621.4 M | 2026 | 2032 | 6.6% | Global cordial drinks, premium-inclusive | Another published estimate |
The U.S.-focused estimate of USD 544.4 million is the most defensible for domestic buyers: it aligns with observed retail channel concentration and non-alcoholic beverage share gains reported by SPINS. The wider global CAGRs of 3.5%–6.6% reflect differing treatment of premium mixers and botanical cordials. Our analysis suggests the U.S. market will track near the 4.1% midpoint, with upside from mocktail culture and multicultural flavor innovation.
The U.S. cordial drink market segments primarily by product type, distribution channel, and source. Fruit cordials remain the anchor segment, while herbs & spices and vegetable cordials offer the strongest innovation runway.
| Parent Segment | Children |
|---|---|
| By Product Type | Fruit Cordials, Vegetable Cordials, Herbs & Spices Cordials |
| By Distribution Channel | Supermarkets & Hypermarkets, Convenience Stores, Foodservice/HoReCa, Online |
| By Source | Organic, Conventional |
| By Packaging | Bottles, Cans, Pouches, Tetra Packs |
Fruit cordials accounted for 75.6% of 2025 U.S. revenue, supported by mango, orange, and strawberry familiarity. Herbs & spices cordials are forecast to grow at 4.5% CAGR, driven by botanical mixology and low-alcohol trends. Organic cordials command a premium and align with clean-label expectations among health-conscious buyers.
The South leads U.S. cordial consumption, accounting for an estimated 34% of national demand, followed by the West (23%), Northeast (22%), and Midwest (21%). Warmer climates, larger multicultural populations, and strong foodservice penetration support Southern leadership.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.22% |
| South | 0.34% |
| Midwest | 0.21% |
| West | 0.23% |
| Region | Est. Share |
|---|---|
| South | 34% |
| West | 23% |
| Northeast | 22% |
| Midwest | 21% |
Indented geography tree:
Our analysis suggests the West and South will outpace national growth due to Hispanic and Asian-American consumer bases seeking tropical and botanical flavors. The Northeast remains premium-skewed, with higher organic and low-sugar cordial penetration.
Growth is driven by rising non-alcoholic beverage preference, at-home mixology, and clean-label reformulation; restraint comes from ready-to-drink competition and shelf-space pressure. The balance favors moderate, steady expansion rather than breakout growth.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Non-alcoholic preference (40% health-conscious, 24% prefer NA taste) | Driver | High | Cordials as versatile mocktail bases |
| At-home mixology & cocktail culture | Driver | Medium-High | Premium, botanical, and exotic flavors |
| Clean-label & low-sugar reformulation | Driver | High | Health-conscious purchasing, levy-style pressure |
| Multicultural flavor innovation | Driver | Medium | Diverse consumer base seeking global profiles |
| Ready-to-drink & flavored water competition | Restraint | High | Convenience and shelf-space erosion |
| Sugar scrutiny and labeling regulation | Restraint | Medium | Reformulation costs, margin pressure |
The net effect is a market growing at roughly 4% annually, with premium and better-for-you sub-segments outpacing the core. Our analysis suggests brands that fail to reduce sugar and introduce culturally relevant flavors will cede shelf space to ready-to-drink alternatives.
The U.S. cordial drink market is moderately fragmented, with established beverage majors, specialty cordial producers, and private-label entrants competing on flavor innovation, health positioning, and channel reach.
| Company | Positioning | Key Strength |
|---|---|---|
| Welch's | Fruit-based, family-friendly | Brand trust, limited-edition innovation |
| SodaStream (PepsiCo) | Home carbonation + flavor concentrates | Installed base, at-home customization |
| Monin | Premium botanical and fruit syrups | Foodservice and mixology leadership |
| Torani | Flavor syrups for coffee and cocktails | Broad flavor portfolio, retail presence |
| Rose's | Traditional lime and cordial mixes | Legacy brand, cocktail familiarity |
| Private Label (retailers) | Value-tier cordials | Price competitiveness, shelf access |
Differentiation hinges on flavor innovation, clean-label credentials, and channel-specific packaging. Moats are built through foodservice relationships and brand heritage, while digital-native challengers leverage e-commerce and social discovery to bypass traditional retail gatekeepers.
Buyers and operators must prioritize formulation transparency, sweetener systems, and channel fit when selecting cordial suppliers. Mission-critical criteria include reduced-sugar capability (driven by evolving labeling thresholds), natural color and flavor sourcing, and packaging recyclability. Procurement risk centers on supply concentration in fruit concentrates and botanical extracts, where seasonal volatility can affect pricing and availability. Switching costs are moderate — reformulation and label approval cycles can take 6–12 months — so buyers should lock in multi-year agreements with contingency clauses. Regulatory compliance spans FDA labeling, state-level sugar taxes, and emerging front-of-pack nutrition rules. Foodservice operators should favor suppliers offering consistent dilution ratios and shelf-stable concentrates to reduce waste and standardize beverage menus.
The balance of evidence favors a cautious-but-constructive outlook for the U.S. cordial drink market. Growth of ~4.1% CAGR is supported by durable non-alcoholic tailwinds, but ready-to-drink competition and sugar scrutiny cap upside. The strongest counter-argument is that cordials remain a niche, seasonal category vulnerable to convenience-driven consumption shifts. However, the mixology and mocktail trend, combined with multicultural flavor demand, provides a structural floor that pure refreshment categories lack.
Our analysis suggests the most attractive opportunities lie in herbs & spices cordials, low-sugar fruit blends, and foodservice/HoReCa channels, where cordials offer operational standardization and waste reduction. Premiumization through botanical and globally inspired flavors can lift average unit prices and defend against private-label encroachment.
Actionable Strategy:
Evidence that would change our conclusion: a sustained acceleration in ready-to-drink innovation eroding cordial shelf space, or regulatory tightening on sweeteners beyond current thresholds, which would compress margins faster than reformulation can offset.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the cordial value chain, including fruit concentrate and botanical extract suppliers, specialized cordial producers, contract formulators and blenders, and national distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
Secondary validation draws on UN Comtrade and US ITC trade statistics for HS 220870 (liqueurs and cordials), FDA labeling databases, corporate 10-K and SEC filings, patent databases, and industry association publications such as the British Soft Drinks Association and UNESDA. These sources anchor volume and value benchmarks.
We apply simultaneous Top-Down (macroeconomic and retail channel allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) triangulation to reconcile divergent published estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | U.S. regional share breakdown | Cross-border trade flow & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.1% from 2020-2034 |
| Segmentation |
|
The U.S. cordial drink market was valued at USD 544.4 million in 2025 and is projected to reach USD 745.1 million by 2033, growing at a 4.1% CAGR.
Fruit cordials held a 75.6% revenue share in 2025, driven by consumer familiarity with mango, orange, and strawberry flavors. Herbs & spices cordials are the fastest-growing segment at 4.5% CAGR.
Rising non-alcoholic beverage preference, at-home mixology, clean-label reformulation, and multicultural flavor innovation are the primary growth drivers, supported by health-conscious consumers.
Supermarkets and hypermarkets accounted for 51.7% of 2025 revenue, though online and foodservice channels are gaining share as consumers seek convenience and specialty flavors.
Leading vendors include Welch's, SodaStream (PepsiCo), Monin, Torani, Rose's, and private-label retailers, competing on flavor innovation, health positioning, and channel reach.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the cordial value chain, including fruit concentrate and botanical extract suppliers, specialized cordial producers, contract formulators and blenders, and national distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement Directors | 35% |
| Heads of R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Fruit Concentrate & Botanical Suppliers | 35% |
| Specialized Cordial Producers | 40% |
| Contract Formulators & Blenders | 15% |
| National Distributors | 10% |
Secondary validation draws on UN Comtrade and US ITC trade statistics for HS 220870 (liqueurs and cordials), FDA labeling databases, corporate 10-K and SEC filings, patent databases, and industry association publications such as the British Soft Drinks Association and UNESDA. These sources anchor volume and value benchmarks.
We apply simultaneous Top-Down (macroeconomic and retail channel allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) triangulation to reconcile divergent published estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | U.S. regional share breakdown | Cross-border trade flow & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |