 Bubble Tea Market
 2026: Size, CAGR and Forecast to 2033
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 225

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Bubble Tea Market
Sakshi Gurunule
Research Associate
| Year | Market Size |
|---|---|
| 2025 | 3.300 B |
| 2026 | 3.600 B |
| 2027 | 4.100 B |
| 2028 | 4.600 B |
| 2029 | 5.200 B |
| 2030 | 5.900 B |
| 2031 | 6.600 B |

The Bubble Tea Market encompasses the global production, distribution, and retail sale of Taiwanese-origin tea-based beverages containing tapioca pearls or alternative toppings. It spans ready-to-drink bottled products, made-to-order café formats, and at-home DIY kits, serving consumers seeking customizable, experiential, and visually shareable refreshment.
This analysis covers the global Bubble Tea Market across type (black tea, green tea, oolong), flavor (fruit, taro, strawberry, chocolate, coffee), base ingredient (milk-based, plant-based), distribution channel (supermarkets, online retail, specialty stores, foodservice), and packaging form (PET/glass bottles, pouches, sealed cups). This analysis does not cover adjacent markets such as traditional tea, carbonated soft drinks, coffee, or functional beverages unless explicitly referenced as competitive context.
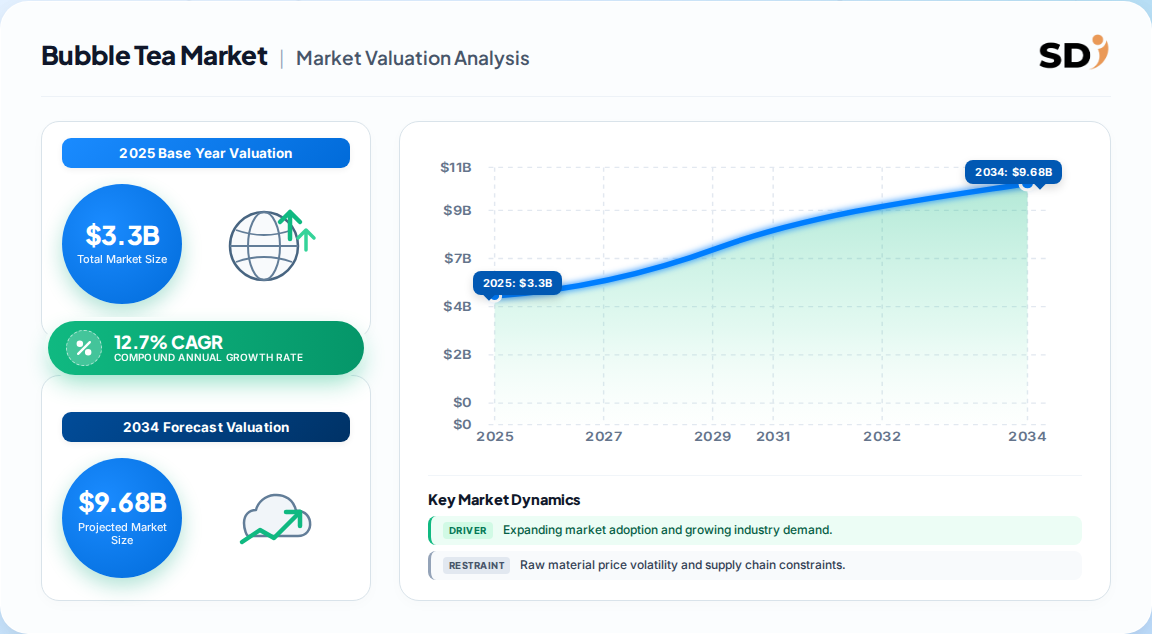
One published estimate places the global Bubble Tea Market at USD 3.3 billion in 2025, rising to USD 8.3 billion by 2033 at a 12.7% CAGR. A competing analysis values the market at USD 2.9 billion in 2025, forecasting USD 5.1 billion by 2034 at 6.28% CAGR. A third benchmark reports USD 2.72 billion in 2025, projecting USD 4.72 billion by 2031 at 9.56% CAGR. These divergences stem from scope differences — inclusion of RTD retail versus café-only sales, and treatment of DIY kits.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 3.3 Billion | 2025 | 2033 | 12.7% | Broad scope: café, RTD, DIY kits, all channels | One published estimate |
| USD 2.9 Billion | 2025 | 2034 | 6.28% | Includes RTD and DIY kits; base ingredient focus | A competing analysis |
| USD 2.72 Billion | 2025 | 2031 | 9.56% | Café-led, distribution-channel weighted | A third benchmark |
Our analysis suggests the broader 12.7% CAGR is most defensible for strategic planning because it captures the full value chain and aligns with observed franchise expansion, RTD launches, and social-media-driven trial. The 6.28% figure likely understates growth by excluding the fastest-growing RTD and kiosk formats.
The market segments by tea type, flavor, base ingredient, distribution channel, and packaging form. Black tea leads type at 43.1% share, fruit leads flavor at 38.3%, and milk-based drinks lead base ingredient at 58.04%. Online retail is the fastest-growing channel at 10.45% CAGR.
| Parent segment | Children | Leading share (2025) | Fastest-growing child |
|---|---|---|---|
| Type | Black tea, Green tea, Oolong tea | Black tea 43.1% | Green tea (13.6% CAGR) |
| Flavor | Fruit, Taro, Strawberry, Chocolate, Coffee | Fruit 38.3% | Taro (13.9% CAGR) |
| Base ingredient | Milk-based, Plant-based | Milk-based 58.04% | Plant-based (10.25% CAGR) |
| Distribution | Supermarkets/Hypermarkets, Online, Specialty stores, Foodservice | Supermarkets 46.84% | Online (10.45% CAGR) |
| Packaging | PET/Glass bottle, Pouches, Sealed cups | PET/Glass 51.11% | Pouches & sealed cups (10.36% CAGR) |
Asia-Pacific leads the global Bubble Tea Market with 38–45% revenue share in 2025, reflecting the beverage's Taiwanese origins and deep cultural embedding across China, Thailand, South Korea, and Southeast Asia. North America holds the second-largest share at 32–35%, while Europe accounts for approximately 18%.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.18% |
| Asia-Pacific | 0.38% |
| Middle East & Africa | 0.07% |
| South America | 0.05% |
One published estimate places Asia-Pacific at 45.18% revenue share in 2025 with North America as the fastest-growing region at 10.22% CAGR. A competing analysis reports Asia-Pacific at 37.6% with Middle East & Africa growing at 9.2% CAGR. Our analysis suggests the variance reflects differing treatment of China's domestic tea market versus branded chain revenue.
Growth is driven by a structural shift from carbonated soft drinks to tea-based alternatives, extreme customization, social-media virality, and rapid franchise expansion. Restraints center on sugar-related health concerns, supply-chain volatility for tapioca pearls, and high franchise saturation in mature Asian markets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Tea-based substitution for carbonated drinks | Driver | High | Health-conscious consumers seek antioxidants; sugar taxes widen price gap |
| Customization and personalization | Driver | High | 72% of consumers prefer adjustable ice and sugar; drives repeat purchase |
| Social media and Instagrammable aesthetics | Driver | Medium-High | Viral content drives trial; chains with strong aesthetics see 25% higher transaction values |
| Franchise and kiosk expansion | Driver | High | Master-franchise agreements transfer capital risk; automated brewing cuts labor 60% |
| Sugar and health concerns | Restraint | High | High sugar linked to obesity, heart disease, NAFLD; regulatory scrutiny rising |
| Raw material price volatility | Restraint | Medium | Tapioca pearl and tea leaf prices fluctuate with supply shocks |
The balance of evidence favors the drivers, but the sugar restriction is intensifying. Our analysis suggests operators that reformulate with zero-sugar syrups and plant-based milks will convert health-conscious consumers and mitigate regulatory risk. The restraint is not a demand killer but a margin and formulation challenge.
The competitive landscape is fragmented, with Asian-origin chains scaling globally through master-franchise agreements. Gong Cha, Tiger Sugar, CoCo Fresh, Chatime, and Kung Fu Tea lead on store count and brand recognition, while regional players compete on local flavors and price.
| Company | Headquarters | Key differentiator |
|---|---|---|
| Gong Cha | Taiwan | Technology-driven stores, loyalty apps, global master-franchise scale |
| Tiger Sugar | Taiwan | Brown-sugar boba specialization, premium positioning |
| CoCo Fresh | Taiwan | High-volume franchise network, pop-culture collaborations |
| Chatime | Taiwan | Broad international footprint, standardized operations |
| Kung Fu Tea | USA | North American brand strength, digital ordering |
| HeyTea | China | Premium fruit teas, limited-time collaborations, high social engagement |
Differentiation rests on customization depth, digital loyalty ecosystems, and supply-chain consistency. Moats are built through master-franchise relationships and proprietary topping supply, not product alone. Smaller operators compete on local flavor adaptation and speed of innovation.
Procurement decisions hinge on tea-leaf quality consistency, tapioca pearl shelf life, and clean-label sweetener availability. Switching costs are moderate: formulators can substitute syrups and milks, but topping supply chains and franchise agreements create lock-in. Regulatory compliance varies by market — sugar taxes in the UK and EU, FDA scrutiny of low-calorie sweeteners in the US, and halal certification requirements in the Middle East all affect formulation and labeling.
Operators should audit supplier certifications (ISO 22000, HACCP, halal) and model total landed cost, not unit price, because import tariffs on Taiwanese tea concentrates can erode margins. The rapid shift to plant-based milks requires qualifying oat and almond suppliers with consistent foaming performance under automated brewing. Finally, franchise disclosure documents and territory rights are critical: master-franchise structures transfer capital risk but limit control over brand execution.
The balance of evidence favors a bullish outlook: the 12.7% CAGR is credible because it is anchored in a structural substitution from carbonated drinks, not a fad. The strongest counter-argument is that sugar regulation and health concerns could compress margins faster than volume grows, particularly in Europe and North America. Our analysis suggests that risk is manageable through reformulation, and the operators that move first on low-sugar and plant-based menus will capture share from laggards.
A second-order effect deserves attention: the rise of automated brewing and kiosk formats lowers labor costs by 60%, enabling smaller footprints in high-rent urban areas. This will accelerate outlet density and compress independent cafés' margins, concentrating share among chains with centralized supply chains. Vendors that do not invest in automation and digital loyalty will face a widening cost gap.
What would change our conclusion: a sustained decline in Gen Z consumption frequency, or a wave of sugar taxes specifically targeting boba, would lower the CAGR toward the 6–7% range. We would also revise if franchise saturation in Asia-Pacific slows store-level same-store sales growth below inflation.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.7% from 2020-2034 |
| Segmentation |
|
The global Bubble Tea Market was valued at approximately USD 3.3 billion in 2025. One published estimate places it at USD 2.9 billion, with the variance reflecting scope differences in RTD and DIY kit inclusion.
The market is projected to grow at a 12.7% CAGR from 2026 to 2033, driven by tea-based substitution, customization, and franchise expansion. A more conservative estimate places CAGR at 6.28%.
Asia-Pacific leads with 38–45% revenue share, reflecting the beverage's Taiwanese origins. North America holds the second-largest share at 32–35% and is the fastest-growing region.
Leading vendors include Gong Cha, Tiger Sugar, CoCo Fresh, Chatime, Kung Fu Tea, and HeyTea. They compete on customization, digital loyalty, and master-franchise scale.
Key trends include health-oriented reformulation with low-sugar and plant-based options, RTD bottled boba expansion, social-media-driven aesthetics, and automated brewing for kiosk formats.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the value chain, including tea and tapioca suppliers, specialized beverage producers, contract formulators, and global distributors. Decision-makers interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, innovation, and go-to-market strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 35% |
| Heads of R&D & Innovation | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Tea & Tapioca Suppliers | 30% |
| Beverage Producers & Chains | 40% |
| Contract Formulators | 15% |
| Distributors & Retailers | 15% |
We validate findings against official multilateral databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized industry associations. These sources provide independent checks on trade flows, ingredient pricing, and franchise disclosure data.
We triangulate demand through simultaneous Top-Down macroeconomic and segment allocation models and Bottom-Up manufacturer capacity, product pricing, and end-use consumption models. This dual approach reconciles supply-side and demand-side estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
