 North America Otc Health Products Market
North America OTC Health Products Market 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 197

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 North America Otc Health Products Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2024 | 74.83 B |
| 2025 | 79.43 B |
| 2026 | 84.32 B |
| 2027 | 89.51 B |
| 2028 | 95.02 B |
| 2029 | 100.9 B |
| 2030 | 106.6 B |

The North America OTC health products market covers non-prescription consumer health goods sold without a prescription — including dietary supplements, weight-loss products, cough/cold/flu remedies, analgesics, digestive and women's health products, CBD nutraceuticals, and sports formulations — across retail, pharmacy, and online channels in the US, Canada, and Mexico.
This analysis covers OTC health products across product, application, form, demography, and distribution channel segments in the United States, Canada, and Mexico for 2018–2030. This analysis does not cover prescription pharmaceuticals, medical devices, clinical diagnostics, professional-only sports nutrition, or veterinary health products.
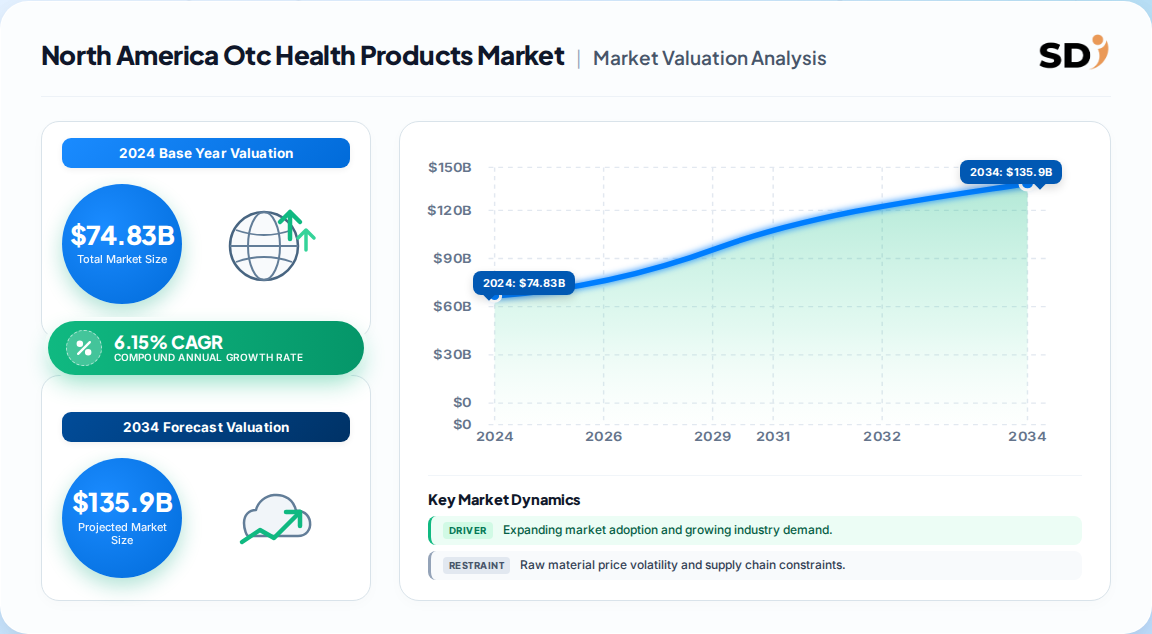
The most defensible base-year estimate is 74.83 Billion USD in 2024, with a 6.15% CAGR lifting the market to 106.61 Billion by 2030. Competing estimates diverge mainly on scope: broader OTC-drug definitions inflate the base, while narrower consumer-health definitions contract it.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 74.83 Billion | 2024 | 2030 | 6.15% | OTC health products incl. supplements, weight loss, CBD | One published estimate (primary benchmark) |
| 106.61 Billion | 2030 | 2030 | 6.15% | Same scope, terminal-year forecast | Same publisher, forecast edition |
| 62.98 Billion | 2021 | 2030 | 6.05% | OTC health products, narrower 2021 base | A competing analysis |
| 106.9 Billion | 2030 | 2030 | 6.05% | Terminal value under narrower base | Same competing analysis |
| 42.98 Billion (2026) | 2026 | 2031 | 8.08% | OTC drugs only (excludes supplements) | Separate OTC-drugs benchmark |
| 39.77 Billion (2025) | 2025 | 2031 | 8.08% | OTC drugs only, branded + generic | Same OTC-drugs benchmark |
Our analysis suggests the 74.83 Billion / 6.15% pair is the most defensible regional benchmark because it integrates supplements, weight loss, and CBD nutraceuticals — the three fastest-moving revenue pools. The OTC-drugs figures (42.98 Billion in 2026; 8.08% CAGR) describe a narrower, faster-growing therapeutic core and should be treated as a sub-segment, not a substitute. The ~1.9-point CAGR gap between the two datasets implies that value is migrating toward supplement-and-wellness formats rather than conventional cough/cold and analgesic SKUs.
Segments are defined across five non-geographic axes: product, application, form, demography, and distribution channel. Product and application together account for the bulk of revenue concentration.
| Parent | Children |
|---|---|
| Product | Cough, cold & flu; Dietary supplements & weight loss; CBD nutraceuticals; Digestive; Women's health; Analgesics; Others |
| Application | Sports formulation; Immune defense; Digestive health; Women's health; Pain management; Others |
| Form | Capsules & tablets; Liquids; Gummies; Powders; Sprays & drops; Others |
| Demography | Adults; Children; Elderly |
| Distribution channel | Hypermarkets/supermarkets/convenience; Retail pharmacies; Online pharmacies; Others |
The United States leads with roughly 73% of regional revenue, followed by Canada (~17%) and Mexico (~10%). Canada is the fastest-growing country market at approximately 6.9% CAGR, driven by preventive-health adoption and digital pharmacy expansion.
| Country | Share (2024) | Growth posture |
|---|---|---|
| United States | ~73% | Mature; innovation and switch-driven |
| Canada | ~17% | Fastest-growing (~6.9% CAGR) |
| Mexico | ~10% | Emerging; herbal and branded OTC focus |
Growth is powered by self-medication, Rx-to-OTC switches (naloxone 2023; Opill 2024), e-commerce expansion, and an aging population. Restraints center on API supply risk, monograph modernization delays, and analgesic/cough-medicine misuse.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Self-medication & preventive care | Driver (+1.80% CAGR) | Strong | 81% of adults use OTC as first-line relief |
| Rx-to-OTC switch approvals | Driver (+1.20% CAGR) | Strong | Opens high-value categories previously prescription-only |
| E-commerce & digital pharmacy | Driver (+2.10% CAGR) | Strong | Price transparency, auto-refill, same-day delivery |
| Aging population & chronic self-care | Driver (+1.50% CAGR) | Strong | 65+ cohort has highest per-capita OTC consumption |
| Hispanic herbal OTC demand | Driver (+0.70% CAGR) | Moderate | Growth in US Southwest, California, Texas, Florida |
| AI-driven personalization | Driver (+0.40% CAGR) | Emerging | Early adoption in tech-forward regions |
| Substance misuse (analgesics, cough) | Restraint (−0.90% CAGR) | Strong | Package-size limits and age verification |
| FDA monograph modernization delays | Restraint (−0.60% CAGR) | Moderate | Slows switch pipeline and label harmonization |
| API supply-chain disruption from Asia | Restraint (−1.10% CAGR) | Strong | Raises input cost and lead-time volatility |
| PBM margin pressure on SMEs | Restraint (−0.80% CAGR) | Moderate | Constrains shelf space for independent manufacturers |
Our analysis suggests the net driver stack (+7.7% combined pull vs −3.4% drag) is consistent with a 6.15% realized CAGR — implying roughly 1.3 points of friction from regulatory delay and supply volatility. The single largest second-order effect is the proposed HHS rule to bring certain OTC preventive services under ACA insurance coverage; if finalized, it would convert Medicaid and private-insurance consumers from out-of-pocket buyers to reimbursed purchasers, structurally expanding the addressable base for contraception and smoking-cessation OTCs.
The market is fragmented but top-tier vendors hold disproportionate shelf and brand equity. Leading players span pharma majors and specialist supplement and CBD firms, with differentiation anchored in brand trust, clinical substantiation, and channel breadth.
| Company | Category focus | Competitive moat |
|---|---|---|
| Bayer AG | Analgesics, supplements, dermatology | Global brand trust; pharmacy relationships |
| Johnson & Johnson | Cough/cold, analgesics, oral care | Portfolio breadth; clinical credibility |
| GlaxoSmithKline (GSK) | Respiratory, digestive, pain | Rx-to-OTC switch capability |
| Herbalife Nutrition | Weight management, sports nutrition | Direct-sales network; loyalty base |
| Nestlé Health Science (Bountiful) | Vitamins, minerals, supplements | Retail distribution scale |
| CV Sciences / Medical Marijuana Inc. | CBD nutraceuticals | Early CBD brand equity; formulations |
| Nature's Sunshine Products | Herbal supplements | Natural-positioning heritage |
Differentiation is shifting from mass-media brand building toward clinical substantiation and e-commerce merchandising. Vendors with switch-ready dossiers and digital shelf-optimized packaging are best positioned; private-label growth at ~8.3% CAGR is compressing margins for undifferentiated mid-tier brands.
Procurement teams should prioritize vendors with USP-verified or NSF-certified quality systems and traceable API sourcing, given the −1.10% CAGR drag from Asian supply-chain disruption. Switching costs are low at the SKU level but high at the regulatory dossier level — qualifying a new supplier for a switch-approved product can take 12–18 months.
Regulatory compliance is the dominant selection criterion: FDA monograph conformity, state-level CBD rules, and Canadian NHP licensing each create distinct qualification paths. Operators should model package-size limits and age-verification requirements for analgesics and cough medicines into channel economics, and should stress-test pricing against PBM-driven shelf consolidation. Buyers renegotiating contracts in 2026–2027 should seek dual-sourced API clauses and switch-pipeline optionality as standard terms, since category boundaries will shift materially once the HHS preventive-services rule is finalized.
The balance of evidence favors a 6.1–6.2% medium-term CAGR for the broad OTC health products market, with upside risk from insurance coverage of preventive OTCs and downside risk from API disruption. The strongest counter-argument is that the OTC-drugs benchmark's 8.08% CAGR signals faster growth in the therapeutic core than the broad-market number implies — a defensible view if switch approvals accelerate beyond naloxone and Opill into migraine and statin categories.
Our judgment: the broad-market figure is the right planning base, but operators should segment their forecasts — applying the higher drug-core growth rate to switch-eligible categories and the lower supplement rate to commodity vitamins, where private-label pressure is most acute.
Actionable Strategy:
Evidence that would change our conclusion: a finalized HHS rule extending ACA coverage to OTC preventive services, or a wave of FDA approvals for migraine/statin switches, would justify shifting the planning CAGR toward 7.5–8.0%.
| Region | Market Share (%) |
|---|---|
| United States | 0.73% |
| Canada | 0.17% |
| Mexico | 0.1% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.15% from 2020-2034 |
| Segmentation |
|
The market was estimated at 74.83 Billion USD in 2024 and is projected to reach 106.61 Billion USD by 2030, expanding at a 6.15% CAGR over the 2025–2030 forecast period.
Dietary supplements and weight loss products led with a 33.71% revenue share in 2024. Capsules and tablets dominate form factor at 37.79%, while CBD nutraceuticals are the fastest-growing product class.
The United States leads with approximately 73% of regional revenue, followed by Canada at around 17% and Mexico at around 10%. Canada is the fastest-growing country market at roughly 6.9% CAGR.
Key drivers include rising self-medication and preventive healthcare, Rx-to-OTC switch approvals such as naloxone and Opill, e-commerce and digital pharmacy expansion, and an aging population with chronic self-care needs.
Leading vendors include Bayer AG, Johnson & Johnson, GlaxoSmithKline (GSK), Herbalife Nutrition, Nestlé Health Science (Bountiful), CV Sciences, Medical Marijuana Inc., and Nature's Sunshine Products.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material and API suppliers, specialized supplement and OTC producers, contract formulators, and global distributors. Interviewees included VP-level Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both supply-side capability and demand-side purchasing behavior.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 30% |
| Heads of R&D | 25% |
| Technical Directors | 25% |
| Commercial Operations Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| API & Raw Material Suppliers | 30% |
| OTC & Supplement Manufacturers | 35% |
| Contract Formulators | 20% |
| Distributors & Retailers | 15% |
Secondary validation draws on UN Comtrade and WTO trade-flow databases, US ITC and Eurostat import/export records, SEC 10-K filings and investor presentations from listed manufacturers, patent databases for formulation and delivery-system innovation, and standards and technical guidance from the US FDA, Health Canada, and USP/NSF quality programs.
Market sizing triangulates a Top-Down allocation (macroeconomic consumption, channel revenue, and category share) against a Bottom-Up model (manufacturer capacity, product pricing, and end-use consumption). Divergences between the two models are reconciled through historical CAGR regression and demand elasticity analysis.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |