 Non Alcoholic Beer Market
: $24.3B to $52B by 2035
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 202

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Non Alcoholic Beer Market
Sakshi Gurunule
Research Associate

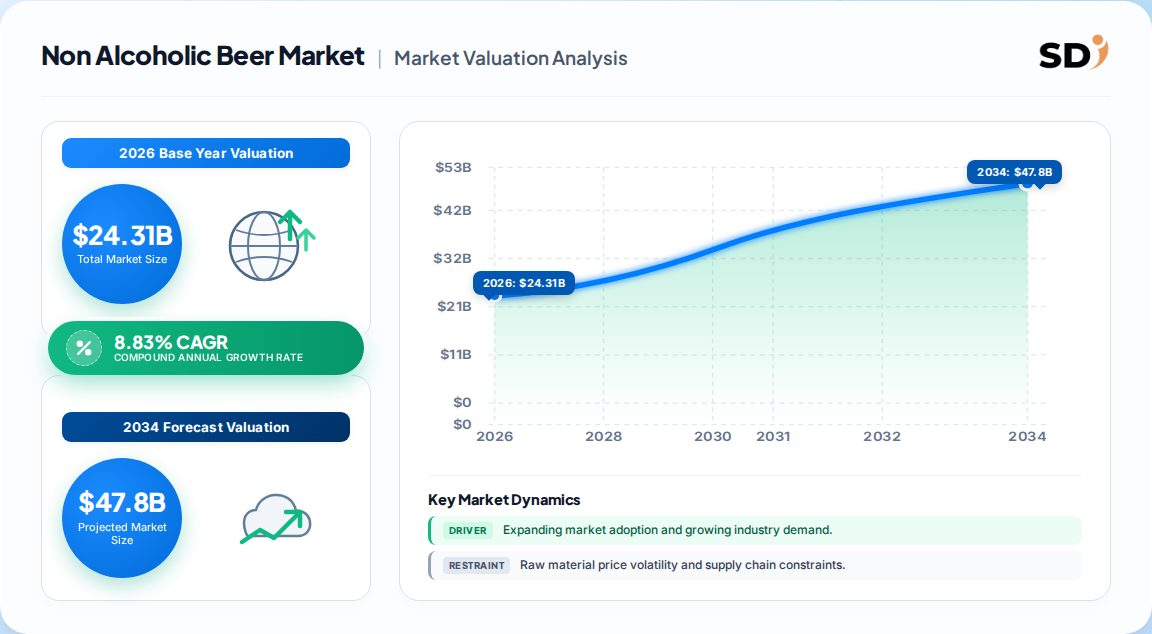
| Year | Market Size |
|---|---|
| 2025 | 22.00 B |
| 2026 | 24.31 B |
| 2027 | 26.46 B |
| 2028 | 28.80 B |
| 2029 | 31.34 B |
| 2030 | 34.11 B |
| 2031 | 37.12 B |

The non-alcoholic beer market covers malt-based beer sold at a maximum of 0.5% ABV, spanning fully alcohol-free 0.0% products and low-alcohol variants. It is valued at retail selling prices across supermarkets, convenience stores, specialty outlets, online sellers, and bars, including draught serves.
This analysis covers global malt-based beer at ≤0.5% ABV across alcohol-free and low-alcohol types, all flavor categories, packaging formats, and both store-based and non-store-based channels. This analysis does not cover soft drinks, malt-based RTD cocktails, functional beverages without beer character, or cannabis-infused drinks.
Published estimates for 2025–2026 cluster between USD 21.7 Billion and USD 26.2 Billion, with forecast horizons ranging from 2030 to 2035. The spread reflects definitional differences more than genuine disagreement about demand.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 22.00 Billion | 2025 | 2035 (USD 52.04B) | 8.83% | ≤0.5% ABV malt beer, retail selling prices | One published estimate |
| USD 23.84 Billion | 2025 | 2030 (USD 38.66B) | 10.2% | 0–1.2% ABV, includes near-beer | A competing analysis |
| USD 21.72 Billion | 2025 | 2035 (USD 41.70B) | 6.74% | Alcohol-free and low-alcohol, retail value | A competing analysis |
| USD 20.94 Billion | 2024 | 2032 (USD 37.07B) | 7.4% | NA beer revenue, production-weighted | A competing analysis |
Our analysis suggests the 8.83% CAGR path is the most defensible central case. The 10.2% figure relies on a 1.2% ABV ceiling that pulls low-alcohol near-beer into scope, inflating the base. The 6.74% figure is conservative on Asia Pacific capacity. The mid-8s path reconciles volume growth of roughly 3,550 million liters in 2025 with the premiumization mix shift that vendors are actively engineering.
Segmentation runs across four primary axes: product type, ABV level, flavor category, and distribution channel. Packaging is a secondary axis, with cans gaining share on portability and recyclability.
| Parent segment | Children |
|---|---|
| By Type | Alcohol-free, Low-alcohol |
| By ABV Level | 0.0%, Up to 0.05%, 0.05–0.5% |
| By Flavor | Plain, Flavored |
| By Packaging | Bottles, Cans, Draught |
| By Distribution Channel | Store-based (supermarkets, convenience, specialty), Non-store-based (online, direct) |
Alcohol-free dominates value at roughly 56% of revenue, but low-alcohol is the faster-growing child (7.6%+ CAGR) because it retains traditional beer mouthfeel. Flavored variants are the fastest-growing category, driven by fruit and botanical extensions aimed at younger buyers. Draught is small today but is the highest-margin format where brewers can secure bar taps.
Europe leads with approximately 38% of global revenue, supported by established brewing infrastructure, a mature moderation culture, and draught distribution of brands such as Heineken 0.0. Asia Pacific is the fastest-growing region on brewer capacity commitments and premiumization.
| Region | Market Share (%) |
|---|---|
| Europe | 0.38% |
| North America | 0.27% |
| Asia-Pacific | 0.22% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
| Region | Share |
|---|---|
| Europe | 38% |
| North America | 27% |
| Asia Pacific | 22% |
| Latin America | 7% |
| Middle East & Africa | 6% |
This divergence implies two very different commercial playbooks. Europe rewards on-premise execution and draught placement; Asia Pacific rewards capacity investment and premium brand building. Vendors running a single global strategy will underperform in at least one of these regions.
Falling alcohol participation and dedicated no-alcohol brewing capacity are lifting demand, while US can tariffs and rigid UK labeling slow can-led launches. The net balance still favors growth, but with a mix shift toward premium, flavored, and on-premise formats.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Falling US drinking participation | Driver | High — Gallup trend | 54% of US adults drink, a record low; shifts occasions to zero-alcohol lager |
| Dedicated NA brewing capacity | Driver | High — capacity disclosures | Athletic Brewing's San Diego plant doubled capacity to 1.2M barrels |
| Dealcoholization technology + draught | Driver | Medium-High | Heineken 0.0 draught placements move NA beer into the bar round |
| US aluminum can tariffs | Restraint | Medium | 50% Section 232 tariff raises per-case packaging costs |
| UK alcohol-free definition | Restraint | Medium | 0.05% ABV cap pushes UK brewers toward costlier dealcoholization |
Our analysis suggests the drivers are structural rather than cyclical. The demand is occasion-driven, not consumer-conversion-driven: buyers are not leaving beer, they are adding a beer-tasting drink to weekday lunch, the drive home, and the second round. That keeps brand equity and supermarket beer aisles in play. The restraints are cost and compliance frictions that shift mix rather than suppress volume.
Anheuser-Busch InBev leads with over 2.5% share, but the top five brewers together hold under 8% of the global category. This is an unusually fragmented structure for a beer-adjacent market and signals that scale advantages have not yet consolidated.
| Company | Position | Differentiation |
|---|---|---|
| Anheuser-Busch InBev | Leader, >2.52% share | Portfolio breadth across 0.0 and low-alcohol; global distribution |
| Carlsberg Group | Top 5 | Regional strength in Europe; 0.0 flagship extensions |
| Heineken N.V. | Top 5 | Draught 0.0 placements; Heineken 0.0 Ultimate extension |
| Kirin Holdings | Top 5 | Japan-origin technology; Asia Pacific distribution |
| Boston Beer Company | Top 5 | Craft credibility; US natural-food channel access |
| Athletic Brewing | Specialist | Dedicated NA capacity; craft IPA leadership |
This divergence implies competitive moats are still being built. Brand heritage transfers from full-strength beer, but taste parity at the tap and reliable supply of fresh craft-style cans matter more. The brewer that pairs a bar tap with a grocery shelf facing in the same market builds a defensible position faster than one that does only one.
Procurement in this category turns on four criteria: taste parity with full-strength beer, supply reliability during January and summer peaks, packaging cost exposure, and regulatory labeling compliance by market.
Supply reliability is the most under-priced risk. Retailers have repeatedly been short of fresh craft-style no-alcohol cans during peak periods, and the constraint is dedicated capacity, not demand. Buyers who lock multi-year supply agreements with dedicated-capacity producers will avoid the seasonal reset risk that has cost shelf facings in prior cycles.
Packaging cost exposure is concentrated in the US, where a 50% Section 232 tariff on finished aluminum cans raises per-case costs for can-led brands. Operators should model a can-versus-bottle cost delta through 2027 and consider bottle or draught formats where the tariff burden is heaviest.
Regulatory compliance is market-specific and non-negotiable. The UK's 0.05% ABV ceiling for "alcohol-free" labeling forces costlier dealcoholization, while other markets allow up to 0.5%. Multi-market operators need a labeling compliance matrix before launch, not after. Switching costs are low for consumers but high for retailers, who face reset costs when a brand fails to deliver.
The balance of evidence favors the mid-8s CAGR path as the central case, with the 10.2% and 6.7% estimates representing scope and regional-capacity outliers. The category's defining feature is not its growth rate but its fragmentation: with the top five brewers holding under 8% share, there is no incumbent whose shelf position is safe, and no challenger whose position is secure. That creates a rare window for operators to set price architecture and channel strategy before consolidation.
The strongest counter-argument is that taste parity at the tap remains unproven at scale, and if draught quality disappoints, the on-premise leg of the growth thesis weakens materially. Our analysis treats this as a 2027-onward risk rather than a 2026 one, because current draught placements are still in test markets. Watch Heineken 0.0 tap quality scores and US drinking-participation polling as the two leading indicators that would change our conclusion.
What would change our conclusion: a reversal in US drinking participation, a slow ramp-up of new dedicated capacity, or a sustained failure of draught taste parity would each pull the outlook down by 100–200 basis points.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.83% from 2020-2034 |
| Segmentation |
|
The global non-alcoholic beer market is valued at approximately USD 24.31 Billion in 2026, according to the most widely cited published estimate. Values across published sources range from USD 21.7 Billion to USD 26.2 Billion depending on whether low-alcohol near-beer up to 1.2% ABV is included.
The central-case CAGR is 8.83% for 2026–2035, reaching USD 52.04 Billion by 2035. Competing estimates range from 6.74% to 10.2%, with the spread driven mainly by definitional differences in ABV ceilings and forecast horizons.
Europe leads with approximately 38% of global revenue, supported by mature moderation culture and draught distribution of brands such as Heineken 0.0. Asia Pacific is the fastest-growing region, driven by brewer capacity commitments and premiumization.
Anheuser-Busch InBev leads with over 2.52% share, followed by Carlsberg Group, Kirin Holdings, Heineken N.V., and Boston Beer Company. The top five together hold under 8% of the global category, indicating a highly fragmented competitive structure.
Falling alcohol participation, especially in the US where only 54% of adults drink, is the primary demand driver. Dedicated no-alcohol brewing capacity and dealcoholization technology that enables draught service are the two supply-side drivers expanding availability and occasions.
US Section 232 tariffs keeping finished aluminum cans at 50% raise per-case packaging costs for can-led brands. The UK's 0.05% ABV ceiling for alcohol-free labeling forces costlier dealcoholization, slowing range extensions in that market.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, with 70% of analytical weight placed on structured interviews and 30% on secondary benchmark validation. We conducted in-depth interviews with stakeholders across five value-chain segments: malt and hop suppliers, dedicated non-alcoholic breweries, contract dealcoholization specialists, global beverage distributors, and on-premise operators. Interviewees were drawn from four decision-maker designations: VP of Sourcing, Heads of R&D and Brewing Innovation, Technical Directors, and Commercial Operations Leads. Each interview followed a semi-structured protocol covering capacity, pricing, taste-parity benchmarks, and market-entry sequencing, and transcripts were coded against a fixed analytical framework to preserve comparability across regions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 28% |
| Heads of R&D and Brewing Innovation | 30% |
| Technical Directors | 22% |
| Commercial Operations Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| Malt, Hop & Ingredient Suppliers | 22% |
| Dedicated NA Breweries | 30% |
| Contract Dealcoholization Specialists | 18% |
| Global Distributors & Retailers | 30% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO Tariff Analysis Online, US ITC DataWeb, Eurostat Comext), corporate annual filings (10-K, SEC filings, investor presentations), patent databases for dealcoholization and reverse-osmosis processes, and recognized non-profit technical standards and industry associations. These sources anchor tariff exposure, labeling thresholds, and capacity commitments to verifiable public records rather than to unsourced estimates.
We triangulate simultaneously from the top down (macroeconomic beverage allocation, per-capita occasion modeling, and industry segment sizing) and from the bottom up (manufacturer capacity, product-level pricing, and end-use consumption modeling). Divergence between the two paths is resolved through primary interview evidence and trade-flow reconciliation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |