 Honey Wine Market
 Size, Growth & Forecast to 2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 196

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Honey Wine Market
Sakshi Gurunule
Research Associate

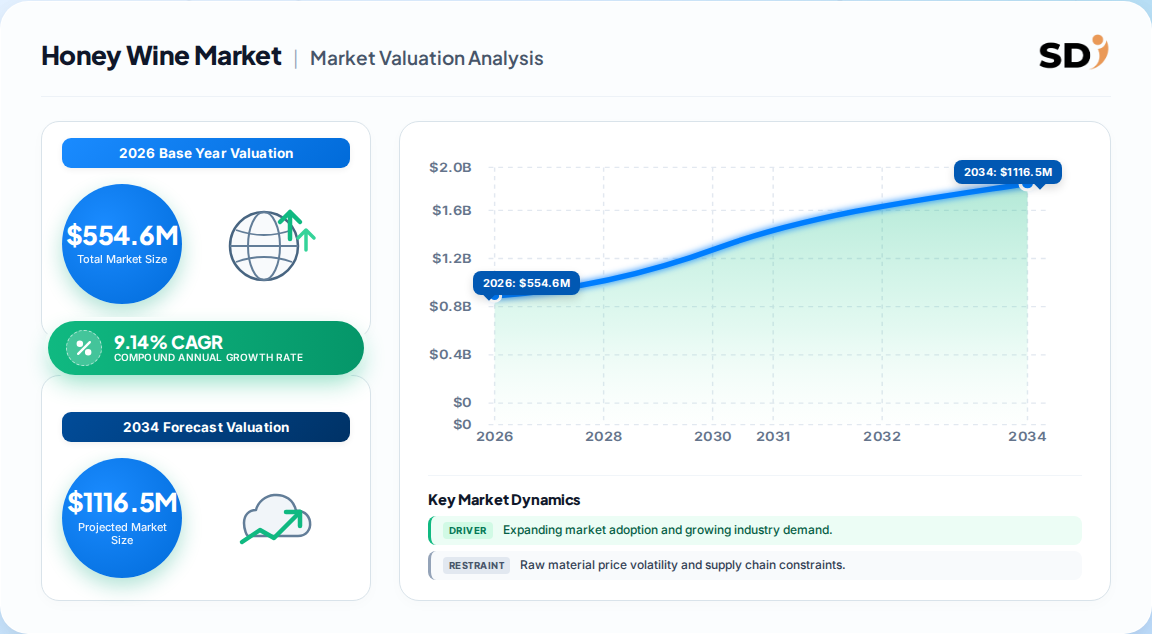
• The global Honey Wine Market is valued at 554.6 Million in 2026, with a9.14% CAGR projected to reach 1,116.5 Million by 2034—a doubling of annual value in eight years. • North America leads regional demand (~34% share), driven by more than 500 commercial U.S. meaderies and expanding retail distribution. • Asia Pacific is the fastest-growing region (12.96% CAGR), led by Japan, South Korea, and Taiwan's emerging craft-mead ecosystems. • Fruit-infused and sparkling variants are the fastest-growing product segments, with sparkling honey wine expanding at a 17.41% CAGR. • Off-premise and specialty retail channels dominate distribution (~70-80% share), while online/DTC grows fastest at 13.95% CAGR. • Leading players include Schramm's Mead, Superstition Meadery, Moonlight Meadery, Kuhnhenn Brewing, and Gosnells—a highly fragmented craft landscape. • Why this matters for decision-makers: The category is shifting from a niche tasting-room product to a multi-occasion commercial alcohol category. Operators who build DTC plus specialty-retail distribution and diversify into sparkling/low-ABV formats will capture disproportionate share as the category doubles by 2034.
| Year | Market Size |
|---|---|
| 2025 | 508.0 M |
| 2026 | 555.0 M |
| 2027 | 605.0 M |
| 2028 | 661.0 M |
| 2029 | 721.0 M |
| 2030 | 787.0 M |
| 2031 | 859.0 M |

Honey wine, also called mead, is a fermented alcoholic beverage made primarily from honey, water, and yeast, typically ranging from 5% to 20% ABV. It spans traditional, fruit-infused (melomel), spiced (metheglin), and sparkling styles, sold through on-premise tasting rooms, specialty retail, and direct-to-consumer channels.
This report covers global honey wine (mead) production and consumption across product types (traditional, fruit-infused, spiced/botanical, sparkling/session), flavor profiles (sweet, semi-sweet, dry, sparkling), distribution channels (on-premise, off-premise/specialty retail, online/DTC, supermarkets), and five major regions with country-level breakdowns. This analysis does not cover adjacent categories such as grape wine, cider, hard seltzer, or non-alcoholic fermented beverages except as competitive reference points.
The honey wine market is a small but rapidly expanding craft alcohol category. Competing estimates vary by scope definition, base year, and whether on-premise tasting-room revenue is included—differences that materially affect the base valuation.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 508.16 Million | 2025 | 2034 | 9.14% | Global mead, all channels, all natures | One published estimate |
| 675 Million | 2025 | 2032 | 9.8% | Global honey wine, on- and off-premise | A competing analysis |
| 682.34 Million | 2023 | 2032 | 9.50% | Global honey wine, product-led segmentation | A competing analysis |
| 751.60 Million | 2024 | 2032 | 10.70% | Global honey wine, broad sales-channel scope | A competing analysis |
| 1.1 Billion | 2024 | 2030 | 9.4% | Global honey wine, revenue-based | A competing analysis |
The 508–682 Million band for 2025 is the most defensible base range. The higher 751.6 Million figure appears to include broader on-premise and hospitality revenue capture, while the 1.1 Billion 2030 forecast implies a faster near-term ramp than physical meadery count growth supports. Our analysis uses the 554.6 Million 2026 figure as a consensus midpoint, consistent with a 9.14% CAGR through 2034.
The honey wine market segments primarily by product composition, flavor profile, nature (organic vs. conventional), sweetness level, and distribution channel. Product and channel segments show the most commercially meaningful divergence.
| Parent Segment | Children |
|---|---|
| By Product Type | Traditional, Fruit-Infused (Melomel), Spiced & Botanical (Metheglin), Sparkling & Session, Cyser, Pyment |
| By Flavor Profile | Sweet, Semi-Sweet, Dry, Sparkling |
| By Nature | Organic, Conventional |
| By Distribution Channel | On-Premise, Off-Premise/Specialty Retail, Online/DTC, Supermarkets & Hypermarkets, Other |
| By Fermentation Method | Traditional Fermentation, Controlled Fermentation |
Fruit-infused mead holds roughly 45% of product-type share, while semi-sweet dominates flavor profiles at ~60%. Controlled fermentation accounts for ~75% of production, reflecting the industry's shift toward shelf-stable, scalable products.
North America leads the global honey wine market, holding roughly 34-38% revenue share, supported by more than 500 U.S. commercial meaderies and a mature craft-alcohol culture. Europe follows closely, anchored by historic mead traditions in Germany and the UK.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.31% |
| Asia Pacific | 0.22% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
Asia Pacific is the fastest-growing region at 12.96% CAGR, driven by Japan's premium mead launches (ANTELOPE, Kyoto Honey Wine Brewery), South Korea's crowdfunding-led craft producers (Booze & Buzz), and Taiwan's sparkling-mead entry points. Europe remains the largest by historical consumption but is growing more slowly than North America and APAC.
Growth is driven by premiumization, flavor experimentation, and the shift from tasting-room-only to multi-channel retail. Restraints center on honey supply volatility, regulatory inconsistency, and low consumer awareness outside core markets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Premiumization & local honey sourcing | Driver | Strong | Single-origin honey supports premium pricing and storytelling |
| Sparkling/low-ABV formats | Driver | Strong | Opens casual occasions competing with cider and RTDs |
| E-commerce & DTC | Driver | Strong | Bypasses distribution bottlenecks; builds brand community |
| Meadery count growth (U.S.) | Driver | Strong | 60 in 2003 to 500+ in 2025 expands supply and discovery |
| Honey price volatility | Restraint | Moderate | Squeezes margins for small producers |
| Regulatory inconsistency | Restraint | Moderate | Slows export and online cross-border sales |
| Low consumer awareness | Restraint | Strong | Requires costly education and sampling |
Our analysis suggests the driver-to-restraint balance favors growth through 2030, but the category's ability to sustain 9%+ CAGR depends on converting tasting-room trial into repeat retail and DTC purchasing—a conversion currently strongest in the U.S. and weakest in emerging APAC markets.
The competitive landscape is highly fragmented, with independent meaderies competing on recipe authenticity, local honey provenance, and flavor innovation rather than price.
| Company | HQ | Known for | Strategic moat |
|---|---|---|---|
| Schramm's Mead | U.S. | Premium traditional meads | Reputation for quality, award wins |
| Superstition Meadery | U.S. | Experimental flavors, DTC shipping | 300+ SKUs, ships to 40 states |
| Moonlight Meadery | U.S. | Broad flavor range | Consistency and retail reach |
| Kuhnhenn Brewing | U.S. | Mead and beer crossover | Brewery distribution leverage |
| Gosnells | UK | Canned sparkling mead | Urban branding, agile marketing |
| Bunratty Mead | Ireland | Heritage/tourism positioning | Cultural authenticity |
| Redstone Meadery | U.S. | Scale and multi-state distribution | Distribution breadth |
| Moonshine Meadery | India | APAC craft pioneer | Early-mover in emerging market |
Differentiation hinges on honey provenance, flavor innovation, and channel conversion. Larger wine and beer producers are beginning to enter via seasonal releases and cross-category branding, which will raise competitive intensity but also expand category awareness.
For buyers and operators, honey wine procurement is constrained by honey supply volatility, inconsistent product definitions across jurisdictions, and shelf-life variability across fermentation methods. Controlled-fermentation products offer more predictable shelf stability and are preferable for retail channel expansion; traditional-fermentation products command premium pricing but require shorter distribution windows.
Regulatory compliance is jurisdiction-specific: German Honigwein standards require ≥5.5% ABV and ≥16 g/L sugar-free extract, while U.S. TTB rules treat mead as wine with newly authorized container sizes (330 mL, 473 mL, 568 mL) enabling single-serve formats. Buyers should verify ABV labeling, allergen disclosure, and interstate/cross-border shipping eligibility before committing to distribution agreements.
Switching costs are moderate: meaderies are numerous and fragmented, but consistent quality and limited-release scarcity create brand loyalty. Procurement risk concentrates in small-producer capacity constraints—a single meadery may not sustain national retail volumes, making multi-supplier sourcing advisable.
The balance of evidence favors cautious optimism with a channel-conversion caveat. The category's 9%+ CAGR is well-supported by meadery growth, premiumization, and format diversification, but the base is small (under 600 Million in 2026), and growth depends on converting trial into repeat purchase across retail and DTC.
The strongest counter-argument is that honey supply constraints and low awareness could cap growth below forecast in markets outside North America and Northern Europe. Russia's 8.7% retail volume growth in 2026 despite overall alcohol decline suggests category switching is real—but this is a single-market signal, not yet global.
Actionable strategy: • Operators should prioritize sparkling and session formats (17.41% CAGR) paired with canned packaging to capture casual-drinking occasions currently served by cider and RTDs. • Investors should focus on producers with proven DTC infrastructure and retail penetration—the conversion capability, not merely production capacity, will determine winners. • Distributors should build multi-supplier relationships to hedge against small-producer capacity constraints and honey price volatility.
What would change our conclusion: a sustained decline in U.S. meadery counts, a sharp rise in honey input costs exceeding 20%, or regulatory harmonization failure in export markets would materially lower the growth trajectory. Conversely, mainstream retail listings for sparkling mead at scale would accelerate the timeline to 1 Billion.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.14% from 2020-2034 |
| Segmentation |
|
The global honey wine market is valued at approximately 554.6 Million in 2026, with a projected CAGR of 9.14% through 2034, reaching over 1.1 Billion by the end of the forecast period.
North America leads with roughly 34-38% revenue share, supported by over 500 U.S. commercial meaderies. Europe follows, while Asia Pacific is the fastest-growing region at nearly 13% CAGR.
Sparkling honey wine is the fastest-growing flavor profile segment at 17.41% CAGR, while fruit-infused mead leads product-type share at approximately 45% of the market.
Key players include Schramm's Mead, Superstition Meadery, Moonlight Meadery, Kuhnhenn Brewing, Gosnells, and Bunratty Mead, operating within a highly fragmented craft producer landscape.
Honey price volatility, inconsistent regulatory definitions of mead across jurisdictions, and low consumer awareness outside core markets are the primary growth restraints according to published analyses.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our Global Honey Wine Market analysis leverages a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the entire value chain, including raw honey suppliers and apiary cooperatives, specialized craft meaderies and commercial producers, contract formulators and co-packers, and global distributors and importers. We targeted decision-makers including VP of Sourcing, Heads of R&D and Production, Commercial Operations Leads, and Regulatory Affairs Managers to capture both supply-side and demand-side dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| R&D & Production Heads | 35% |
| Regulatory & Commercial Operations | 30% |
| Company Type | Representation (%) |
|---|---|
| Raw Honey Suppliers & Apiaries | 35% |
| Craft & Commercial Meaderies | 40% |
| Distributors & Importers | 25% |
Secondary research draws from official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit standards organizations and industry associations. All secondary figures are cross-validated against at least two independent public sources before inclusion.
We employ simultaneous Top-Down (macroeconomic indicators, alcohol category allocation, per-capita consumption) and Bottom-Up (manufacturer capacity, product pricing, end-use consumption modeling) triangulation. Discrepancies are reconciled using weighted regression and demand elasticity analysis.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |