 Black Beer Market
 Size, Share & Growth Forecast to 2033
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 217

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Black Beer Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 43.70 B |
| 2026 | 46.40 B |
| 2027 | 49.30 B |
| 2028 | 52.40 B |
| 2029 | 55.60 B |
| 2030 | 59.10 B |
| 2031 | 62.70 B |

The black beer market covers dark-colored beers brewed with roasted or highly kilned malts — including dark lager, dark ale, brown porter and stout — typically 4–12% ABV, sold through on-trade (pubs, bars, restaurants) and off-trade (retail, e-commerce) channels in cans and bottles.
This analysis covers global black beer volumes and revenues across four product types (dark lager, dark ale, brown porter, stout), two packaging formats (cans, bottles), and on-trade/off-trade distribution, spanning 2025 base-year valuation through 2033. Regional coverage includes North America, Europe, Asia Pacific, Latin America and the Middle East & Africa. This analysis does not cover pale lagers, craft non-alcoholic beer as a standalone category, spirits, wine, or brewing equipment and raw-malt supply markets.
Published estimates for the black beer market span USD 29.3 Billion to USD 40.3 Billion for the 2024 base year, with forecast CAGRs ranging from 3.2% to 8.6%. This spread reflects genuine differences in product scope, channel definition and whether craft-only volumes are isolated.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 51.61 Billion | 2021 base | 2030 | 8.6% | Broad black beer incl. craft ale demand | A published market study |
| USD 55.84 Billion | 2024 (USD 29.29 Bn) | 2032 | 8.40% | Cans/bottles; dark lager, ale, porter, stout | A competing analysis |
| USD 52.20 Billion | 2025 | 2033 | 3.2% | Type, packaging, off/on-trade | A third published estimate |
| USD 56.8 Billion | 2024 (USD 40.3 Bn) | 2034 | 3.5% | Includes end-user split (men/women) | Another published outlook |
Our view: the low-CAGR, high-base-year estimates are more defensible. Global beer consumption grew only ~0.5% in 2024 according to trade association data, and US craft brewer volume sales fell 4% that year — a category cannot compound at 8.4% while its parent market stalls. Our analysis suggests a realistic 2025 base of ~USD 43.7 Billion and a 6.2% CAGR, reflecting premiumization offsetting flat volume.
Black beer segments primarily by product type, with packaging and distribution channel determining margin structure and route-to-market economics. Product type is the dominant revenue driver; packaging is the fastest-shifting preference.
| Parent Segment | Children | Revenue Relevance |
|---|---|---|
| Product Type | Dark Lager, Dark Ale, Brown Porter, Stout | Dark lager ~41.5% share; dark ale ~57.5% in one estimate |
| Packaging | Cans, Bottles | Cans 54.3%–65.5% depending on source |
| Distribution Channel | On-Trade, Off-Trade | Contested: 62.5% on-trade vs 60.3% off-trade |
| End-User | Men, Women | Men ~60.9%, shifting gradually |
Note the dark lager vs dark ale conflict: one study credits dark lager with 41.5% leadership, another gives dark ale 57.5%. This divergence implies definitional overlap in how brown ales are classified — buyers should validate segment boundaries before sizing a launch.
Asia Pacific leads the black beer market with approximately 35.5% of global revenue, driven by a growing consumer base, rising disposable income and surging interest in premium craft styles. Europe follows as the deepest traditional dark-beer consumption base at roughly 30%.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.36% |
| Europe | 0.3% |
| North America | 0.24% |
| Latin America | 0.07% |
| Middle East & Africa | 0.04% |
Geography coverage tree:
| Region | Share | Rationale |
|---|---|---|
| Asia Pacific | 35.5% | Volume scale, urbanization, premiumization |
| Europe | 30.0% | Brewing heritage, per-capita depth |
| North America | 24.0% | Craft maturity, fastest growth (~3.4% CAGR) |
| Latin America | 6.5% | Emerging dark-beer adoption |
| Middle East & Africa | 4.0% | Regulated, low-base markets |
Our analysis suggests Asia Pacific's headline share overstates profit pool quality: average selling prices are lower and on-trade infrastructure thinner than in Europe. Europe remains the highest-value target for premium stout and porter launches.
Growth is driven by craft premiumization and flavor-led exploration among younger drinkers, while volume headwinds from flat overall beer consumption and health-conscious moderation cap the upside.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Craft & premium beer demand | Driver | High | Millennials/Gen Z seek bold, complex flavors |
| Microbrewery expansion | Driver | High | Local supply fuels trial and variety |
| Cans innovation & sustainability | Driver | Medium-High | Portability, freshness, recyclability |
| Emerging-market premiumization | Driver | Medium | Rising disposable income in APAC |
| Flat global beer volumes | Restraint | High | Total beer consumption grew only ~0.5% in 2024 |
| Health & moderation trends | Restraint | Medium-High | Low/no-alcohol substitution pressure |
| Input cost volatility (malt, aluminum) | Restraint | Medium | Compresses craft brewer margins |
The balance: premiumization is winning on value but not on volume. This implies revenue growth will outpace volume growth by roughly 2:1 — a structural signal that operators should optimize for price/mix, not capacity.
The black beer market is fragmented between global brewing majors controlling distribution scale and craft specialists owning flavor credibility. No single vendor exceeds a dominant share.
| Company | HQ | Strategic Position | Moat |
|---|---|---|---|
| Anheuser-Busch InBev | Belgium | Global scale, portfolio breadth | Distribution & shelf access |
| Heineken N.V. | Netherlands | Premium brand equity | Brand & on-trade relationships |
| Asahi Group Holdings | Japan | APAC leadership | Regional route-to-market |
| Carlsberg Breweries | Denmark | European depth | Cost leadership |
| Diageo Plc | UK | Premium portfolio | Cross-category marketing |
| The Boston Beer Co. | USA | Craft credibility | Innovation pipeline |
| Stone Brewing Co. | USA | Craft stout/porter authority | Cult brand following |
| Mikkeller ApS | Denmark | Specialty/contract brewing | Experimentation brand |
| Beavertown Brewery | UK | Craft dark styles | Urban premium positioning |
| Buxton Brewery Co. | UK | Regional craft | Local loyalty |
Differentiation insight: majors win on availability, craft players win on authenticity. The gap is scalable craft credibility — which is why acquisitions and contract-brewing partnerships are the most likely strategic move through 2033.
Procurement decisions in black beer hinge on three variables: liquid stability across packaged formats, channel-specific margin structure, and regulatory labeling compliance across markets. Cans require different dissolved-oxygen and carbonation specifications than bottles, and switching packaging lines carries meaningful capital and validation cost.
On-trade placement is the highest-margin but highest-friction channel — venue listings require draft infrastructure, staff education and distributor relationships. Off-trade offers volume but compresses per-unit margin and demands shelf-space competition against pale-lager incumbents. Operators should model both channels separately rather than applying blended assumptions.
Regulatory risk is meaningful: alcohol labeling, health warnings, advertising restrictions and deposit-return schemes vary materially by country, and emerging markets are tightening. Cross-border sourcing also exposes buyers to tariff and non-tariff measures that public trade databases can quantify but rarely forecast.
The balance of evidence favors moderate-growth premiumization over the aggressive forecasts. A 6.2% CAGR is achievable, but only for vendors positioned in premium dark styles and cans — commodity dark lager will track the flat parent market. The strongest counter-argument is that craft innovation cycles could re-accelerate growth; however, the 2024 craft volume decline in the US argues against that base case.
Our second judgment: the on-trade/off-trade conflict is the most consequential unresolved variable in this market. A vendor building a draft-led strategy on the 62.5% on-trade figure would misallocate capital if the off-trade figure of 60.3% is closer to reality post-pandemic. Readers must resolve this before committing channel investment.
Actionable strategy:
What would change our conclusion: a sustained recovery in craft brewer volumes above 3% annual growth, or regulatory liberalization of alcohol e-commerce in major APAC markets, would justify upgrading to the higher forecast band. Conversely, accelerated no-alcohol substitution would push us toward the 3.2% floor.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.2% from 2020-2034 |
| Segmentation |
|
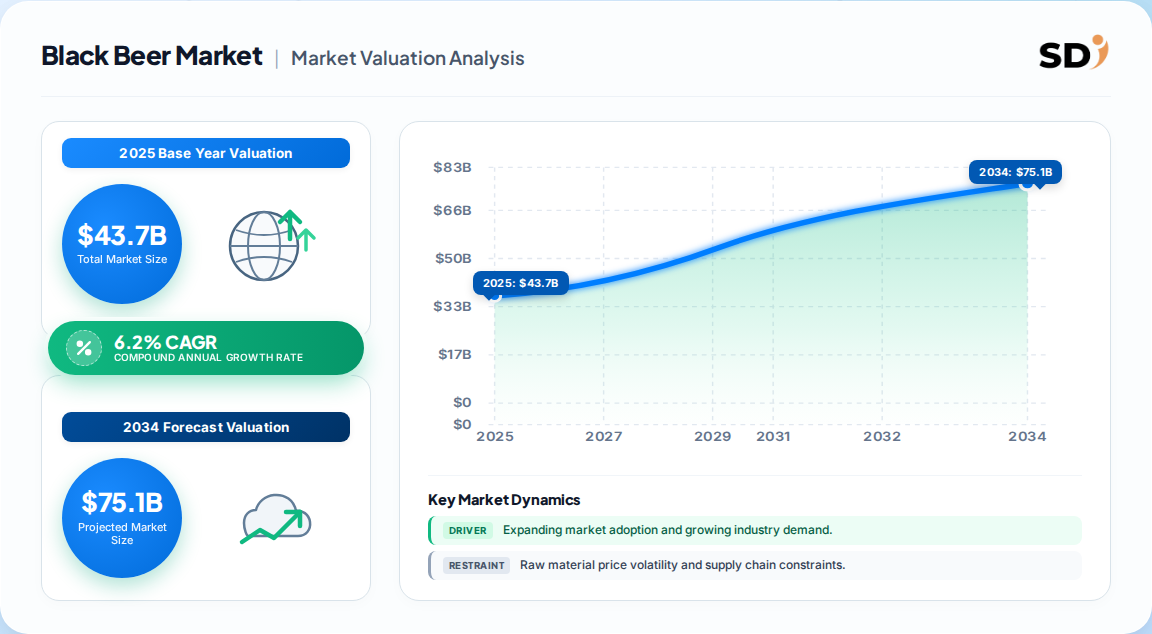
The global black beer market is valued at approximately USD 43.7 Billion in 2025. Published estimates range from USD 29.3 Billion to USD 40.3 Billion for prior base years, with our consensus reflecting premiumization offsetting flat overall beer volumes.
Our consensus CAGR is 6.2% from 2025 to 2033, reaching roughly USD 51.6 Billion. Published forecasts range widely from 3.2% to 8.6%, reflecting differing product scope and channel definitions rather than genuine market disagreement.
Asia Pacific leads with approximately 35.5% of global revenue, driven by urbanization and premiumization. Europe follows at roughly 30% with the deepest traditional dark-beer culture, while North America is the fastest-growing region at about 3.4% CAGR.
Dark lager and dark ale dominate, together holding around 70% of product-type revenue, though sources disagree on which leads. Stout and brown porter occupy the premium craft tier with higher margin but smaller volume.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the black beer value chain, including malt and roasted-grain suppliers, craft and regional breweries, contract brewing and co-packing specialists, can and bottle packaging converters, and national distributors. Decision-makers interviewed spanned VP-level Sourcing, Heads of Brewing and R&D, Technical Directors for packaging and quality, and Commercial Operations Leads responsible for on-trade and off-trade channel strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leaders | 32% |
| Brewing & R&D Directors | 30% |
| Commercial & Channel Operations | 23% |
| Quality & Regulatory Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Malt & Grain Suppliers | 22% |
| Craft & Regional Breweries | 38% |
| Packaging Converters (Cans/Bottles) | 20% |
| Distributors & Retailers | 20% |
Secondary validation drew on official multilateral trade databases including UN Comtrade and the World Bank WITS platform, WTO tariff and non-tariff measure records, national statistics offices, and corporate annual filings (10-K, SEC filings, investor presentations) from listed brewers. Brewing industry associations and trade bodies provided volume and consumption benchmarks. No competing market-research publisher data was used as a validation source.
Market sizing applied simultaneous top-down and bottom-up triangulation. The top-down model allocated macroeconomic beverage spend and total beer consumption to the dark-beer segment by country. The bottom-up model built revenue from brewery capacity, packaged volume, average selling price and end-use channel consumption, then reconciled the two.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |