 Middle East Africa Dietary Supplements Market
 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 208

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Africa Dietary Supplements Market
Sakshi Gurunule
Research Associate

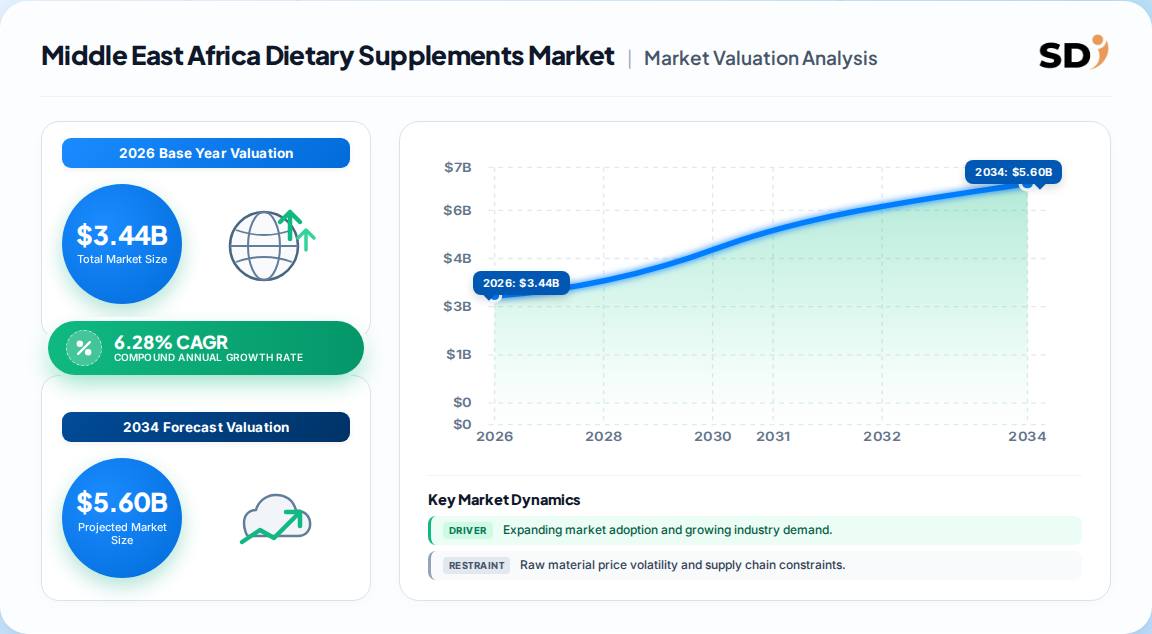
| Year | Market Size |
|---|---|
| 2025 | 3.240 B |
| 2026 | 3.440 B |
| 2027 | 3.660 B |
| 2028 | 3.890 B |
| 2029 | 4.130 B |
| 2030 | 4.390 B |
| 2031 | 4.670 B |

The Middle East Africa dietary supplements market covers concentrated nutritional products — vitamins, minerals, botanicals, proteins, probiotics and specialty formulations — sold in tablet, capsule, powder, gummy and liquid form to consumers seeking to correct nutrient gaps, manage chronic conditions or support general wellbeing across GCC and African economies.
This analysis covers consumer-packaged dietary supplements sold through retail, pharmacy and online channels across GCC, Levant and African markets, segmented by product type, form, end-user, health benefit and distribution channel. Figures are retail-value based. This analysis does not cover functional foods and beverages, sports nutrition sold exclusively through gym channels, clinical infant formula, pharmaceutical drugs, or bulk bioactive ingredients sold to manufacturers.
Two credible estimates diverge materially, so buyers should anchor on the metric definition before the headline number.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 3.44 Billion | 2026 | 2031 (USD 4.67 Billion) | 6.28% | Consumer dietary supplements, retail value, broad MEA | One published estimate |
| USD 4.10 Billion | 2024 | 2030 | 10.3% | Dietary supplements incl. broader ingredient and OTC framing | A competing analysis |
| USD 3.55 Billion (ingredients) | 2025 | 2033 (USD 6.01 Billion) | 6.80% | Bioactive ingredients feeding supplements and functional food | Adjacent-category benchmark |
Our analysis suggests the 6.28% figure is the more defensible planning base. It sits closer to the bioactive-ingredient benchmark (6.80%), and the 10.3% figure likely absorbs adjacent OTC and functional-food revenue. Buyers should plan on mid-single-digit volume growth with high-single-digit value growth driven by premiumization.
Segmentation matters because growth is concentrated in narrow pockets that broad headlines obscure.
| Parent segment | Children | Largest child (share) | Fastest child (CAGR) |
|---|---|---|---|
| Product type | Vitamins & minerals, herbal/botanicals, proteins & amino acids, probiotics, others | Vitamins & minerals (~66%) | Herbal/botanicals (~7.9%) |
| Form | Tablets, capsules, powders, gummies, liquids | Tablets (~31%) | Capsules (~7.3%) |
| End-user | Adults, infants/children, seniors | Adults (~90%) | Infants/children (~7.9%) |
| Health benefit | General health, bone & joint, immunity, metabolic, beauty | General health (~32%) | Bone & joint (~7.8%) |
| Distribution | Pharmacies, supermarkets, online, specialty | Pharmacies (~64%) | Supermarkets (~7.2%) |
| Purchase type | OTC, prescribed | OTC (~53%) | Prescribed |
Saudi Arabia leads absolute value on the strength of high disposable income and preventive-health spending, while Egypt delivers the fastest growth off a larger, more price-sensitive base.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.17% |
| UAE | 0.14% |
| South Africa | 0.13% |
| Egypt | 0.11% |
| Israel | 0.06% |
| Rest of GCC | 0.19% |
| Rest of Africa | 0.2% |
Our analysis suggests the GCC will remain the profit pool while North and Sub-Saharan Africa supply the volume growth. Vendors optimizing only for GCC premium pricing will under-serve the fastest-growing demand and cede share to regional manufacturers.
Chronic-disease burden is the single strongest structural driver, outpacing clean-label and personalization trends in measured impact.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising chronic disease burden (diabetes ~17% of adults in Arab nations) | Driver | High | Sustained metabolic and cardiovascular supplement demand |
| Plant-based and clean-label preference | Driver | Medium | Premium pricing and botanical ingredient adoption |
| Preventive healthcare policy focus | Driver | Medium | Government-led supplementation awareness |
| Product and ingredient innovation | Driver | Medium | Format diversification, functional beverages |
| Personalization demand | Driver | Low-Medium | Urban premium niches only |
| Regulatory fragmentation across markets | Restraint | High | Registration delays and cost per SKU |
| Halal and labeling compliance costs | Restraint | High | Reformulation and certification overhead |
| Price sensitivity in African markets | Restraint | Medium | Limits premiumization outside GCC |
The balance favors growth, but the constraint is compliance throughput rather than consumer appetite. Our analysis suggests regulatory registration capacity — not demand — will be the binding constraint on 2031 revenue realization, which is why the faster-growth sub-segments are also the hardest to enter.
Global multinationals hold brand equity in vitamins and general health, while regional manufacturers compete on price, cultural fit and distribution depth.
| Vendor | Category strength | Differentiation | Competitive moat |
|---|---|---|---|
| Bayer AG | Vitamins, general health | Global brand trust, clinical heritage | Regulatory dossiers and pharmacy relationships |
| Amway Corporation | Multivitamins, wellness | Direct-selling loyalty base | Distributor network lock-in |
| Herbalife Nutrition | Weight management, protein | Community-driven retention | Coach network and localized SKUs |
| Vitabiotics Ltd | Vitamins, specialty nutrition | Premium positioning, format breadth | Brand credibility in GCC pharmacy |
| GlaxoSmithKline PLC | OTC-adjacent supplements | Pharmacy shelf dominance | Medical detailing and trust |
| Regional manufacturers | Botanicals, value tiers | Cultural and botanical fit, local cost base | Halal certification and price |
Differentiation is shifting from brand heritage toward certification, local manufacturing and format agility. This divergence implies the multinational moat is narrowing in mid-price tiers, where regional producers can match quality claims at lower landed cost.
Selection criteria are shifting toward provable compliance. Halal certification is effectively a gating requirement in GCC markets, and non-certified products show materially weaker engagement — treat this as a procurement precondition, not a marketing differentiator.
Procurement risk concentrates in regulatory lead times and SKU registration cost. Each market requires separate dossiers, so portfolio breadth raises fixed cost non-linearly; buyers should model cost-per-SKU-per-country before committing to a wide range. Switching costs are moderate for brands but high for distributors, who carry registration assets and shelf relationships.
Ingredient sourcing carries reputational risk: plant-based and clean-label claims invite scrutiny, and gelatin-derived capsules conflict with halal positioning. Our analysis suggests capsule-format reformulation toward plant-based shells is an under-priced compliance hedge. Finally, e-commerce growth lowers entry cost but compresses price transparency, pushing margin capture toward certified brands with pharmacy anchors.
The balance of evidence favors planning on 6.3–6.8% CAGR, not the double-digit estimate. The higher figure almost certainly includes adjacent OTC and functional-food revenue, and the bioactive-ingredient benchmark corroborates mid-single-digit growth. The strongest counter-argument is that formalization of African retail and rapid e-commerce adoption could unlock latent demand faster than historical growth implies — a genuine upside risk, but one concentrated in volume tiers where margins are thinnest.
Positioning should follow the profit pool, not the headline growth. Growth is fastest in herbal, pediatric and bone-and-joint segments, and in Egypt; profit remains in GCC pharmacy-led vitamins. Vendors that chase only growth will trade margin for volume; vendors that chase only GCC premium will miss the next decade's volume base.
Actionable strategy:
Evidence that would change this conclusion: a sustained acceleration in African retail formalization, or region-wide mutual recognition of supplement registrations, which would collapse the compliance constraint and validate the higher growth path.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.28% from 2020-2034 |
| Segmentation |
|
One published estimate values the market at USD 3.44 billion in 2026, rising to USD 4.67 billion by 2031 at 6.28% CAGR. A competing analysis reports USD 4.10 billion for 2024 with 10.3% growth, reflecting broader category inclusion.
Saudi Arabia leads in absolute value with roughly 17% share, supported by high disposable income and preventive-health spending. Egypt is the fastest-growing country, forecast near 7.5% CAGR through 2031.
Herbal and botanical supplements grow fastest at about 7.9% CAGR, alongside infant and children's supplements at approximately 7.9%. Bone and joint health is the fastest-growing benefit category at around 7.8%.
Halal certification is effectively a commercial precondition across GCC markets. Non-certified products show materially lower consumer engagement, and gelatin-based capsules in particular require reformulation or plant-based shell alternatives to compete.
Pharmacies and drug stores control roughly 64% of distribution value, reflecting trust and medical endorsement. Supermarkets and hypermarkets are the fastest-growing channel at about 7.2% CAGR, with e-commerce expanding accessibility.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the supplement value chain with raw material and botanical extract suppliers, specialized supplement manufacturers, contract formulators and capsule-shell producers, and regional distributors serving GCC and African pharmacy networks. Interviewees included VP-level Sourcing leads, Heads of R&D and formulation, Technical Directors, Regulatory Affairs Managers and Commercial Operations Leads. Fieldwork captured registration lead times, Halal certification pathways, shelf-acceptance criteria and pricing architecture across Saudi Arabia, the UAE, Egypt and South Africa.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Directors | 30% |
| Regulatory & Quality Leads | 25% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Supplement Manufacturers & Brand Owners | 40% |
| Botanical & Ingredient Suppliers | 25% |
| Contract Formulators & Encapsulators | 20% |
| Regional Distributors & Pharmacy Chains | 15% |
Secondary validation drew on UN Comtrade and WTO tariff and trade-flow data, national customs statistics, corporate annual filings and investor presentations, patent databases covering botanical extraction and delivery formats, and recognized technical standards bodies including ISO food-safety frameworks and CODEX-aligned labeling guidance. Regional food and drug registration authorities were reviewed for compliance timelines. No third-party market-research publisher data is cited in the validation layer.
Top-down sizing allocated macroeconomic health expenditure and consumer nutrition spend to supplement categories by country. Bottom-up modeling built revenue from manufacturer capacity, unit pricing and end-use consumption across pharmacy and modern trade. Both paths were reconciled to a single base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |